


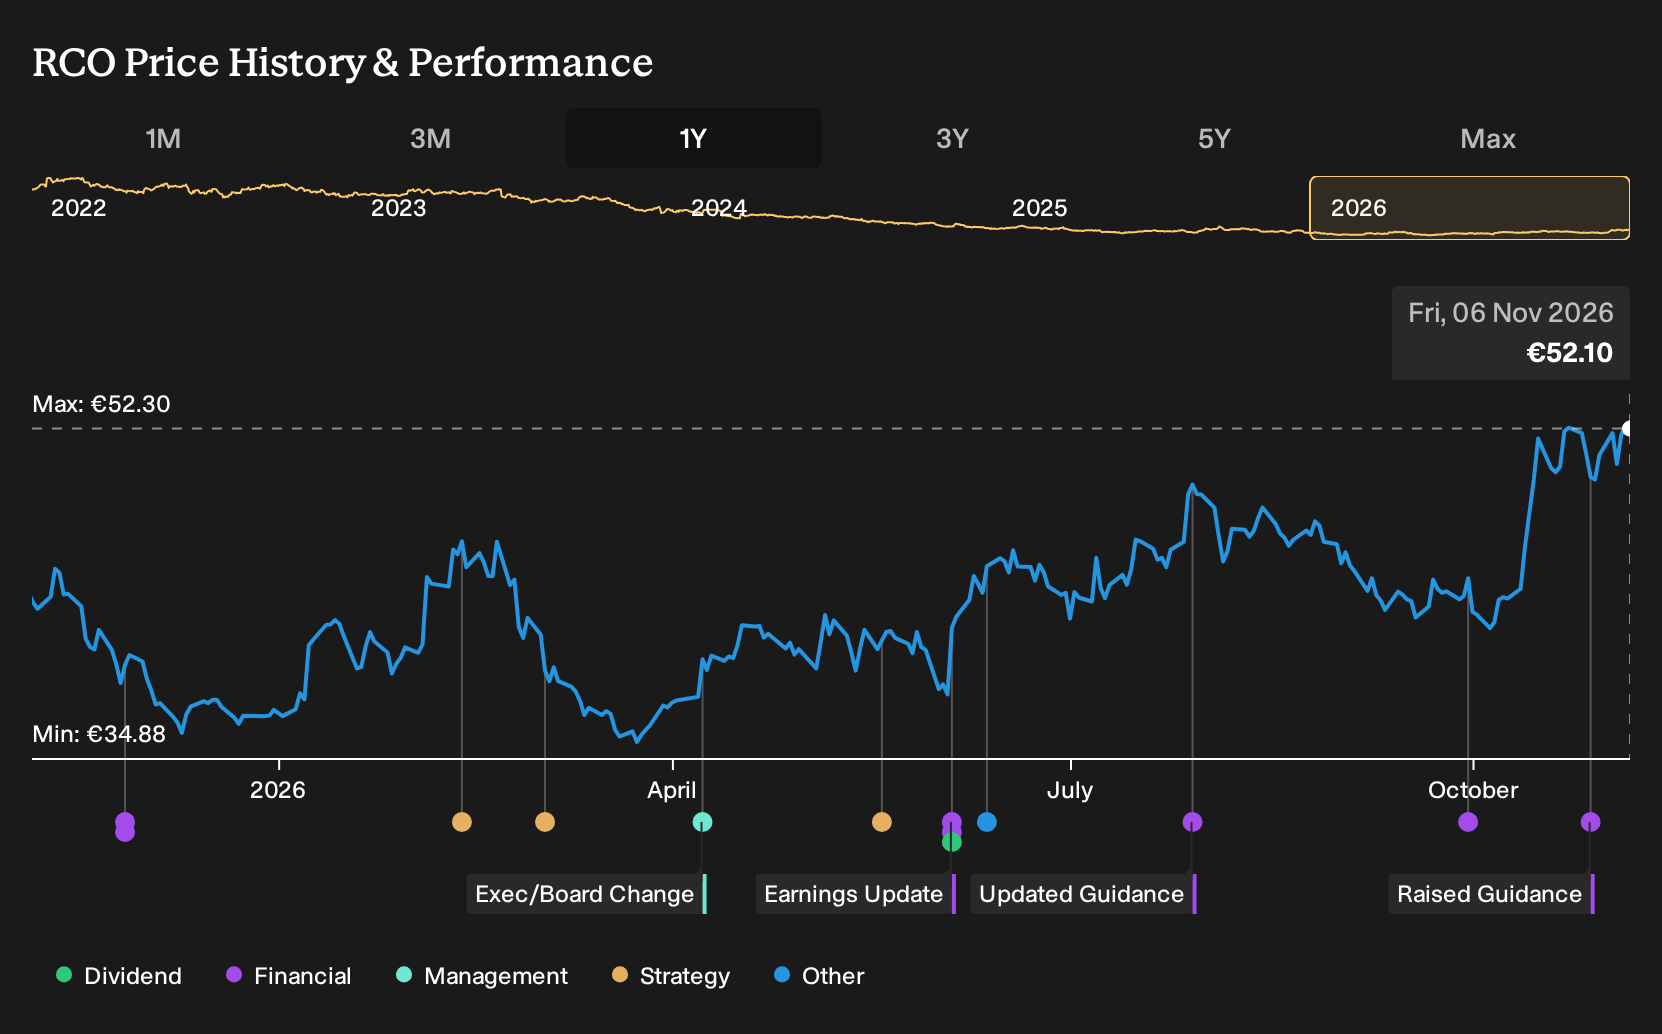
- Rémy Cointreau updated its 2026 guidance after the October 2026 announcement, now expecting a positive currency effect of about €15 million on sales and between €3 million and €5 million on current operating profit instead of prior anticipated currency headwinds.
- The shift from forecast currency pressure to a projected earnings tailwind points to management confidence in the group’s pricing, cost control and RC Forward execution, despite what it still calls a particularly volatile backdrop.
- We will now look at how Rémy Cointreau's upgraded positive currency effect guidance could reshape the existing RC Forward investment narrative.
Compare Rémy Cointreau’s upgraded currency outlook with other potential opportunities by scanning our hand picked 224 high quality undervalued stocks that also combine pricing power with resilient balance sheets.
Rémy Cointreau Investment Narrative Recap
To own Rémy Cointreau, you need to believe premium spirits branding, RC Forward execution and tighter capital discipline can offset recent pressure on profitability and uneven regional performance. The raised 2026 currency guidance improves the near term backdrop but does not change the central question. Can management convert high advertising spend and large inventories into stronger operating profit and cash generation?
The key short term catalyst still sits in margin and free cash flow delivery after current operating profit fell 11.5% organically and margin moved to 17.7%. The biggest risk remains that earnings recovery lags while net debt of €690.4m and inventories of €2.17b keep leverage and financing costs elevated despite the more favourable FX outlook.
The most relevant context for this currency update is the RC Forward plan, which targets €100m of gross current operating profit value creation by FY28-29. A swing from expected FX headwinds to an indicated tailwind of about €15m on sales and €3m to €5m on current operating profit gives the program a little more room, but execution around cost, mix and volume still does the heavy lifting.
For you as an investor, the interesting angle is how this interacts with rich valuation markers, such as a 34.7x P/E compared with both industry and internal fair value estimates, and with a balance sheet carrying net debt at 3.22x EBITDA. If FX now helps rather than hurts, attention may sharpen on whether organic sales, non-Cognac expansion and working capital actions can improve returns on equity from the current 4.1% level without relying on currency support.
Rémy Cointreau's narrative projects €1.1b revenue and €117.4m earnings by 2029. This assumes 4.3% yearly revenue growth and an earnings increase of about €38.7m from current earnings of €78.7m.
Uncover why Rémy Cointreau's fair value indicates a 13% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
One alternate take focuses on earnings power rather than FX. The most pessimistic analysts were working with only €1.0b revenue and €84.0m earnings by 2029 for Rémy Cointreau, assuming margins edge down to 8.2%. That is a much harsher story than consensus, and the fresh currency guidance could push both narratives to evolve. Consider both perspectives before deciding which you find more convincing.
Explore 2 other Rémy Cointreau fair value estimates, including one that suggests as much as 33% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Rémy Cointreau research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rémy Cointreau. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rémy Cointreau's overall financial health at a glance.
Looking For More Investment Ideas Beyond Rémy Cointreau?
If the Rémy Cointreau story has sharpened your thinking on pricing power, balance sheets and cash generation, it can be useful to test that framework on a wider watchlist. The Simply Wall St Screener lets you scan for stocks that better match your own risk tolerance, income needs and quality filters, rather than anchoring only on a single luxury spirits group.
- For investors who want quality at a sensible entry point, start with companies that pass strict value and fundamentals checks using our 224 high quality undervalued stocks.
- If capital preservation and smoother swings matter most to you, narrow the field to businesses with sturdier financial positions through the 212 resilient stocks with low risk scores.
- When you are hunting for future leaders with strong under the radar potential, broaden your opportunity set with the 588 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com