


Tech shares have been hit hard after fresh concerns about an AI slowdown and tighter financial conditions, which has pushed many investors toward cash flow strength and more grounded expectations. That pullback can leave some Australian companies with solid cash generation trading below what detailed discounted cash flow work suggests is fair. This article highlights three such stocks from our cash flow value screener that could interest patient bargain hunters.
The three stocks below are just a sample from this cash flow value theme, and the full screen surfaced 4 more Australian companies with equally grounded stories that are not covered here. To size up the full field and identify which ideas best match your own conviction level, head straight into the Undervalued Stocks Based On Cash Flows screener.
Greatland Resources (ASX:GGP)
Overview: Greatland Resources is a gold and copper miner focused on the Havieron project in Western Australia, where potential production underpins cash flow valuations.
Operations: Greatland Resources generates A$2.26b in revenue from its Telfer-Havieron segment, supported by sales mainly into China and the rest of Asia.
Market Cap: A$6.94b
Greatland Resources appeals to this cash flow focused screen because the Havieron gold copper project is shifting from exploration story to producing asset, which makes projected mine economics far more central to how investors assess value.
"The primary driver of Greatland’s future is the gold price. As a single-asset developer moving toward production, it offers significant operational leverage to gold."
Margins and valuation both hinge on how one moving part in that transition behaves once production meets the real-world cost and pricing cycle.
As that single variable plays out, the full narrative for Greatland Resources maps how cash flows, funding risks and gold price sensitivity could be decoupling from market expectations.
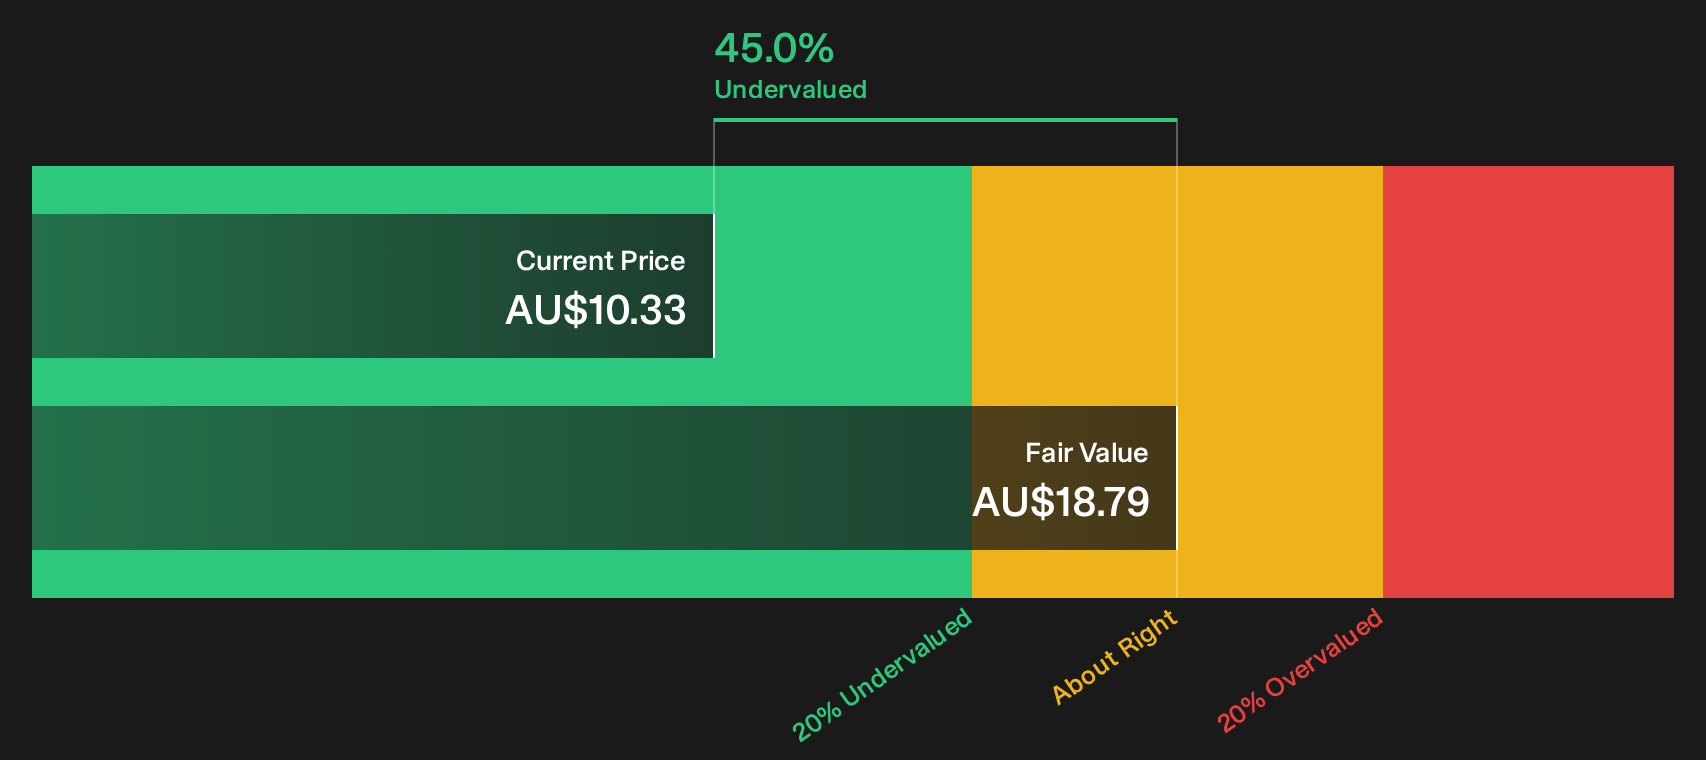
Woodside Energy Group (ASX:WDS)
Overview: Woodside Energy Group is a Perth based hydrocarbon producer, with LNG projects such as Pluto, North West Shelf and Wheatstone contributing to cash flow.
Operations: Woodside Energy Group generates about $7.29b from Australia, $4.62b from international operations and $1.93b from marketing activities annually.
Market Cap: A$58.44b
For investors focused on cash flow driven value, Woodside Energy Group matters because its LNG projects provide recurring volumes that feed directly into discounted cash flow models and support the idea of a cash generative energy portfolio.
"Expectations that Woodside Energy Group will bring the Scarborough project into production around Q4 2026 and ramp up volumes support the idea that future LNG sales and associated revenue are already partially reflected in the current valuation."
What happens if a still underappreciated shift in how that LNG cash flow is shared between new projects, debt and dividends pulls margins in a different direction?
That tug of war sits at the centre of the full narrative for Woodside Energy Group, which lays out how Woodside Energy Group’s cash engine could accelerate or stall under different capital allocation paths.
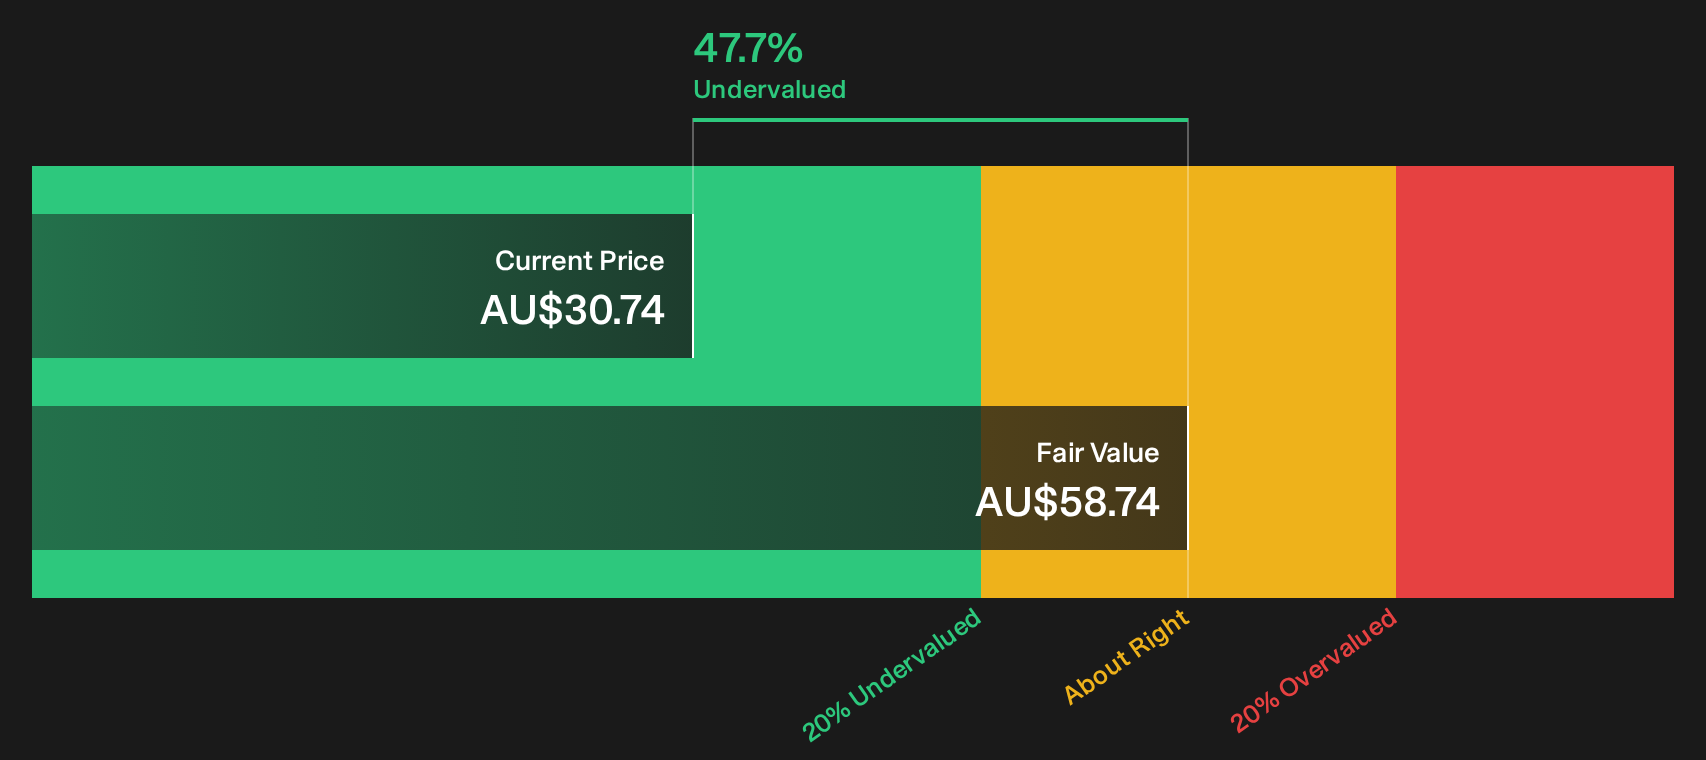
Origin Energy (ASX:ORG)
Overview: Origin Energy is an integrated Australian utility that earns most of its value from cash-generating electricity and gas retailing, generation and LNG activities.
Operations: Origin Energy generates about A$15.26b from its Energy Markets division and A$307 million from Integrated Gas and related activities.
Market Cap: A$20.82b
Origin Energy matters for this cash flow focused list because its mix of retail energy, generation and LNG assets turns customer demand into relatively visible operating cash that anchors DCF style valuation work.
"Continued growth in rooftop solar, home batteries and the 1.6 GW virtual power plant, supported by rising adoption of customer electrification products, can shift more consumption behind the meter and reduce grid supplied volumes. This affects wholesale and retail earnings visibility."
The real test for Origin Energy is how one pressure on future margins interacts with the discounted cash flow upside investors are currently watching.
If that pressure point matters to you, the full narrative for Origin Energy shows how Origin Energy’s cash engine could still accelerate as the energy system rewires.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the best breakout ideas rarely stay quiet for long. Use these fresh screens while the data still matters and sentiment has not fully caught up. Act now.
- Spot resilient balance sheets before momentum traders arrive by scanning the curated list of solid balance sheet and fundamentals (12 results) that highlights businesses built to handle tougher funding conditions.
- Hunt for income ideas while yields remain elevated with a focused pass through the 5 dividend fortresses that zeros in on sturdier high payout candidates.
- Track early leaders in next generation computing by running the targeted 25 quantum computing stocks and see which specialists still trade under the broader market’s radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com