


agilon health has seen its share price surge over the past year, which puts a lot of focus on whether the current valuation lines up with the sales the business is generating. With such a sharp move behind it, the question now is how the stock price stacks up against what the company produces in revenue.
- Over the past 12 months the stock has delivered a very large gain of around 7x, which puts extra weight on whether recent enthusiasm is supported by the underlying sales base.
- Recent revenue and profit performance came in ahead of market expectations, which may support investor hopes for stronger future sales productivity and improved earnings power on each dollar of revenue.
- There is a second opinion on agilon health worth weighing. See what analysts think agilon health's shares could be worth.
The issue now is whether agilon health's current share price is justified by its sales given this mix of past returns and recent business results.
If you want to pressure test whether agilon health's sales-based valuation question applies elsewhere, compare it with other companies screened for 39 high quality undervalued stocks
Where Does agilon health Sit on Sales?
P/S fits agilon health because investors are currently focusing on how efficiently it turns each revenue dollar into value after a strong share price move.
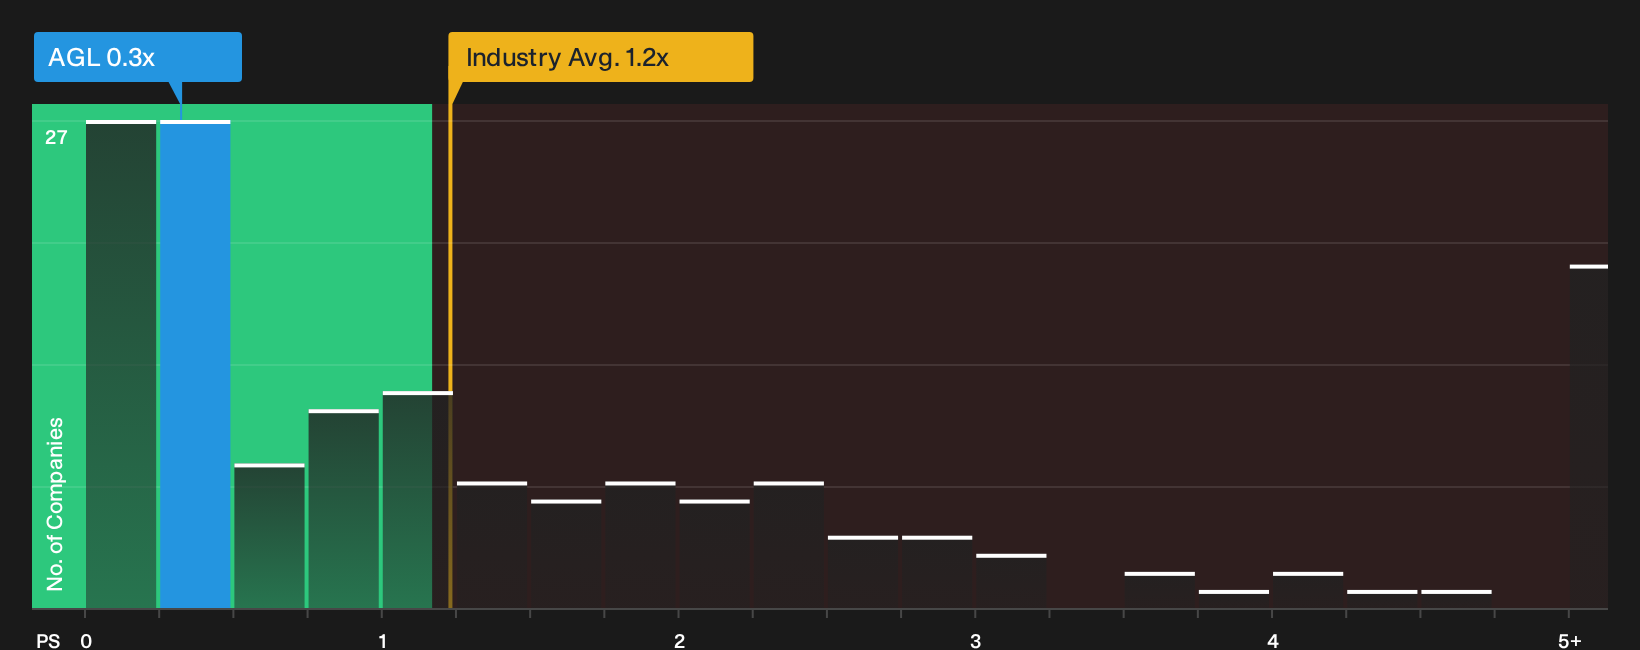
The stock trades on a P/S of about 0.3x, which is well below both the Healthcare industry average of roughly 1.2x and the peer group near 1.8x. That level also sits close to the multiple implied by a fair-value model that blends agilon health's growth outlook, margins, size and risk profile. Because the recent Q3 2026 update showed revenue and earnings ahead of expectations, this kind of discount suggests the market is still cautious about how durable those results are.
For you as a shareholder or potential buyer, the key question is whether that lower P/S reflects genuine concerns about future execution or a gap between sentiment and the current revenue base. Explore the numbers behind agilon health's P/S valuation.
The agilon health Narrative: What Would Justify Today's Price?
Narratives pick up where agilon health's valuation puzzle leaves off by laying out which paths for growth, margins and earnings would need to hold for the stock to be worth much more or much less than it is today on Simply Wall St's Community page. Instead of a single P/S or model result, Narratives spell out the future that number relies on so you can track over time whether agilon health's progress still fits that picture.
Community views on agilon health are split between those who see disciplined risk execution creating upside and those who worry membership and mix pressures are already reflected in the price.
Bull case: roughly fairly valued
"The shift to profitability-focused growth, including lower Medicare Part D exposure at less than 15% of the book and tighter contracting with payers, can reduce earnings volatility and help translate agilon health’s higher medical margin guidance into more predictable adjusted EBITDA and operating cash flow…"
Discover why this Narrative puts agilon health at roughly fairly valued.
Bear case: 33% overvalued
"Although agilon health is leaning more on Traditional Medicare ACO models, including REACH and new Senior Health Connect partnerships, the recent Medicare Advantage membership decline indicates that shifting mix toward ACO arrangements could replace higher revenue premium lives with lower revenue fee based contracts…"
Explore why this Narrative puts agilon health at 33% overvalued.
One big agilon health question still hangs over today’s price
Everything circles back to what people think this business could look like a few years from now, and professional estimates offer a different lens to compare with today’s market value. Explore where analysts expect agilon health to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com