


CONMED (CNMD) just paired higher third quarter earnings with a small trim to full year sales guidance, giving investors a mixed update on profitability and growth momentum as of late October 2026.
Against that backdrop, CONMED’s share price has moved to US$51.50, with a 7 day share price return of 16.28% and a 30 day share price return of 16.44%. This suggests a burst of momentum around the earnings release, even though the 3 year total shareholder return has fallen 46.50% and the 5 year total shareholder return has declined 64.70%. This points to a longer period where investors have been cautious despite the recent rebound.
Spot opportunities beyond CONMED by scanning a curated 19 high quality undiscovered gems that may be quietly rebuilding momentum after tough multi year share price stretches.CONMED now looks like a stronger earnings story than its long term share chart suggests. After this sharp rebound to US$51.50, is the stock still cheap, or has the valuation already reset?
Most Popular Narrative: 13% Overvalued
The most followed CONMED valuation storyline pegs fair value around $45.50, which sits below the latest $51.50 close. This frames today’s jump as stretching slightly ahead of that anchor.
CONMED’s decision to exit lower growth gastroenterology lines and concentrate capital and commercial resources on high growth, high margin platforms such as AirSeal, Buffalo Filter and BioBrace sharpens the product mix. This can support organic revenue growth and improve consolidated gross margin and earnings.
See why 3 investors see CONMED as 13% overvalued.
Using that framework, analysts apply an 8.6% discount rate and assume revenue of about $1.6b and earnings of $179.7m by 2029, with CONMED trading on an 8.8x P/E at that point. Those inputs produce the $45.50 fair value marker, which treats the current price as baking in a bullish tilt rather than leaving a large margin of safety.
Result: Fair Value of $45.50 (OVERVALUED)
Still, this bullish CONMED storyline can break if organic sales keep undershooting guidance or if higher interest costs quietly eat into cash generation.
Find out about the key risks to this CONMED narrative.
Another View: CONMED Looks Cheap On Earnings
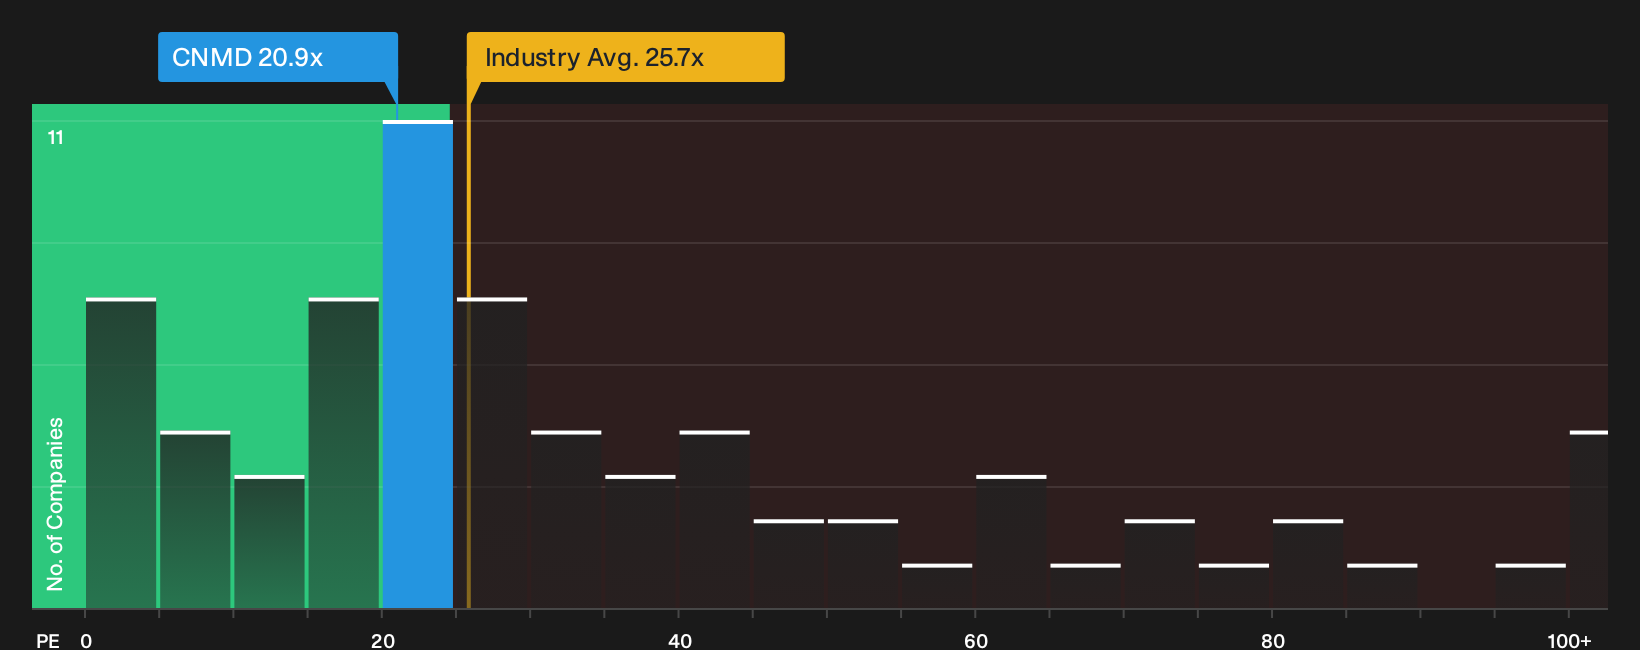
The narrative around CONMED paints the stock as roughly 13% overvalued at $51.50, yet the earnings based lens points in a different direction. At a P/E of 20.9x versus peers at 48.5x and a fair ratio of 26.4x, the gap hints at either caution or opportunity. Which side of that trade do you think it reflects?
For a closer look at how this valuation stacks up against similar medical equipment stocks, and how the current P/E compares with the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this CONMED story feels pulled in two directions, use that tension as a prompt to move fast and inspect the numbers yourself. To see both the potential upside and the key concerns in one place, review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond CONMED?
CONMED is only one piece of your portfolio puzzle. The real edge often comes from lining up several high quality ideas side by side.
- Zero in on resilient potential by focusing on businesses that pair staying power with measured risk using the 29 resilient stocks with low risk scores.
- Hunt for pricing mismatches where quality and valuation still look appealing by scanning the 39 high quality undervalued stocks.
- Balance return and resilience by reviewing companies with strong finances through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com