


Equinox Gold (TSX:EQX) moved sharply after investors reacted to higher Canadian gold production and progress at the Valentine mine, even as broader markets absorbed weak activity data and awaited key Canadian jobs numbers.
That sharp reaction fits into a mixed year for Equinox Gold, with a 7 day share price return of 19.85% contrasting with a year to date share price decline of 13.80% and a modest 1 year total shareholder return fall of 0.57%.
Scan how Equinox Gold compares to other producers benefiting from renewed interest in precious metals by reviewing the hand picked 33 elite gold producer stocks.
The jump in Equinox Gold shares raises a simple puzzle. Are investors responding to tangible progress at mines such as Valentine, or are they primarily re-rating the story based on sentiment as the valuation case faces its next test?
Most Popular Narrative: 34% Undervalued
On the most followed view, Equinox Gold’s CA$16.24 share price sits well below a fair value estimate of about CA$24.52, which puts execution at its newer mines and acquired assets under the spotlight.
Successful integration of Orla Mining and Calibre assets into Equinox Gold, with the combined portfolio expected to produce about 1.1 million ounces of gold in 2026 and a clear organic path toward roughly 1.9 million ounces annually, points to a larger production base that can support higher revenue and operating cash flow as more of that capacity is brought on line.
See why 54 investors see Equinox Gold as 34% undervalued.
Result: Fair Value of CA$24.52 (UNDERVALUED)
Still, Equinox Gold’s story can be knocked off course if higher capital spending at projects like Valentine, or persistent cost inflation, keeps squeezing cash generation and delays investor patience.
Find out about the key risks to this Equinox Gold narrative.
Another Angle on Equinox Gold’s Valuation
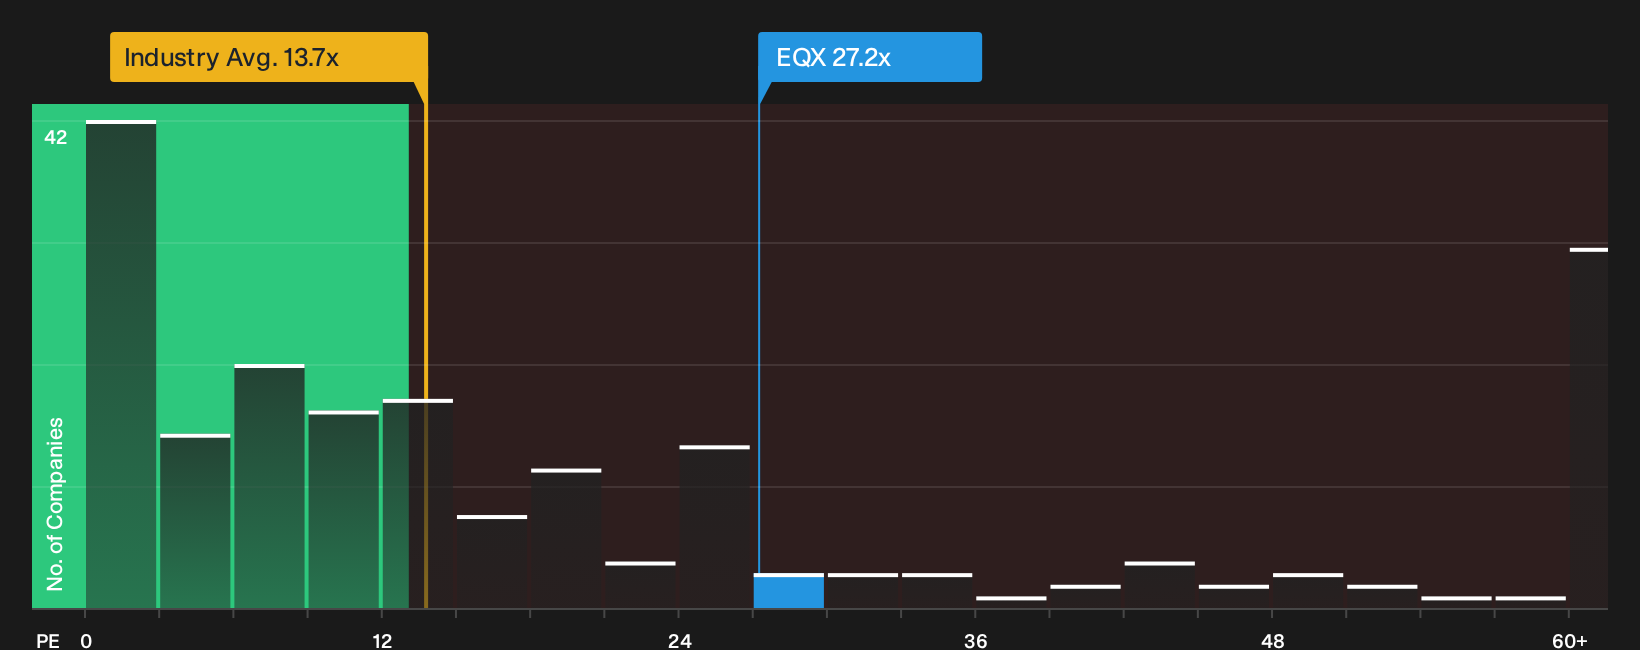
The first view leans on future earnings and analyst targets, but the market is currently paying a P/E of 27.2x for Equinox Gold compared with a fair ratio of 19.5x, the Canadian Metals and Mining industry at 13.7x and peers at 14.7x. That richer multiple may signal that the bigger risk is overpaying for the story rather than underestimating it, so how comfortable are you with that gap?
For a closer look at what this pricing gap could mean in practice, including how it might close over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Equinox Gold can feel messy, so move quickly, review the underlying numbers, and weigh both sides of the debate using the 3 key rewards and 1 important warning sign.
Looking for more Equinox Gold sized opportunities?
If Equinox Gold has sharpened your focus on where capital goes next, do not stop here. Broaden your watchlist with other ideas that match your risk and return preferences.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (5 results) that could handle tougher conditions without breaking stride.
- Hunt for mispriced quality by reviewing the 6 high quality undervalued stocks that might offer stronger fundamentals than their current valuations suggest.
- Boost the income side of your portfolio by examining the 3 dividend fortresses built around higher yield payers focused on regular cash returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com