


Maravai LifeSciences Holdings (MRVI) just tightened the spotlight on its 2026 outlook by lifting full year revenue guidance, while also reporting third quarter results that showed higher sales and a smaller net loss than a year earlier.
That guidance lift comes after a powerful run in Maravai LifeSciences Holdings’ shares, with a year to date share price return of 121.18% and a 1 year total shareholder return of 162.02%. However, the 5 year total shareholder return is still down 80.01%, which suggests that recent momentum reflects a reset in expectations rather than a smooth long term climb.
Scan how investors are pricing similar sentiment shifts by reviewing the hand picked 19 high quality undiscovered gems, which, like Maravai LifeSciences Holdings, sit at the intersection of fresh guidance and changing expectations.
Bulls see a leaner Maravai LifeSciences Holdings with guidance pointing up, while bears point to ongoing losses and a rough 5 year track record. Which story do the current valuation markers support?
Most Popular Narrative: 12% Undervalued
Maravai LifeSciences Holdings' most followed narrative pegs fair value at $8.50, slightly above the latest close at $7.52. This frames the current rally as investors leaning into improving fundamentals rather than pure speculation.
The main thing that has to go right is that non COVID mRNA demand and the Cygnus HCP and ELISA kit and services portfolio continue to absorb capacity and support recurring, higher margin revenue as COVID CleanCap contributes a smaller share.
See why 3 investors see Maravai LifeSciences Holdings as 12% undervalued.
Result: Fair Value of $8.50 (UNDERVALUED)
Still, the Maravai LifeSciences Holdings story can break if non COVID mRNA and Cygnus demand softens, or if lumpy GMP orders keep cash flows unpredictable.
Find out about the key risks to this Maravai LifeSciences Holdings narrative.
Another View: What Multiples Say About Maravai LifeSciences Holdings
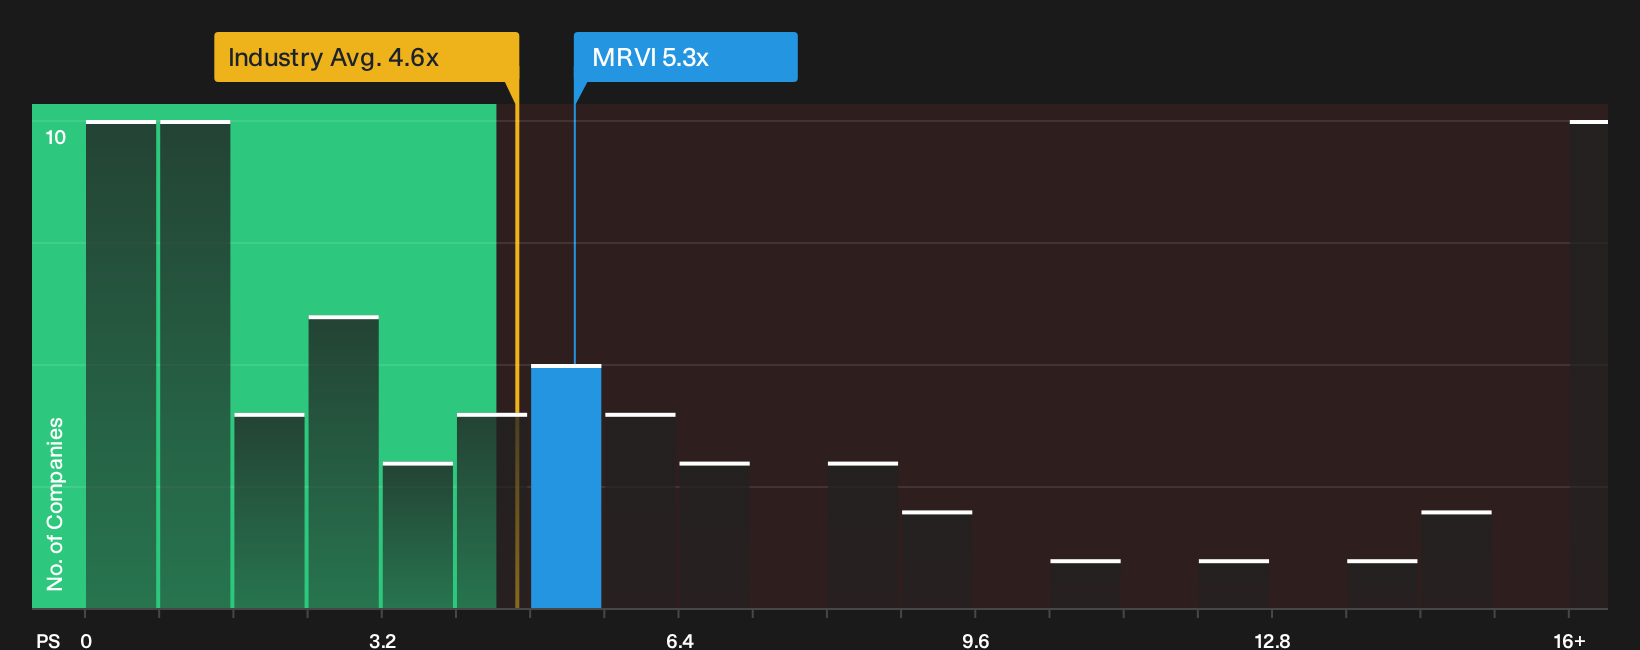
There is a very different read if you look at Maravai LifeSciences Holdings through its sales multiple. The stock trades on a P/S of 5.3x, compared with a fair ratio of 3.2x, the US Life Sciences average at 4.3x and peers around 10.5x. Does that mix of premium to fair value but discount to peers suggest more upside, or more downside risk if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The split between an undervalued story and a punchy P/S tag is clear enough. This is the moment to pull up the data, pressure test Maravai LifeSciences Holdings against your own thresholds, and weigh that profile against the 2 important warning signs.
Looking for more investment ideas beyond Maravai LifeSciences Holdings?
If Maravai LifeSciences Holdings has your attention, use this momentum to refresh your broader watchlist with structured ideas rather than chasing headlines.
- Target potential mispricing by scanning the 39 high quality undervalued stocks that combine robust fundamentals with prices that trail underlying business quality.
- Strengthen your income stream by reviewing the 8 dividend fortresses that pair higher yields with more resilient payout profiles.
- Dial down volatility risk by focusing on the 29 resilient stocks with low risk scores that screen for steadier balance sheets and more predictable financial traits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com