


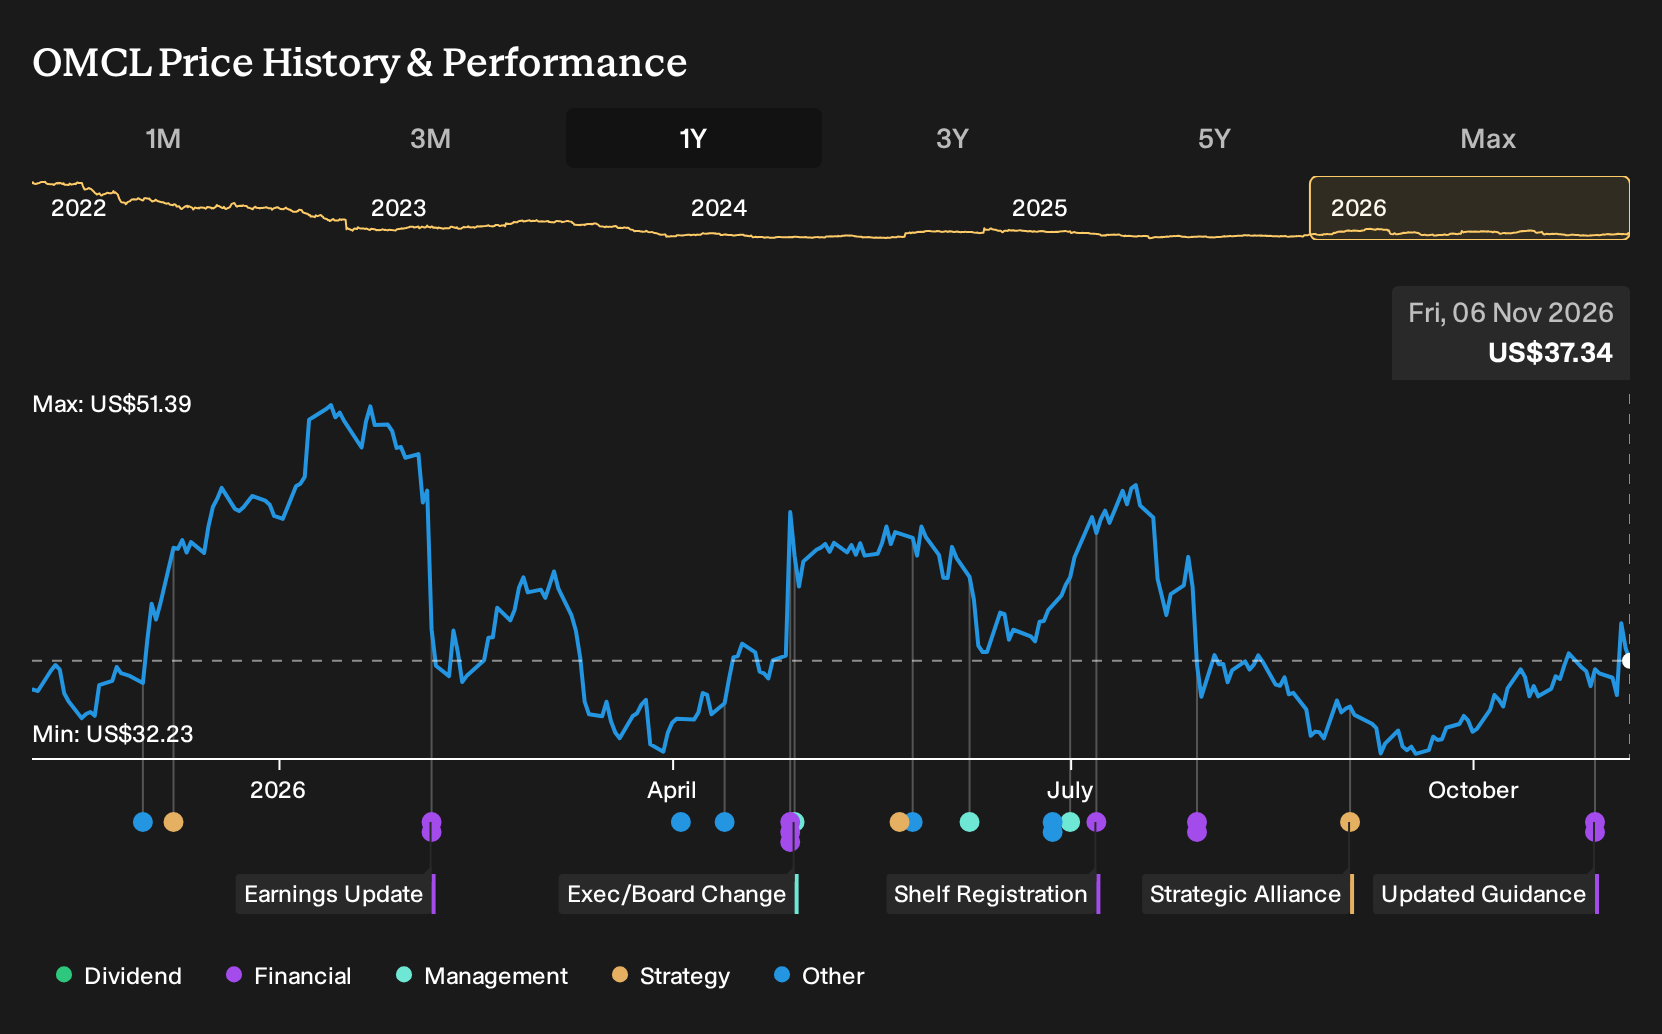
- Omnicell reported third quarter 2026 revenue of US$307.85 million with net income of US$11.04 million and raised full year 2026 revenue guidance to a range of US$1.225b to US$1.231b.
- The sharp rise in year to date net income relative to modest revenue movement highlights how cost discipline and mix are influencing Omnicell's earnings power.
- This article examines how Omnicell's stronger year to date profitability and updated 2026 revenue outlook shape the broader investment narrative.
Omnicell Investment Narrative Recap
To own Omnicell, you need to buy into a story where hospitals and pharmacies keep leaning on automation, software and services to handle rising medication complexity. The latest quarter supports an earnings reset more than a growth reset. Revenue sat roughly flat year on year, while profit improved, which keeps the near term focus on execution and efficiency rather than breakneck expansion.
The key short term swing factor is whether Omnicell can keep lifting earnings through mix, pricing and cost control while tariff pressure, capital spending pauses at hospitals and competitive launches remain on the table. The quarter does not remove those risks, but it suggests the current operating plan is holding together.
The most relevant update here is Omnicell's new 2026 revenue outlook of US$1.225b to US$1.231b, plus fourth quarter guidance of US$295 million to US$301 million. That range frames what management thinks is realistic given current orders, implementation capacity and customer decision timing. It also gives you a reference point for how tight or loose execution may be in the next few quarters.
When you line that guidance up against the recent jump in year to date net income, the story leans more on margin quality than headline sales acceleration. For investors following catalysts around OmniSphere rollout, SaaS mix and services adoption, the guidance and profit run rate together offer a way to judge whether tariff costs, regulation and hospital budget pressure start to bite or remain manageable operational headwinds.
Omnicell's current analyst framework points to revenue growing by 2.7% a year, reaching US$1.3b in sales and US$63.1 million in earnings by 2029. This implies an earnings increase of about US$18.4 million from US$44.7 million today.
Discover how Omnicell's fair value indicates a 54% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Omnicell’s Titan XT and OmniSphere rollout as a catalyst. Before this latest report, they were pencilling in revenue growth of about 4.5% a year and earnings of roughly US$88.6 million by 2029. If those forecasts change after this quarter, the story you follow could look very different.
Explore 3 other Omnicell fair value estimates, including one that suggests up to 87% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Omnicell research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Omnicell. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Omnicell's overall financial health at a glance.
Looking For More Investment Ideas Beyond Omnicell?
If Omnicell is just one position on your watchlist, it can help to cross check your thesis against other businesses with different strengths. The Simply Wall St Screener lets you filter for balance sheet quality, income potential, or mispriced opportunities so you can see where Omnicell fits in your broader portfolio plan.
- For investors who want potential upside backed by stronger fundamentals, compare Omnicell with a curated set of quality companies using the 39 high quality undervalued stocks.
- If capital preservation sits high on your agenda, contrast Omnicell's risk profile with a 29 resilient stocks with low risk scores that screens for resilience and healthier financial footing.
- To widen your opportunity set beyond well known tickers, set Omnicell alongside a 19 high quality undiscovered gems that highlights under followed businesses with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com