


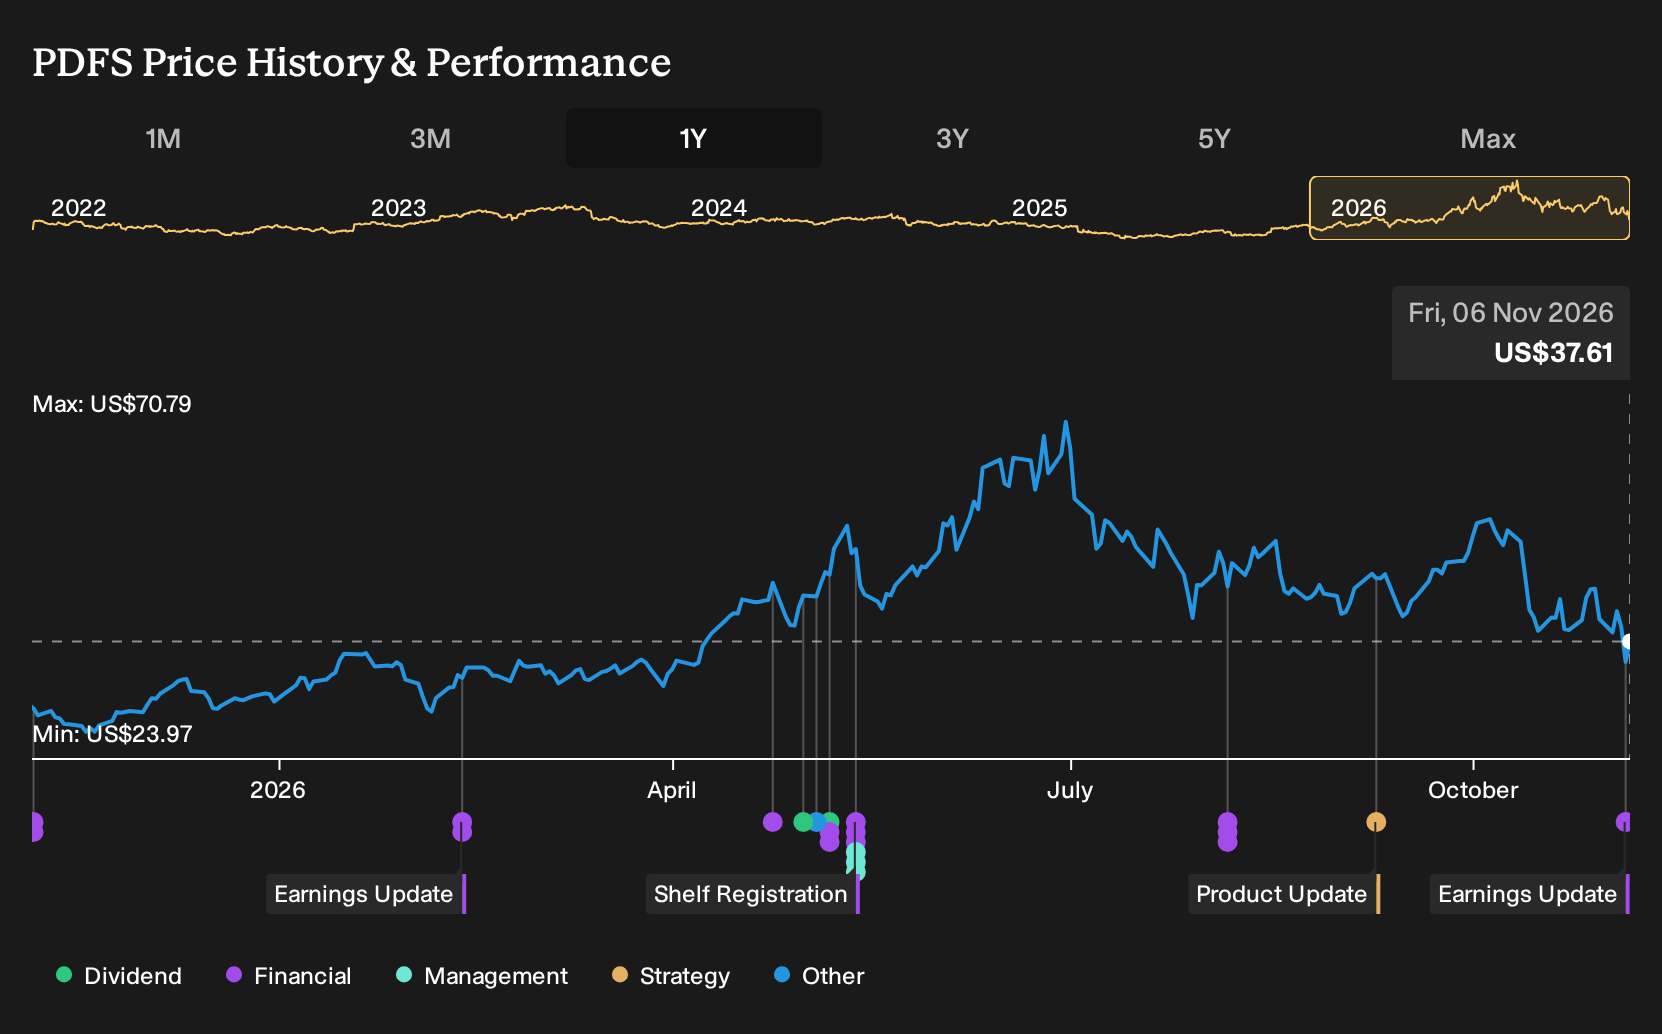
- PDF Solutions reported third quarter 2026 revenue of US$68.33 million and net income of US$6.84 million, with basic and diluted EPS from continuing operations of US$0.16, compared with US$0.03 a year earlier.
- Across the first nine months of 2026, PDF Solutions shifted from a small net loss a year ago to US$15.9 million in profit, indicating that its data and AI oriented semiconductor tools are gaining commercial traction as contract wins and new products such as Exensio Aurora scale.
- Attention now turns to how this earnings beat, supported by record quarterly revenue, may influence PDF Solutions' investment narrative for long term holders.
Scan how PDF Solutions’ AI focused semiconductor tools compare with other potential breakouts across our hand picked 41 AI small caps.
PDF Solutions Investment Narrative Recap
To own PDF Solutions, you need to be comfortable with a story built on AI driven semiconductor manufacturing tools, recurring software subscriptions and capital intensive eProbe hardware. The latest quarter supports that narrative, with record revenue, higher net income and continued traction in data centric platforms. For the near term, the key catalyst is execution on large AI and analytics contracts such as the recent eight figure eProbe deal and multiple seven figure agreements that test whether demand stays broad based.
The biggest operational risk still sits in the heavy R&D and CapEx load tied to eProbe and DirectScan. Quarterly CapEx around US$14.1 million, plus rising component and compute costs, leaves little room for error if volume based revenue or gainshare soften. The Q3 earnings beat does not remove that risk yet; it just buys management more credibility while they work to align spending with recurring revenue and manage margin pressure from hardware inputs.
The most relevant piece of recent news for this quarter is management’s launch of Exensio Aurora as an AI native architecture, paired with strong customer feedback. This sits right in the middle of the current catalyst, which is broader adoption of AI driven manufacturing analytics across fabs, equipment vendors, OSATs and fabless customers. The Q3 results show that platform and equipment related revenue are already supporting record sales.
Exensio Aurora, together with secureWISE connectivity and Exensio Studio AI, gives PDF Solutions a clearer route to more subscriptions and usage based analytics. That helps build on the existing base of recurring revenue and backlog that analysts highlighted previously. The operational test from here is straightforward: Can the business keep converting those AI tools into long term contracts quickly enough to offset hardware cost pressure and the lumpiness of volume based gainshare streams?
PDF Solutions' current earnings are reported at US$10.3 million, with analysts forecasting earnings of US$64.3 million on projected revenue of US$413.6 million by 2029. This outlook is based on an assumption of revenue growth of 19.7% per year and implies an earnings increase of roughly 6x from today’s level.
Uncover why PDF Solutions' fair value indicates a 62% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts far more weight on valuation risk than on AI contract wins. While the consensus talks about US$413.6 million of revenue and US$64.3 million of earnings by 2029, the lowest analysts were working off roughly US$408.1 million and US$24.3 million instead. That gap shows how sharply opinions on PDF Solutions can differ and why it helps to explore several angles before reacting to this quarter’s news.
Explore 3 other PDF Solutions fair value estimates, including one that suggests as much as 69% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PDF Solutions research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for PDF Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PDF Solutions' overall financial health at a glance.
Looking for more investment ideas beyond PDF Solutions?
Once you have formed a view on PDF Solutions, it can help to line it up against a broader watchlist built from different styles of opportunities using the Simply Wall St Screener.
- For investors who care most about valuation support and quality fundamentals, start with a focused set of 39 high quality undervalued stocks that already screen well on both price and balance sheet strength.
- If capital preservation and a smoother ride matter more to you than chasing every rally, consider building a watchlist from 29 resilient stocks with low risk scores that are assessed to have more resilient profiles.
- Readers who prefer strong financial footing as a foundation for any thesis can scan a list of solid balance sheet and fundamentals (24 results) and use it as raw material for their next round of research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com