


SiTime has been a strong performer over the past few years. After a sharp pullback in recent weeks, the key issue for investors is whether the current share price can still be explained by what the business is generating in sales.
- The stock has returned about 286.0% over the past 3 years, which puts a lot of weight on the question of whether that move is supported by its revenue base.
- Recent news of rapidly expanding revenue and a larger combined timing business may support expectations for stronger sales over time, which directly affects how much investors are prepared to pay per dollar of turnover.
- There is a second opinion on SiTime worth weighing. See what analysts think SiTime's shares could be worth.
The issue now is whether SiTime's current valuation is justified by its sales when compared with the Fair Ratio benchmark.
If you want a reference point for SiTime's sales driven story, it helps to compare it with other companies using our screener of 39 high quality undervalued stocks.
Does SiTime Look Pricey on Sales?
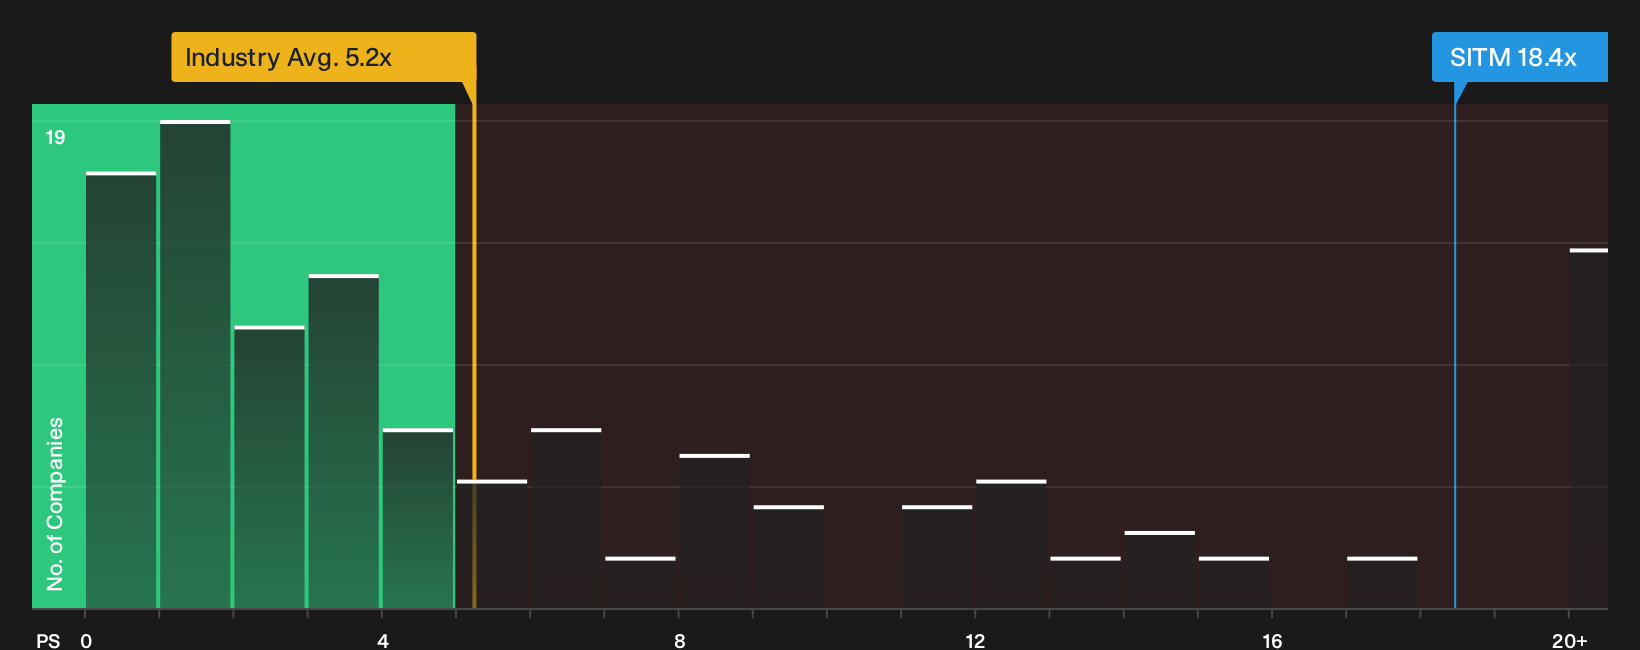
P/S fits SiTime fairly well because revenue is a clearer anchor than earnings while the business is still building out its profit base. On this lens, the stock trades on a P/S of about 18.4x, compared with a Semiconductor industry average near 5.2x and a peer group around 16.9x.
The Fair Ratio framework, which adjusts the P/S multiple for SiTime's growth profile, margins, size and risk, points to a lower figure than the current valuation, so the shares screen as overvalued on this metric. Despite the strong Q3 2026 revenue update and the larger timing portfolio, the price still asks investors to pay a premium per dollar of sales relative to both the sector and similar companies. This means you would need to be confident that the recent momentum in SiTime's business can be sustained over time for that gap to feel comfortable. Explore the numbers behind SiTime's P/S valuation.
The SiTime Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St act as a bridge between SiTime's current P/S premium and the assumptions that would need to hold on growth, profitability and earnings quality for the stock to be worth materially more or less than today's price. Each scenario ties a fair value to a particular version of SiTime's potential catalysts and key risks, so you can track over time which story the business is actually following.
One of the top community narratives on SiTime: 50% undervalued
"Acceleration in AI-driven data center and related infrastructure growth is driving strong, sustained demand for SiTime's precision timing solutions…"
Discover why this Narrative puts SiTime at 50% undervalued.
One more key piece on SiTime before you make a move
Valuation only tells part of the story. The next step is to see how professional analysts currently map out SiTime's earnings and revenue a few years from now, and how that picture lines up with today's market pricing. Explore where analysts expect SiTime to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com