


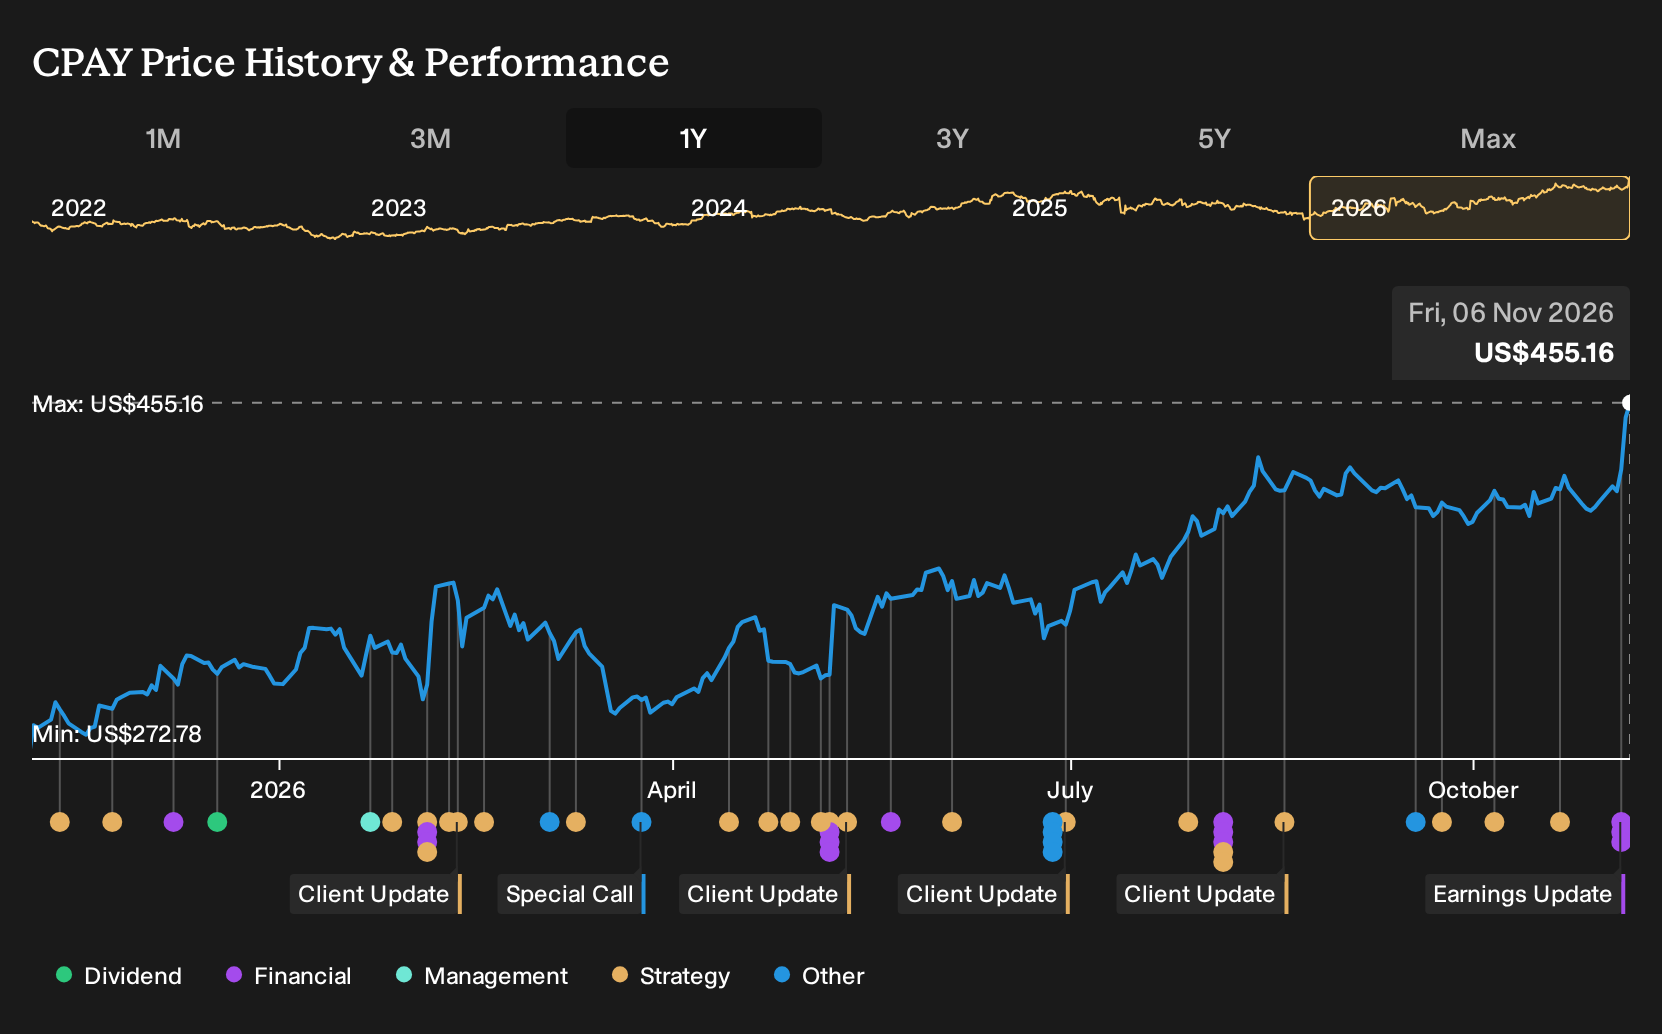
- Corpay reported third quarter 2026 sales of US$1,381.93 million and net income of US$378.42 million, with basic earnings per share from continuing operations of US$5.73, and raised full year 2026 guidance for revenue, net income and diluted EPS.
- The business sharpened its focus on Corporate Payments and cross border services, funding share repurchases with US$1.2b of non core divestitures and expanding its buyback authorization by US$1b.
- Next, the discussion will examine how Corpay's raised 2026 earnings outlook could influence the existing investment narrative around corporate payments.
Scan Corpay's latest earnings beat against a curated peer set by reviewing 39 high quality undervalued stocks that share strong fundamentals and may be positioned for the next stage of their story.
Corpay Investment Narrative Recap
To own Corpay, you need to believe the corporate payments and cross border engines can keep carrying more of the load as Vehicle Payments becomes less central. The raised 2026 guidance, alongside Q3 revenue of US$1,381.93 million and net income of US$378.42 million, reinforces that the current operating playbook is working today.
The key short term catalyst is continued double digit organic growth in Corporate Payments and cross border volumes, supported by execution on portfolio simplification. The biggest risk remains any setback in organic revenue momentum or tighter constraints around U.S. Vehicle Payments fees, which could limit margin progress even while guidance looks solid for now.
The most relevant update for this story is Corpay lifting its full year 2026 outlook. Management now guides to total revenue between US$5.34b and US$5.36b, net income between US$1.337b and US$1.357b, and diluted EPS between US$20.03 and US$20.23. That represents a tighter, higher bar for the remainder of the period covered by the guidance.
For you as a shareholder, that raised bar makes execution the main catalyst. Stronger earnings targets can support confidence in Corporate Payments expansion, cross border volumes and the benefits of divesting non core Vehicle Payments assets. At the same time, any shortfall relative to these higher numbers would quickly refocus attention on growth durability and on potential regulatory or pricing pressure in legacy fuel card operations.
Corpay's current analyst narrative points to revenues of US$6.6b and earnings of US$1.9b by 2029, based on assumed 9.4% yearly revenue growth and an earnings increase of about US$800m from US$1.1b today.
Uncover why Corpay's fair value is essentially aligned with its current price.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community range from about US$461 to more than US$633.9b, a spread that shows how far apart retail opinions on Corpay can be. You are weighing those views against catalysts such as cross border expansion and portfolio simplification, as well as risks around fuel card fees and margin pressure. Investor opinions clearly diverge, so it is worth exploring several of these viewpoints before deciding how Corpay fits into your own thesis.
Explore 2 other Corpay fair value estimates, including one that suggests it could be worth just $461.00.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Corpay research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Corpay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corpay's overall financial health at a glance.
Looking for more Corpay sized investment ideas?
If Corpay has helped clarify what you want from a business, you can use that momentum to map out a broader watchlist that fits your risk tolerance, income needs, and time horizon.
- For investors who care most about quality at a reasonable entry point, you can scan a curated universe of strong fundamentals through the 39 high quality undervalued stocks.
- If capital preservation comes first for you, you may want to focus on balance sheets that can handle stress by starting with this 29 resilient stocks with low risk scores.
- When you want to explore potential future leaders before they hit the headlines, you can broaden your search with a 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com