


Texas Roadhouse (TXRH) is back in the spotlight after its third quarter update combined solid year-over-year gains in revenue and earnings with a slight miss versus Wall Street expectations.
Texas Roadhouse shares closed at US$183.88 after the Q3 release, with the 1 day share price return down 4.12%, the 30 day share price return up 12.98% and the 1 year total shareholder return at 13.28%. This suggests that recent momentum has picked up again despite earlier volatility tied to the earnings miss and the short lived sales impact from the social media hoax.
Scan how Texas Roadhouse stacks up against other consumer names with resilient performance and cash generation by reviewing our curated list of 39 high quality undervalued stocks.The question now is simple. After Texas Roadhouse stock rallied hard on the rebound story and still trades below analyst targets and some intrinsic estimates, is most of the easy upside already gone, or is there meaningful value left?
Most Popular Narrative: 13% Undervalued
On the most followed view, Texas Roadhouse screens as undervalued, with a fair value of about $210 against the recent $183.88 close. This puts the focus on what is powering that gap. The story hanging over the stock is whether its restaurant expansion, multi brand buildout, and cash returns can keep supporting that narrative value.
The main factor that has to go right is that Texas Roadhouse continues to translate its traffic outperformance, multi brand expansion, and technology investments into stable or improving restaurant margins despite ongoing beef and wage cost pressures.
The current valuation implies the market may be underestimating the long term earnings power of Texas Roadhouse if its traffic, unit growth plans, and cash returns to shareholders persist while margin pressures ease over time.
See why 57 investors see Texas Roadhouse as 13% undervalued.
Result: Fair Value of $210.33 (UNDERVALUED)
Still, the Texas Roadhouse narrative can be knocked off course if beef and wage inflation keep squeezing restaurant margins, or if new units underperform after heavy capital spending.
Find out about the key risks to this Texas Roadhouse narrative.
Another View: What Texas Roadhouse’s P/E Is Telling You
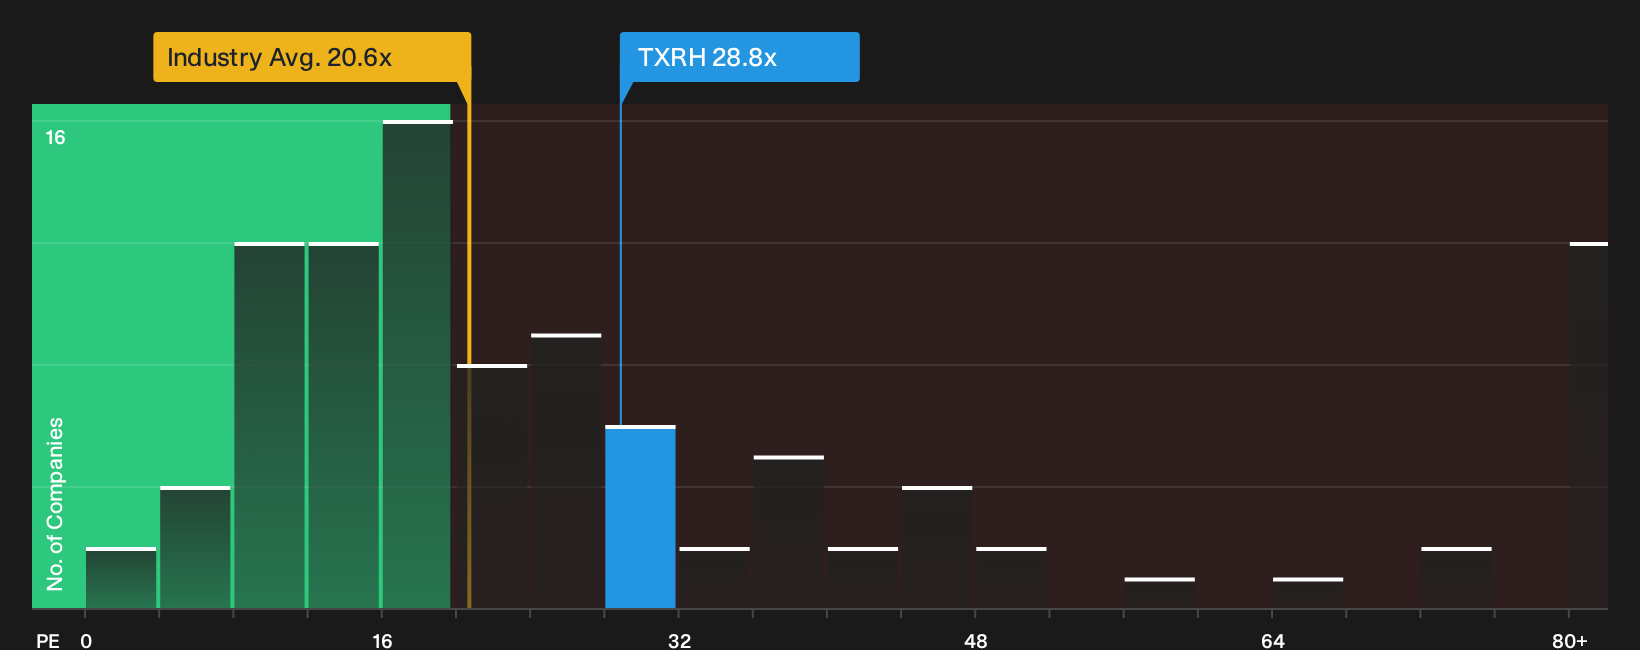
There is a different read on Texas Roadhouse once the focus shifts to its current P/E of 28.8x. That level is well above both the US Hospitality group on 20.6x and the stock’s own fair ratio of 23.4x, which points to valuation risk if sentiment cools or growth expectations reset.
Investors weighing that premium against the earlier fair value story may want to see what the numbers imply for this price in more detail through our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Texas Roadhouse so far, right. If you want to move faster than the crowd and build your own view from the numbers, start by weighing its 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Texas Roadhouse?
Do not stop with a single stock. Use the Simply Wall Street Screener to compare opportunities efficiently, pressure test your thesis, and spot better risk reward trade offs.
- Target potential turnaround plays by scanning the 9 elite penny stocks with strong financials that pair low share prices with stronger balance sheet and earnings profiles than you might expect.
- Zero in on quality at a discount by reviewing a curated 39 high quality undervalued stocks that combine healthy fundamentals with valuations that look more forgiving.
- Prioritise resilience and sleep better at night by focusing on a 29 resilient stocks with low risk scores where financial strength and lower risk scores do more of the heavy lifting.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com