


Blackbaud has climbed in the past month yet it is still working through a share price record that shows sizable declines over 1 and 5 years, which puts fresh focus on whether the current valuation can be squared with its earnings power. With the stock closing at US$54.12, the key issue for you is how that price lines up against what the business actually earns today and what it may reasonably earn in the future.
- Over the past 5 years the share price has declined 35.0%, which makes the current P/E and earnings outlook especially important for anyone reassessing the stock.
- Recent news around Blackbaud's AI-focused Platform for Good and the planned Lantern fundraising intelligence model may support expectations for future earnings growth and margin resilience, which in turn feeds directly into how investors think about paying for its current profit stream.
- Your read on Blackbaud is one view; the desks covering it have another. See what analysts think Blackbaud's shares could be worth.
The stock's next move may depend on whether Blackbaud's current earnings are strong and durable enough to justify today's price tag.
If you want to stress test how Blackbaud's AI story and earnings-based valuation compare with other potential ideas, scan through 41 profitable AI stocks that aren't just burning cash.
Is Blackbaud Still Cheap on Earnings?
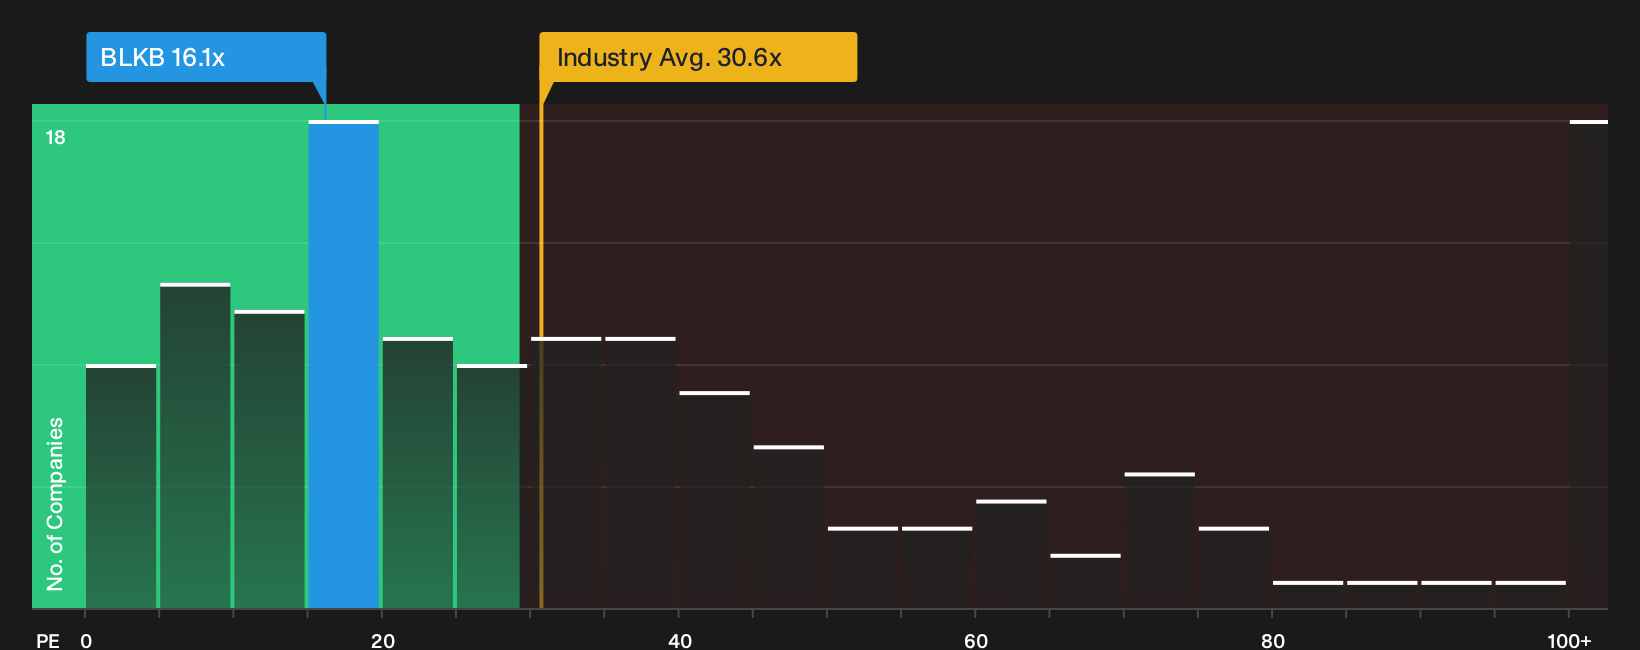
The P/E ratio is a useful lens for Blackbaud because it already reports positive earnings and is compared most often against other software groups on this basis. At around 16.1x earnings, Blackbaud trades at a sizable discount to the wider Software industry, where the average trades near 30.6x, and also below a peer group closer to 40.4x. Because this gap is measured on profits rather than revenue or assets, it indicates that the market is paying far less for each dollar of Blackbaud's earnings than for many software rivals.
The fair P/E that would typically be expected for Blackbaud, once factors like its business quality, risk profile and sector context are blended together, sits above the current 16.1x level. This suggests that the shares screen as undervalued on this measure. Because the newly announced Platform for Good and Lantern AI products relate directly to how the business monetises its software, the current discount persists despite a clear narrative around future AI tools and fundraising intelligence. That gap between the present multiple and what the models suggest as a more typical level is what investors will want to probe further with deeper research. Explore the numbers behind Blackbaud's P/E valuation.
The Blackbaud Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Blackbaud pick up where the P/E debate leaves off and explain what kind of future growth, margins and earnings profile would need to occur for the stock to appear meaningfully cheaper or more expensive than today's share price, using the Community page as the hub. Each scenario links a specific numerical view to a clear stance on how Blackbaud's expansion, profitability and risk mix could develop, which you can revisit as new information becomes available.
Community views on Blackbaud split between those who see more upside in the AI and payments build out and those who worry renewal risks already justify caution.
Bull case: roughly fairly valued
"Ongoing investment in generative and agentic AI, now reflected in broad use of machine learning prospecting in Raiser's Edge NXT and the rollout of high ticket Agents for Good products such as the Fundraising Development Agent and the K-12 Admissions Agent, can add new subscription revenue layers and support higher gross margins..."
Discover why this Narrative puts Blackbaud at roughly fairly valued.
Bear case: 20% overvalued
"Although Blackbaud is starting to commercialize its AI first roadmap with Agents for Good, Platform for Good and Lantern, the larger 2026 contractual recurring revenue renewal cohort that is moderating gross dollar retention through the first half of 2027 could blunt early AI upsell..."
Explore why this Narrative puts Blackbaud at 20% overvalued.
Before acting on Blackbaud's valuation, one more piece of the puzzle matters
Numbers tell only part of the story, because the people directing Blackbaud and the way their rewards line up with your interests can tilt the risk and return profile in ways this valuation work does not cover. See who runs Blackbaud and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com