


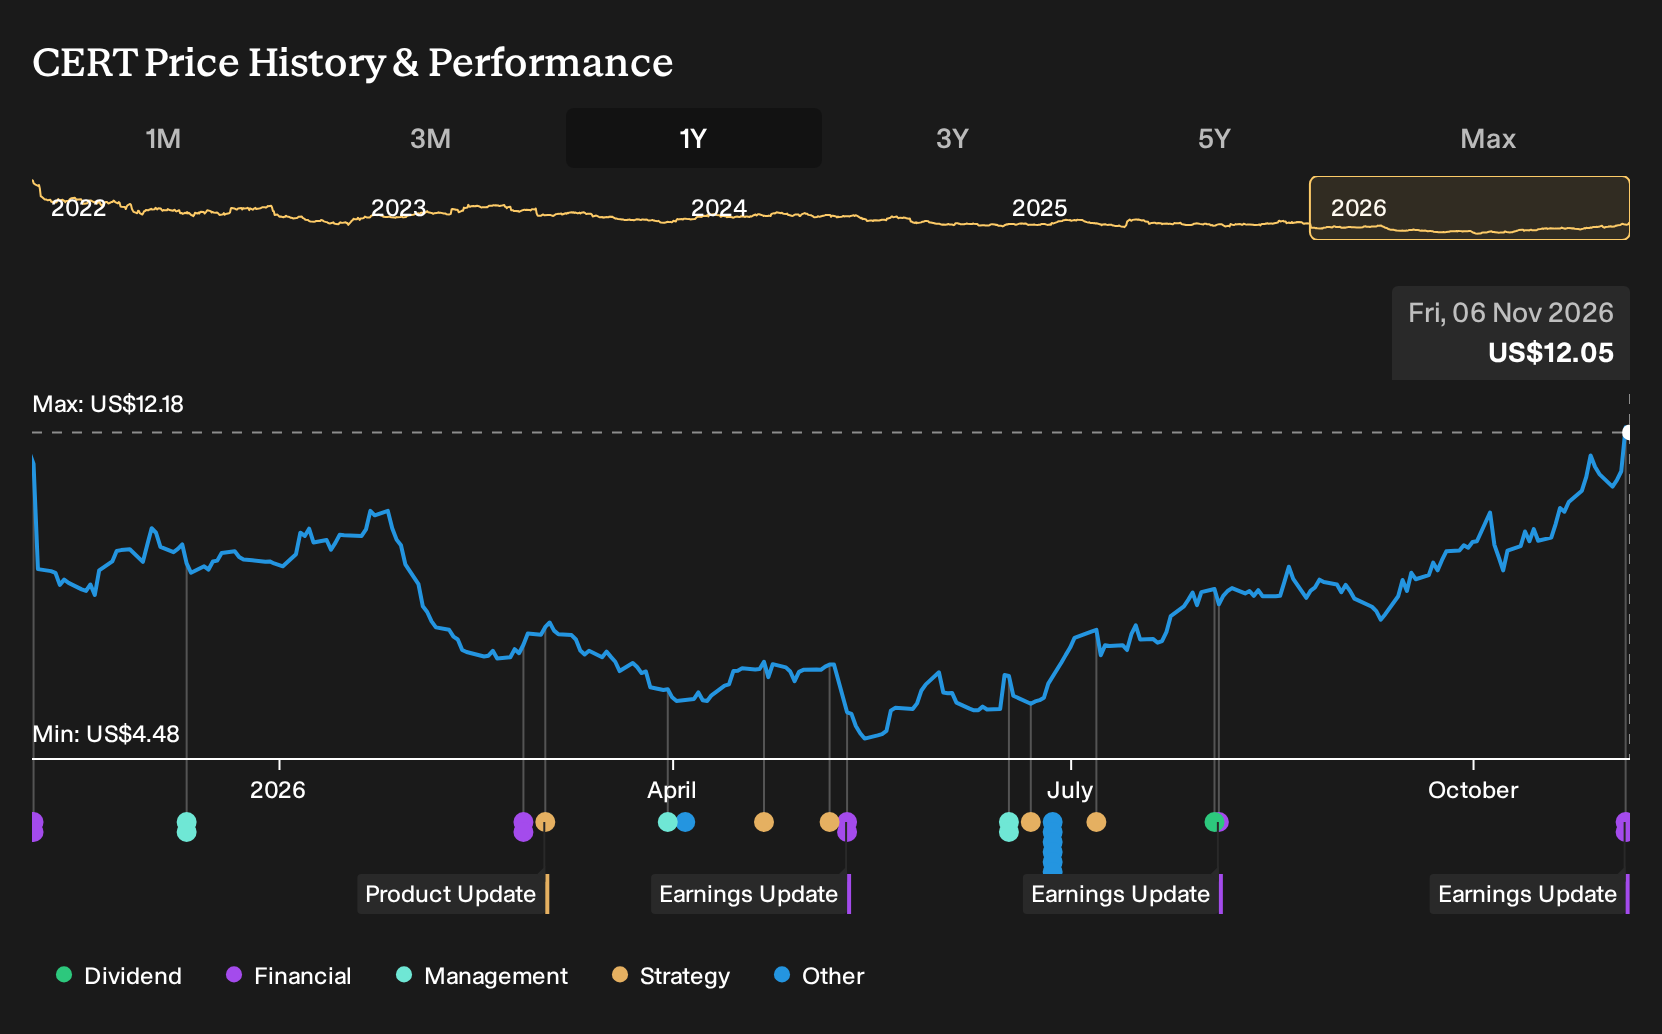
- Certara reported Q3 2026 revenue of US$94.9 million and net income of US$5.59 million, with software sales growing 11% year over year and an adjusted EBITDA margin of 31.8%.
- The company paired its first double-digit organic software revenue increase in two years with tighter 2026 guidance that emphasizes higher margin software and ongoing AI integration.
- We will now look at how Certara's investment narrative could be influenced by stronger software growth and tighter full year guidance.
Compare Certara's renewed software momentum with other potential breakouts in healthcare and AI by scanning our hand-picked list of 35 healthcare AI stocks.
Certara Investment Narrative Recap
To own Certara, you need to believe its biosimulation and AI infused software can keep gaining traction with pharma customers while the services side remains a healthy funnel for new software users. The Q3 print helps that story in the near term, with 11% software growth and a 31.8% adjusted EBITDA margin, which points to better mix and expense discipline.
The short term swing factor is whether this software strength holds up while overall 2026 revenue growth is guided to only 2% to 3%. The biggest risk remains that pharma budgets, slower adoption of new tools, or weaker returns on Certara's R&D and acquisitions keep group revenue and earnings under pressure.
The guidance update narrowing 2026 revenue growth to 2% to 3% is the key follow on to these results. Management is effectively telling investors to focus less on headline growth this year and more on where that growth comes from, particularly higher margin software tied to AI and cloud offerings.
For catalysts, the question is whether this tighter range creates a cleaner setup for future launches such as the AI enabled MIDD and QSP platforms and for deeper use of Simcyp and Phoenix across customers. If pharma caution or slow regulatory acceptance persists, that same guidance range could highlight execution risk instead of operating progress.
Certara's narrative projects US$421.9 million revenue and US$15.8 million earnings by 2029. This implies fairly flat yearly revenue trends and requires a US$38.3 million earnings improvement from a loss of US$22.5 million today.
Uncover why Certara's fair value indicates a 28% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
For a contrasting take on Certara, focus on the risk that weaker services demand keeps dragging on results, even if software keeps improving. The most cautious analysts were penciling in revenue of about US$405.6 million and earnings of US$37.3 million by 2029, yet still saw only a US$7.0 fair value. That gap shows how widely views can differ. Treat this Q3 update as fresh data and explore how both the consensus and bearish stories might now evolve.
Explore 2 other Certara fair value estimates, including one that suggests as much as 42% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Certara research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Certara. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Certara's overall financial health at a glance.
Looking For More Ideas Beyond Certara?
If Certara has you thinking about where else disciplined growth, resilient balance sheets, or income strength might show up, the Simply Wall St Screener can quickly surface a wider watchlist tailored to what matters most to you.
- If capital preservation and steadier risk matter most to you, start with a basket of companies filtered for resilience through the 29 resilient stocks with low risk scores.
- For investors who care about durable cash flows and clean finances, broaden your watchlist with a list of solid balance sheet and fundamentals (24 results).
- If you are hunting for lesser known opportunities with solid fundamentals, widen your opportunity set with a 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com