


- Almonty Industries is drawing fresh scrutiny as its earnings are measured against a premium valuation, with investors weighing how current tungsten operations support that pricing.
- The debate centres on how much value to place on Almonty Industries' long term tungsten contracts, sizable cash balance and role in non Chinese supply.
- We will now see how Almonty Industries' investment narrative is shaped by this premium valuation built on long term tungsten contracts.
Scan beyond Almonty Industries and line up other premium rated miners with strong fundamentals using our curated list of 33 best rare earth metal stocks
Almonty Industries Investment Narrative Recap
To own Almonty Industries at today’s P/E near 30x, investors need to believe its tungsten operations can move from reliance on a single core asset in Portugal toward a broader, more reliable production base. In the near term, the key factor is the Sangdong ramp in South Korea and how quickly operations can move from roughly 16-hour days toward design capacity without major setbacks.
The biggest current risk is execution slippage across Sangdong, Los Santos tailings and Rwanda feed, since delays or technical issues would strain the earnings now implied by the premium valuation. The recent share price surge does not directly change those operational tasks, although it raises the bar for what the business needs to deliver.
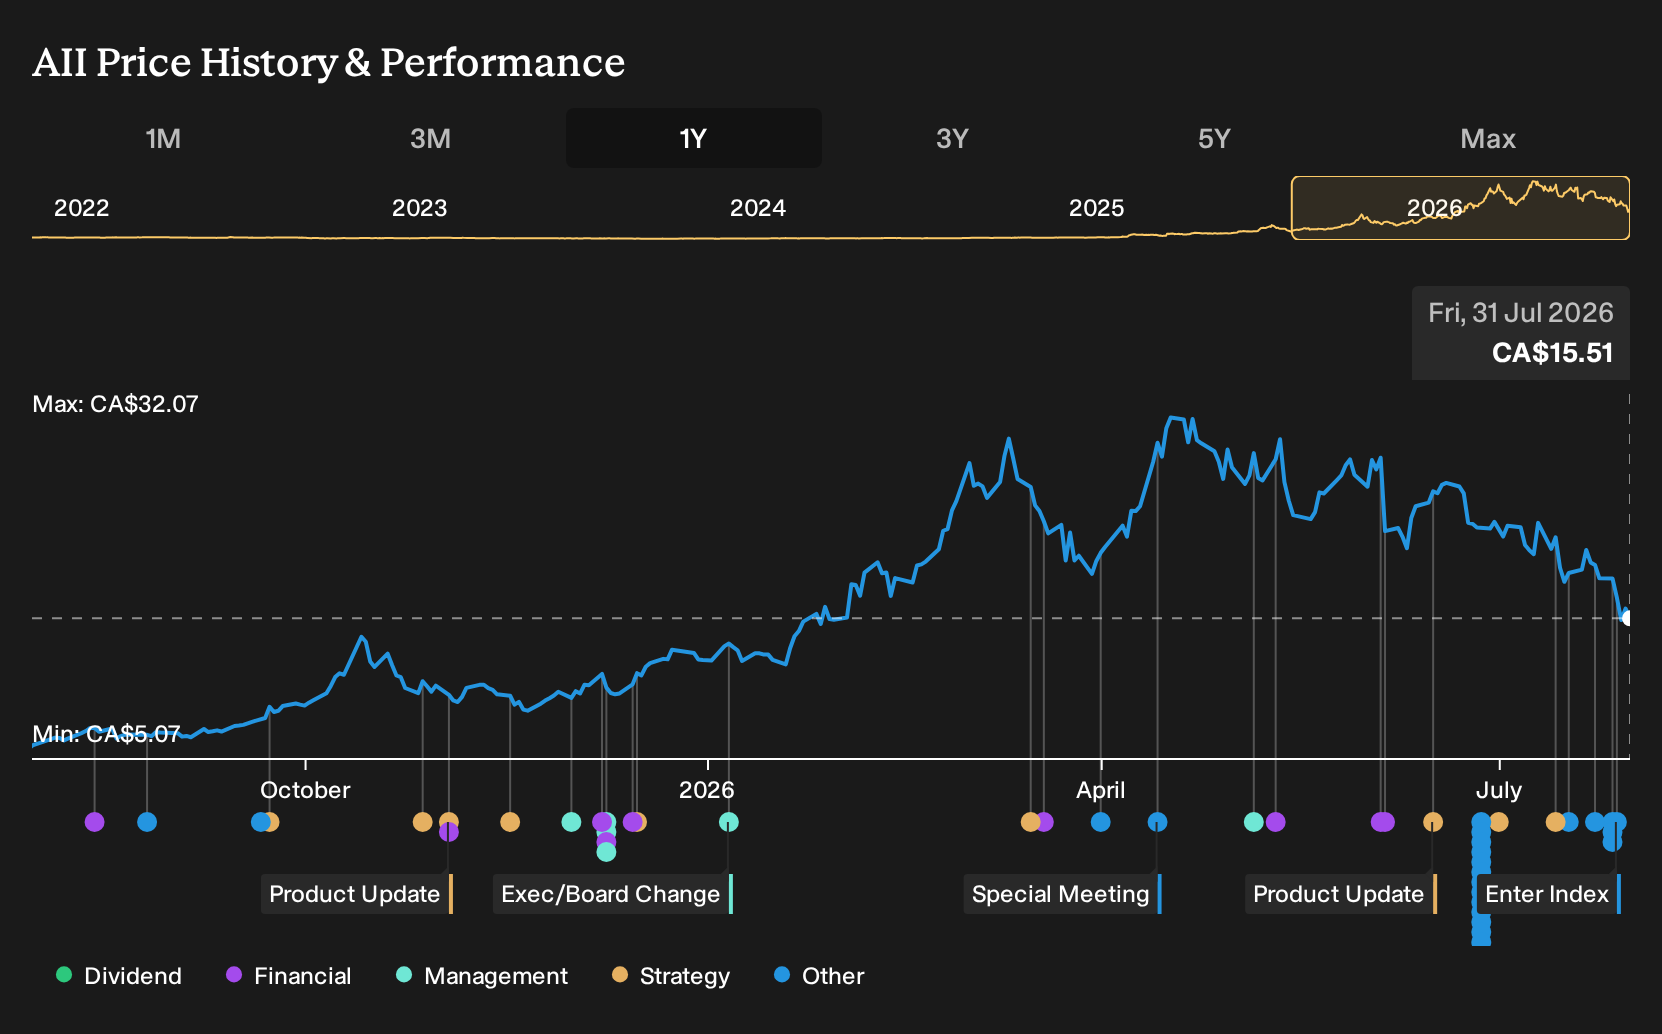
The most relevant backdrop to the latest share price move is the earlier extension of Almonty Industries’ long-term offtake with Global Tungsten & Powders. That contract added six years, increased contracted volume by 40% and shifted pricing to the middle of the market, which helps explain why investors are focusing so much on the firm’s non-Chinese supply position.
Those terms, together with take-or-pay arrangements at Los Santos and early exports from Rwanda, shape the key catalysts investors are watching. As Sangdong ramps and the planned tungsten oxide plant in Korea progresses, the central question is how effectively management converts this contracted book and project pipeline into consistent throughput, cash generation and support for the current earnings multiple.
Almonty Industries' current analyst playbook assumes a very large 171.4% yearly increase in revenue and earnings rising from CA$107.5 million today to CA$983.1 million by 2029, which implies an earnings uplift of about CA$875.6 million and ties into a forecast that revenues reach CA$1.7b in the same year.
Uncover why Almonty Industries' fair value indicates a 190% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You can interpret the recent share price surge in two very different ways. Consensus points to Sangdong’s ramp as the key driver, yet the most cautious Almonty Industries analysts focus more on Montana’s high costs and slow permitting. Those lower forecasts, with earnings closer to CA$618.1 million on about CA$1.0b revenue by 2029, highlight how wide the opinion range was before this news and suggest that expectations may shift again as fresh information emerges.
Explore 4 other Almonty Industries fair value estimates, including one that suggests it could be worth just $13.34!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Almonty Industries research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Almonty Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Almonty Industries' overall financial health at a glance.
Looking for more investment ideas beyond Almonty Industries?
If the Almonty Industries story has sharpened your thinking about risk, valuation and balance sheet strength, it can be useful to compare it with other opportunities that share similar qualities.
- If you want companies that look inexpensive relative to their fundamentals, scan through a 39 high quality undervalued stocks and see which ones line up with your own quality checklist.
- If income is a priority for you, focus on resilient payers by reviewing a 8 dividend fortresses that aims to pair higher yields with sturdier profiles.
- If capital preservation matters just as much as upside, filter for stability first by working through a 29 resilient stocks with low risk scores that keeps weaker balance sheets and fragile business models off your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com