


Headlines around Nvidia and alleged espionage links are forcing investors to rethink where chip demand meets export rules and political scrutiny. When trust and compliance suddenly sit in the spotlight, attention often moves to businesses that already talk openly about secure handling and authorized distribution. This article explains how that theme connects to Nvidia and then profiles 3 stocks exposed to the same news shock, all pulled from a targeted compliance screener.
The three stocks below are a small sample, while the full screen surfaced 48 more semiconductor distributors, foundries, and OSATs with equally compliance focused narratives that are not covered here. To go straight to the full list and identify your own highest conviction ideas, analyze and filter directly through the Semiconductor Supply-Chain Compliance & Authorized Distributors screener.
Powerchip Semiconductor Manufacturing (TWSE:6770)
Powerchip Semiconductor Manufacturing runs foundry style chip manufacturing, testing and packaging that directly aligns with the screener focus on secure, export aware supply chains. The business generated about NT$55.2b from semiconductors and has a market value near NT$249.3b, giving it scale in compliance sensitive production.
Powerchip Semiconductor Manufacturing sits in the middle of cross border chip production, handling wafers and packaging for clients across Taiwan, the U.S. and China in a way that keeps export control questions prominent. Recent profitability and size give it resources to invest in tighter processes, yet regulatory pressure could still reshape pricing dynamics or order flow.
That kind of pressure makes detail matter, so review the 4 key rewards and 2 important warning signs to see how Powerchip Semiconductor Manufacturing’s scale could amplify both upside and compliance shocks.

ChipMOS TECHNOLOGIES (TWSE:8150)
ChipMOS TECHNOLOGIES is an OSAT specialist whose assembly and testing work for advanced chips makes secure handling and export aware processes central to its role in the semiconductor supply chain.
ChipMOS TECHNOLOGIES runs testing, assembly, bumping, and display driver services that generated about NT$8.5b from assembly, NT$6.7b from testing, NT$6.2b from bumping, and NT$5.6b from display drivers, with a market value near NT$49.1b.
ChipMOS TECHNOLOGIES matters here because its packaging and test lines touch the same kind of high value chips now drawing scrutiny. At the same time, its story hinges more on how it turns that handling expertise into steady, higher margin work.
"Solid momentum and volume growth in memory products, particularly DRAM and Flash tied to data center and AI-related demand, is now reflected in memory reaching 51% of Q2 2026 revenue and higher utilization. This supports the view that ChipMOS TECHNOLOGIES can keep lifting revenue and operating margins if this demand environment persists."
What happens to ChipMOS TECHNOLOGIES' margins and cash generation depends heavily on how one large, capital hungry project cycle actually plays out.
That uncertainty around one big buildout is exactly what the full narrative for ChipMOS TECHNOLOGIES unpacks, highlighting where accelerating demand could decouple from capital strain.

Sigurd Microelectronics (TWSE:6257)
Sigurd Microelectronics runs IC packaging, testing, and burn in services that fit a supply chain screen focused on secure, export aware handling. The Packaging and Testing segment brings in about NT$21.2b compared with roughly NT$56 million from Trading, and the company is valued near NT$76.3b.
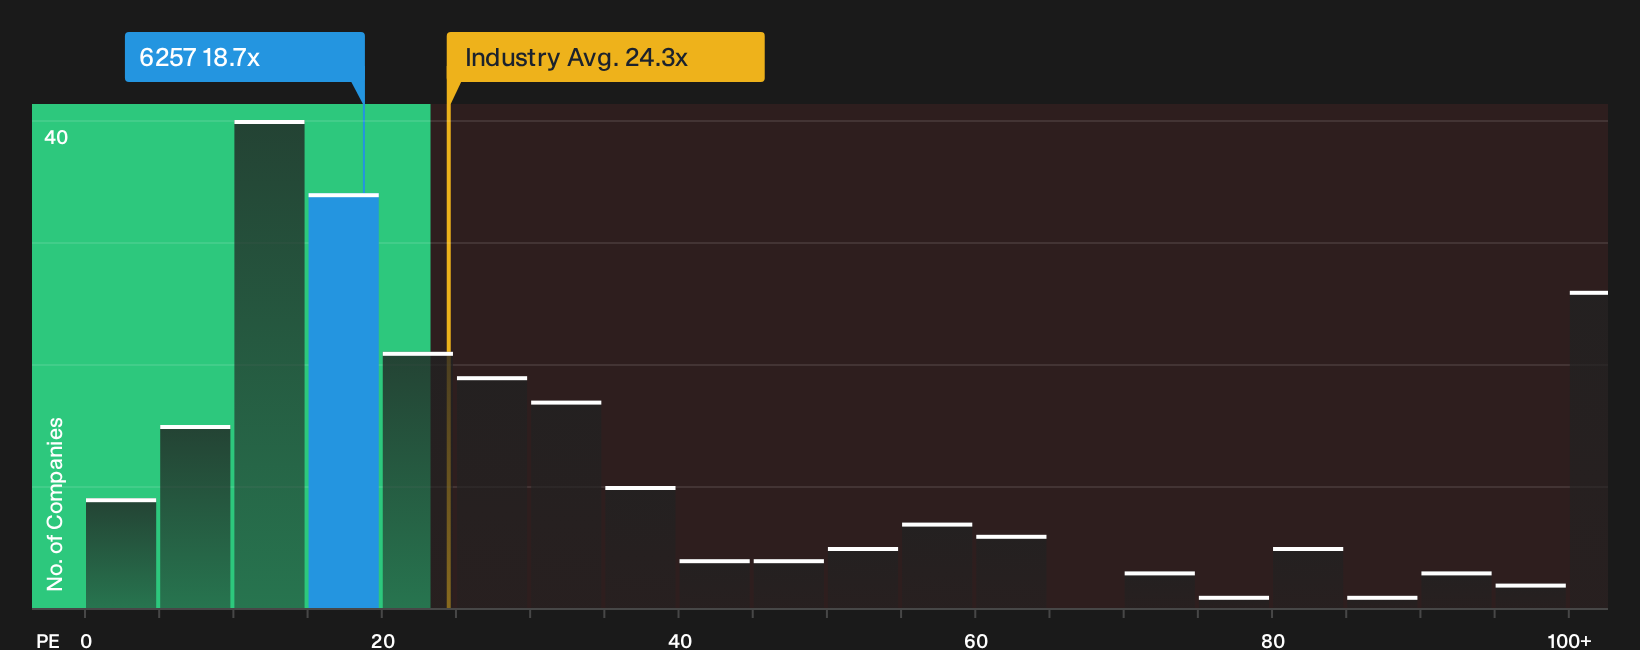
Sigurd Microelectronics gives chip designers, foundries, and device makers a global testing and burn in partner that emphasizes tracking and export control for sensitive devices. That is exactly what this screener is trying to surface. Investors get a compliance focused OSAT at an 18.7x P/E, yet everything depends on how one unseen pressure shapes future cash backed returns.
That hidden pressure is exactly where the 4 key rewards and 3 important warning signs (1 is major!) helps you see whether Sigurd Microelectronics' current P/E is masking vulnerability or an underappreciated opportunity.
Seeking Alternatives Before Everyone Else
Fresh ideas tend to move first, and late money usually chases what is already flying. Scan these under the radar lists while it matters and before momentum gets fully caught. Consider acting while conditions still look attractive.
- Spot potential breakouts early by scanning a curated pool of 224 high quality undervalued stocks that combine financial quality with prices that still appear beaten down and overlooked.
- Explore durable income streams through a hand built group of 232 dividend fortresses designed to prioritize balance sheet strength alongside notable cash distributions.
- Follow the AI infrastructure buildout using a focused universe of 52 AI infrastructure stocks where hardware, energy, and data-center enablers provide the picks and shovels behind the trend.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com