


- Alphatec Holdings reported third quarter 2026 results with net loss narrowing to US$5.47 million and basic loss per share from continuing operations improving to US$0.03, while nine month loss declined to US$65.16 million and loss per share to US$0.42 compared with the prior year.
- Management also raised full year 2026 guidance, now expecting about US$862 million in total revenue, split between roughly US$789 million of surgical revenue and US$73 million of EOS revenue, which puts the spotlight on how effectively Alphatec Holdings is converting its spine ecosystem into higher quality scale.
- The focus will now be on how Alphatec Holdings' investment narrative aligns with this tighter loss profile and higher revenue outlook.
Scan how Alphatec Holdings' tighter losses and higher 2026 revenue outlook compare with other potential spine and medtech breakouts by running the 19 high quality undiscovered gems.
Alphatec Holdings Investment Narrative Recap
To own Alphatec Holdings, you need to believe the spine ecosystem can keep winning share with surgeons and convert higher procedure volume into a path toward consistent profitability. The narrowed quarterly loss points to better expense control. The raised 2026 outlook leans on that thesis but does not remove execution risk around salesforce productivity and capital needs.
The key short term swing factor remains how quickly Alphatec Holdings can push higher quality surgical volume across its direct commercial footprint. The biggest risk stays the same. Heavy R&D and instrument spend on robotics and informatics could strain cash if revenue growth slows or if competitive pressure from larger medtech peers intensifies.
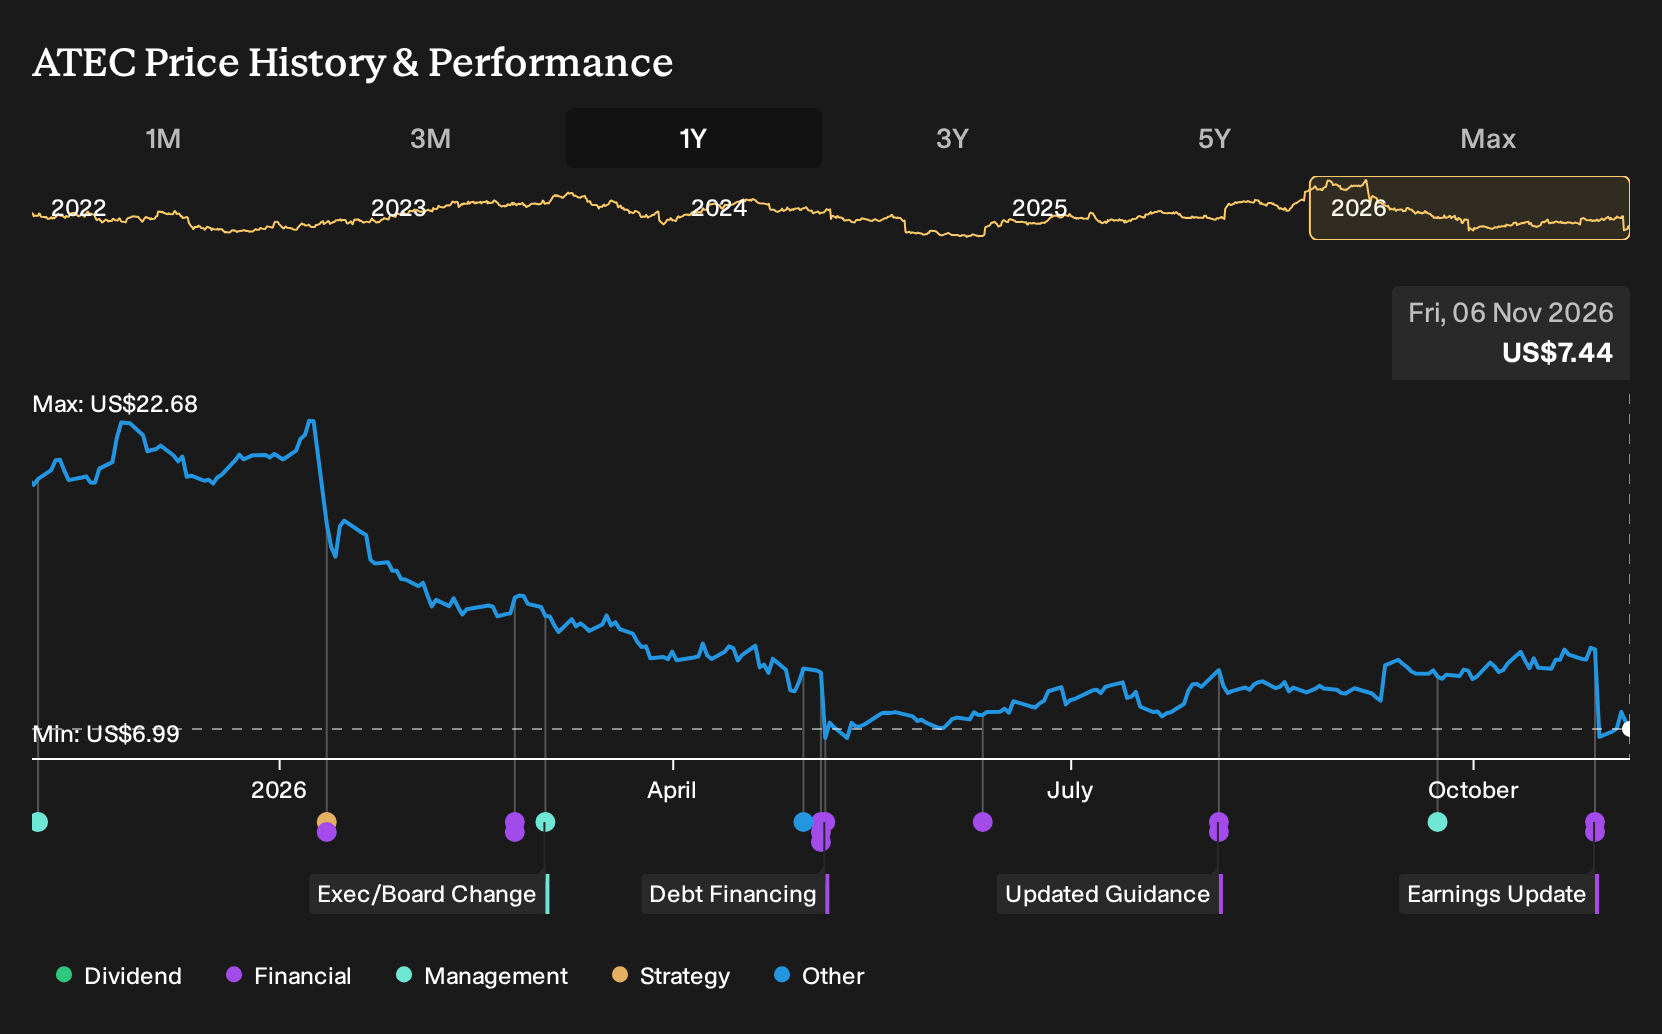
The revised 2026 guidance is the announcement that matters most here. Management now expects about US$862 million in full year revenue, with roughly US$789 million from surgical procedures and US$73 million from EOS imaging. That mix shows where the commercial engine is currently strongest and where the ecosystem data story is building.
For you as an investor, the question is whether Alphatec Holdings can keep tightening losses while ramping products like Valence, EOS and SafeOp without stretching the balance sheet. Execution on surgeon adoption, instrument placements and field efficiency sits on one side. On the other side, there is ongoing competition, regulatory cost, and an unprofitable starting point that still needs to turn into durable earnings.
Alphatec Holdings' narrative projects US$1.2b revenue and US$199.8 million earnings by 2029. This implies 13.2% yearly revenue growth and an earnings increase of about US$286.7 million from earnings today, compared with a current loss of US$86.9 million.
Uncover why Alphatec Holdings' fair value indicates a 92% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle on Alphatec Holdings is the bullish focus on EBITDA and free cash flow potential. Before this guidance, the most optimistic analysts were talking about around US$882 million of 2026 revenue and US$140 million of adjusted EBITDA. You can see how far that view sits from consensus and decide which assumptions feel realistic, especially now that fresh numbers are on the table and could shift those forecasts.
Explore 3 other Alphatec Holdings fair value estimates, including one that suggests as much as 156% potential increase from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alphatec Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alphatec Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alphatec Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Alphatec Holdings?
After sizing up Alphatec Holdings, it can help to zoom out and compare opportunities across a wider field of stocks that match the kind of balance between risk, quality and potential return you are aiming for.
- If you want to focus on quality first and valuation second, scan for companies that combine strong fundamentals with attractive pricing through the 39 high quality undervalued stocks.
- For income oriented portfolios that prize consistency, filter for high yield payers with resilient payout profiles using the 8 dividend fortresses.
- When capital preservation is your priority, narrow your universe to companies with steadier risk profiles by running the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com