


Uber Technologies (UBER) just signed a high profile deal with Amazon that integrates Uber Eats directly into Amazon’s website and app, giving Prime members free delivery on qualifying restaurant orders.
Investors have been weighing this Amazon tie-up alongside a mixed run for Uber Technologies, with the share price slipping about 17% year to date, but delivering a 5.1% gain over the past week and a 32.98% three year total shareholder return that points to longer term momentum.
Scan how other delivery and mobility players are priced and positioned next to Uber Technologies by checking the hand picked 39 high quality undervalued stocks, which combine quality fundamentals with potential mispricing.
So is this Amazon partnership and the recent share rebound telling you something about Uber Technologies’ underlying business progress, or just exposing how quickly sentiment can swing on a headline as investors reassess valuation next?
Most Popular Narrative: 41% Undervalued
Uber Technologies closed at $68.59, while the most followed narrative on the stock pegs fair value at $116. That is a wide gap, and the argument behind it leans heavily on how much cash the platform is already throwing off and what happens if autonomous vehicles reshape who earns that cash.
The market is no longer debating whether Uber can become profitable. It is debating who owns the economics of transportation when the driver disappears.
That distinction matters because Uber is generating more cash than at any point in its history just as investors are becoming increasingly nervous that autonomous vehicles could disrupt the marketplace responsible for producing that cash.
See why 54 investors see Uber Technologies as 41% undervalued.
According to Ivoed, the narrative behind that $116 fair value uses an 8.38% discount rate and assumes Uber Technologies can keep converting its global Mobility, Delivery and Freight footprint into sizeable free cash flow while managing the risk that autonomous partners capture a bigger share of the economics. The key tension is simple. Either Uber ends up as the must use distribution layer for robotaxis and delivery fleets, or it pays heavily to stay relevant while hardware and software suppliers keep more of the profit pool.
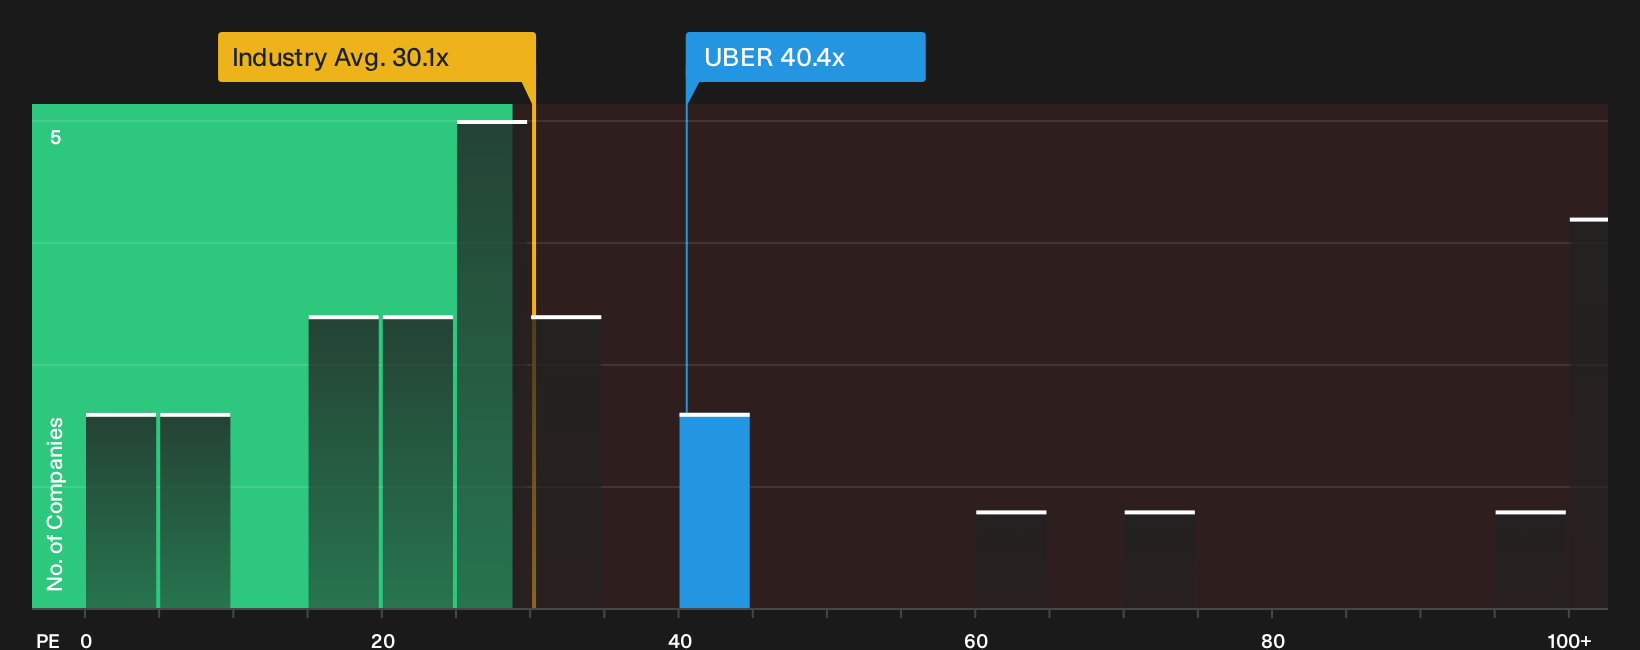
The same storyline flags that revenue growth around the low teens and forecast earnings growth of 29.63% a year are being run through a discounted cash flow lens rather than a P/E shortcut. This helps explain why the narrative can still see value even though the current P/E of 40.4x screens as expensive versus both the US Transportation average and an estimated fair P/E of 34.5x in the separate statements data. For readers, the takeaway is that this popular thesis leans more on cash generation, network effects and AV bargaining power than on today’s headline multiples.
Result: Fair Value of $116 (UNDERVALUED)
Still, the narrative can crack quickly if autonomous partners keep more of the economics than Uber Technologies, or if rising AV investment erodes free cash flow.
Find out about the key risks to this Uber Technologies narrative.
Another View: Uber Technologies On Simple Earnings Math
While the popular Uber Technologies narrative focuses on cash flows and autonomous optionality, plain P/E arithmetic sends a cooler signal. The stock trades at 40.4x earnings, which is richer than the US Transportation group at 30.1x and above a 34.5x fair ratio the market could move toward over time.
If the share price drifts toward that lower multiple instead, valuation risk sits with holders rather than onlookers waiting for a better entry point. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With all this mixed sentiment around Uber Technologies, the most useful move now is to move quickly through the underlying data yourself and stress test both sides of the story. Weigh the 2 key rewards and 2 important warning signs against your own expectations before deciding where you stand.
Looking for more investment ideas beyond Uber Technologies?
If Uber Technologies has you thinking harder about valuation and risk, use this momentum to broaden your watchlist with a few focused screeners.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (24 results) that can help you sidestep fragile stories before they crack.
- Hunt for mispriced quality by running through a 39 high quality undervalued stocks that highlights businesses where fundamentals and market expectations are out of sync.
- Stack potential income and stability by reviewing a 8 dividend fortresses that filters for higher yield payouts with added scrutiny on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com