


- Camtek reported third quarter 2026 results with sales of US$161.29 million and net income of US$42.84 million, compared with a loss a year earlier.
- The business continues to lean heavily into AI and high performance computing packaging, with inspection and metrology demand driving substantial orders and revenue visibility.
- We will now see how Camtek's stronger profitability, supported by AI focused inspection demand, could influence its broader investment narrative.
Scan beyond Camtek and see how other AI focused hardware suppliers are positioned by reviewing our curated list of 52 AI infrastructure stocks.
Camtek Investment Narrative Recap
To own Camtek, you need to be comfortable with a business that is tightly linked to AI focused advanced packaging and HBM inspection demand. The recent quarter, with US$161.29 million in sales and US$42.84 million in net income, supports the idea that this exposure is currently translating into strong profitability. The near term upside story depends on continued execution against that AI heavy order book and effective use of existing capacity.
The key near term risk is that this concentration cuts both ways. A slowdown in AI or HBM spending, or customers shifting technology roadmaps, could affect backlog conversion and the margin targets that investors are watching. Pricing pressure or higher production costs, especially as German capacity ramps, would also matter more now that expectations for earnings quality and growth are higher.
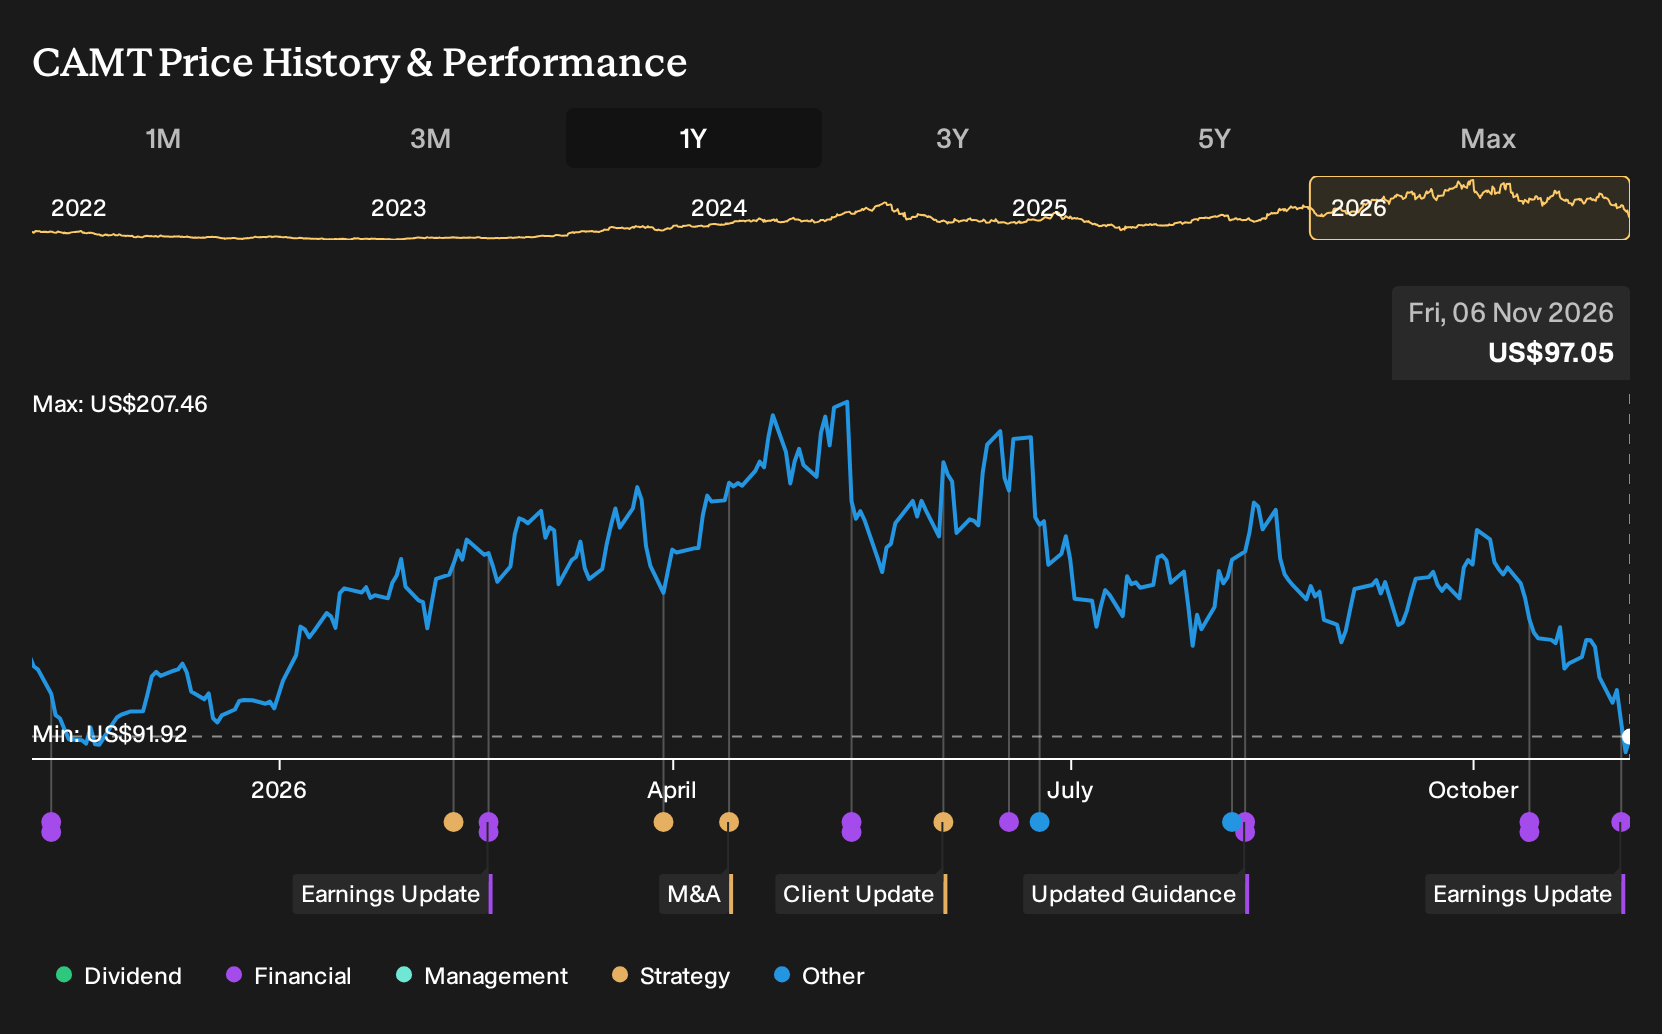
The most relevant fresh data point for this thesis is the third quarter 2026 earnings report. Sales for the period reached US$161.29 million compared with US$125.99 million a year earlier, and Camtek moved from a net loss of US$53.18 million to net income of US$42.84 million. Basic earnings per share from continuing operations were US$0.92, with diluted EPS at US$0.84.
For the first nine months of 2026, sales were US$416.2 million and net income was US$97.79 million, both higher than the prior year, which helps frame the current AI driven order momentum. Investors focused on catalysts can use these figures to assess how the firm is converting its advanced packaging and HBM exposure into consistent profitability, while keeping an eye on the earlier one off loss and the risk that concentrated end market demand could still swing results in future periods.
Camtek's current analyst narrative points to US$1.0b in revenue and US$706.2 million in earnings by 2029, based on assumed yearly top line growth of 26.2% and a move in earnings from US$37.7 million today to the 2029 consensus. This implies a very large increase in profit versus the current base.
Uncover why Camtek's fair value indicates a 75% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Camtek leans heavily on the AI software angle. The most optimistic analysts were already modeling US$1.1b in revenue and US$753.4 million in earnings by 2029 before this latest earnings report, on the assumption that Visual Layer’s AI stack shifts more value into software. You can treat today’s results as a fresh data point and explore how these upbeat forecasts might be revised from here.
Explore 4 other Camtek fair value estimates, including one that suggests there could be as much as 106% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Camtek research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Camtek. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Camtek's overall financial health at a glance.
Looking for more Camtek style investment ideas?
Once you have a view on Camtek, it can help to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you scan for stocks based on the traits that matter most to you, from value to balance sheet strength to potential under the radar stories.
- If you want potential value combined with quality fundamentals, start with a curated set of 39 high quality undervalued stocks that may offer a more attractive entry point than headline stocks.
- For investors who care most about resilience and financial stability, focus on companies with strong cash positions and modest leverage by working through the list of solid balance sheet and fundamentals (24 results) that match those criteria.
- To broaden your watchlist with lesser known opportunities, scan through a 19 high quality undiscovered gems that could complement more widely followed holdings like Camtek.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com