


Fresh third quarter results put Primo Brands (PRMB) in focus for investors, as the water focused beverage company coupled higher sales and profit with updated 2026 guidance and new capital return initiatives.
At a share price of US$22.39, Primo Brands has seen a 17.8% 1 month share price return and a 38.3% year to date share price gain. The 1 year total shareholder return of 58.4% points to momentum that has accelerated around the earnings beat, refreshed 2026 guidance, dividend affirmation and the new US$300m repurchase plan.
Scan how Primo Brands compares with other water focused and resilient consumer stocks moving on earnings and buyback news in our curated list of list of solid balance sheet and fundamentals (24 results)
After a sharp move on strong earnings, richer guidance and a fresh buyback, Primo Brands now poses a simple question for new investors: Does the current price still leave enough upside to justify the risk?
Most Popular Narrative: 24% Undervalued
Primo Brands is pegged with a fair value of $29.36 in the most widely followed narrative, compared with the latest close at $22.39. This frames the current debate squarely around how much investors trust that long term earnings path.
Ongoing integration synergies from route optimization, facility consolidation and headcount efficiency, with a stated goal of reaching $300 million run rate savings by 2026, may help structurally lift EBITDA margins and support double digit earnings growth.
See why 4 investors see Primo Brands as 24% undervalued.
Result: Fair Value of $29.36 (UNDERVALUED)
Still, the bullish Primo Brands story can unravel if direct delivery volumes remain weak for an extended period or if integration and cost savings fall short of expectations.
Find out about the key risks to this Primo Brands narrative.
Another View: Primo Brands Through The Earnings Multiple Lens
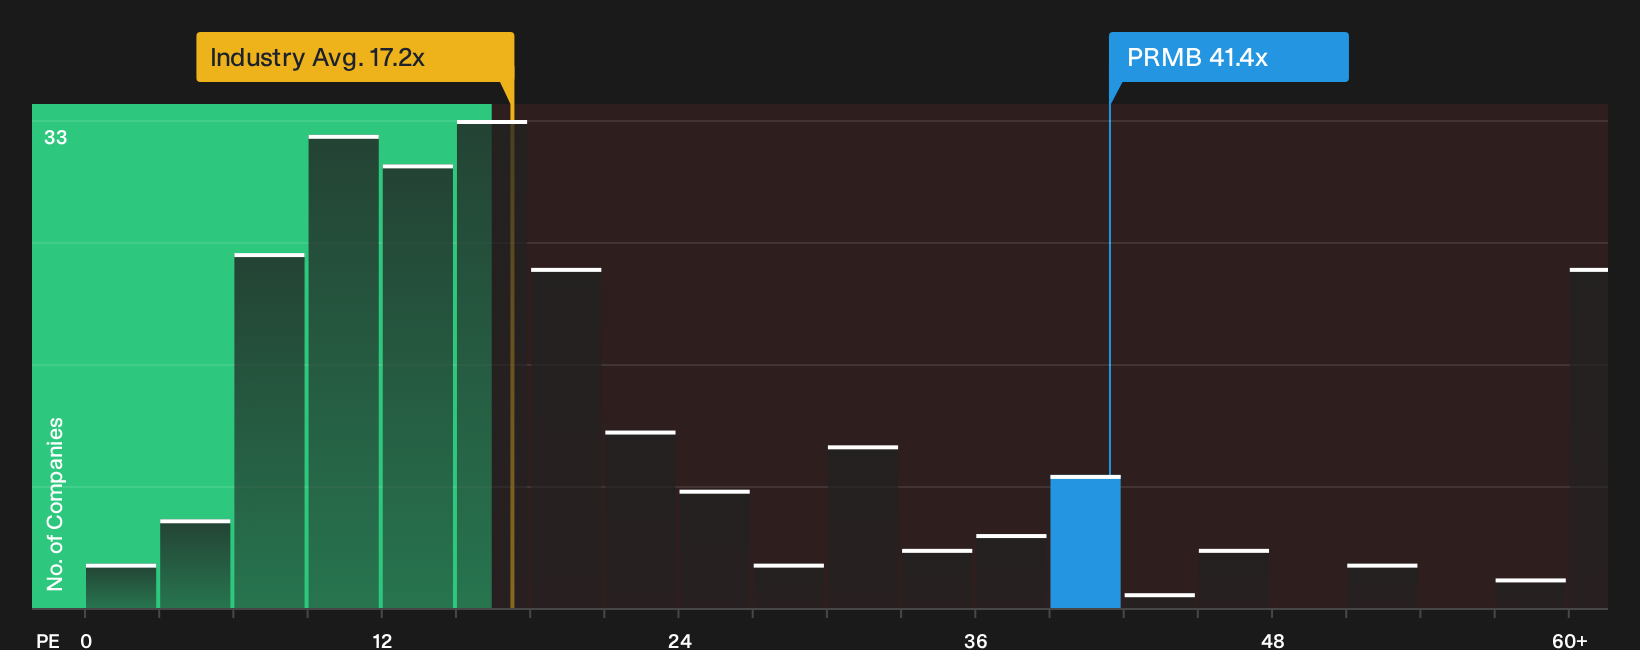
The first narrative around Primo Brands focuses on fair value and cash flows, yet the current pricing tells a more complicated story. At a P/E of 41.4x, the stock trades well above the global beverage group on 17.3x and above peer averages near 27x, even though the estimated fair ratio is 48x.
That combination of a rich headline multiple and a higher fair ratio points to both upside potential and valuation risk, depending on how much earnings progress actually materialises. It raises a straightforward question for investors evaluating Primo Brands today: how comfortable are you paying a premium now with the expectation that the business will earn its way into that valuation?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the upbeat fair value case and the premium P/E story around Primo Brands right now is reasonable, so move fast, check the data for yourself and weigh both the concerns and the upside in 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Primo Brands?
If Primo Brands has you rethinking your watchlist, do not just stop here. Push further, compare more setups and give yourself better options.
- Target resilient opportunities by scanning companies with strong balance sheets and solid fundamentals in our curated list of solid balance sheet and fundamentals (24 results).
- Hunt for potential value by reviewing a focused set of 39 high quality undervalued stocks that pair quality metrics with pricing that may look appealing.
- Strengthen your income playbook by checking a handpicked group of 8 dividend fortresses that aim to combine yield with resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com