


- Power Integrations reported third quarter 2026 sales of US$125.48 million, net income of US$18.32 million, and diluted EPS of US$0.32, with management also issuing fourth quarter revenue guidance of US$118 million to US$126 million.
- The results highlighted strong demand for GaN products, higher gross and operating margins, and a planned quarterly dividend increase to US$0.22 starting in 2027, while the business also cited supply constraints and elevated channel inventory as ongoing operational pressures.
- This raises questions about how Power Integrations' investment narrative may be reshaped by stronger GaN driven margins alongside the firmer revenue outlook.
Scan other GaN and power efficiency plays moving on similar earnings catalysts with our curated list of 52 AI infrastructure stocks to see how Power Integrations compares within this theme.
Power Integrations Investment Narrative Recap
To own Power Integrations, you need to be comfortable with a GaN centric story that leans on data center, EV, and industrial design wins, while the older appliance heavy book of business works through soft demand and channel stock. The latest quarter showed that higher margin GaN products and industrial demand are helping earnings, even as supply constraints and elevated inventory remain real frictions.
The biggest near term swing factor is whether that GaN and industrial momentum can keep offsetting weaker consumer channels while supply bottlenecks ease. The key risk is that any stumble against expectations hits hard, given a rich P/E, appliance exposure, and a dividend that is not fully backed by current earnings.
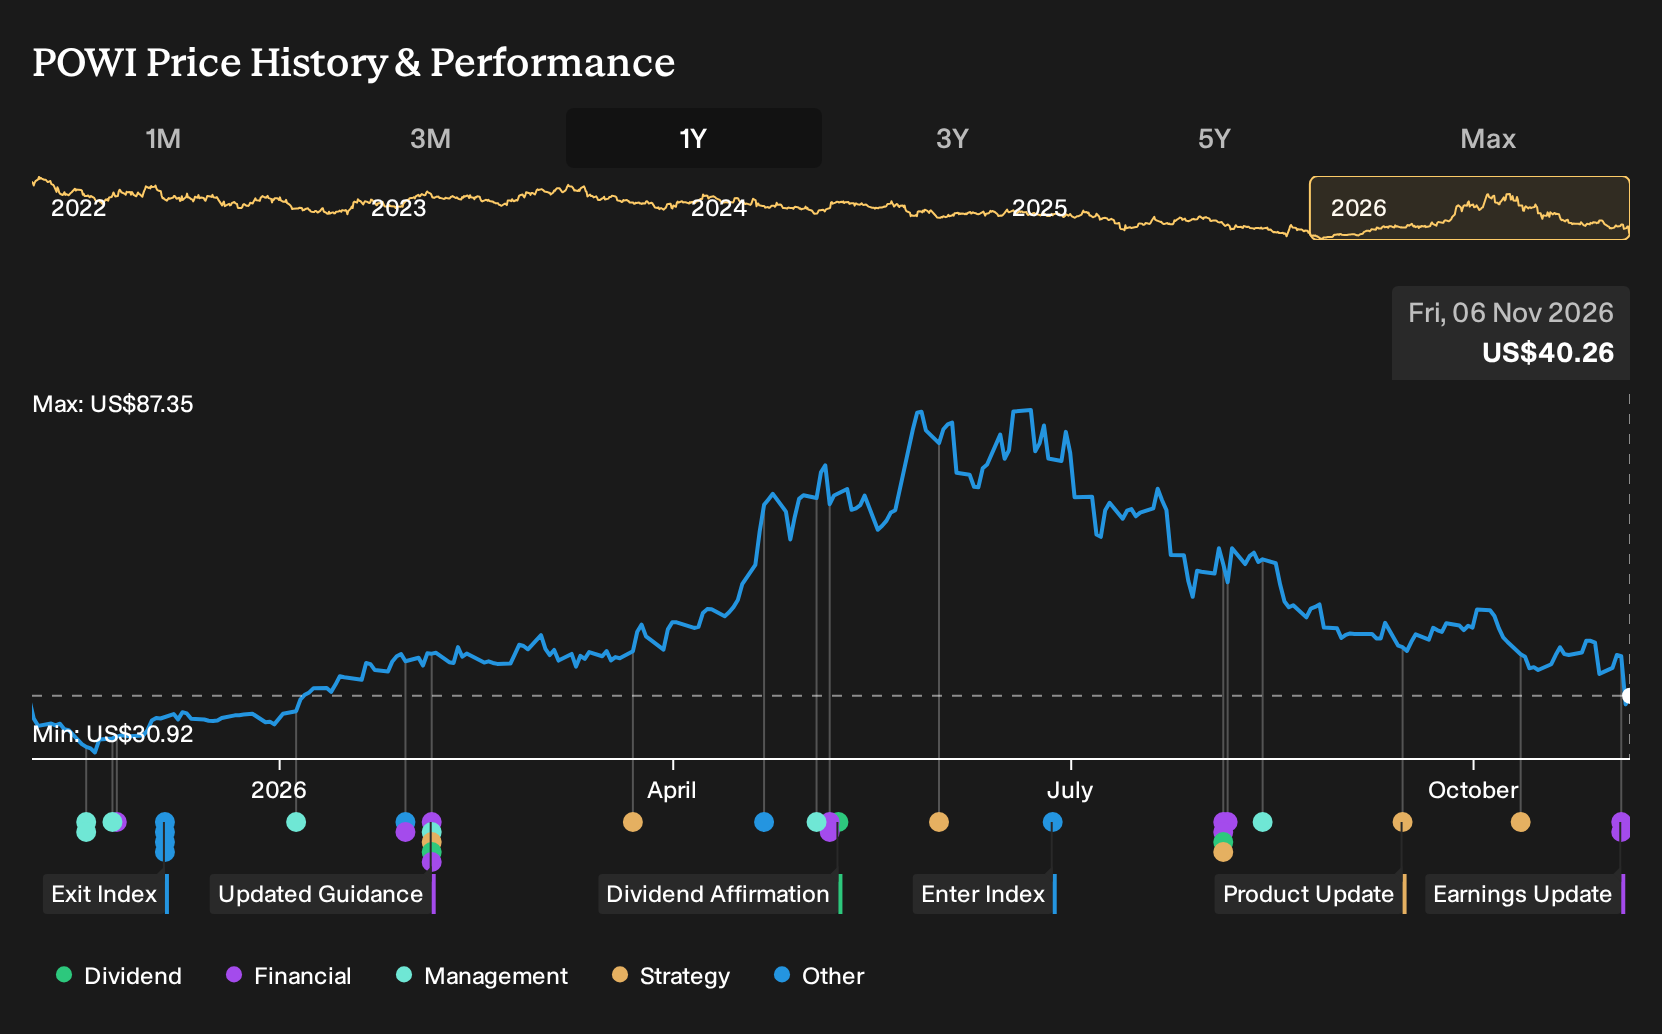
The earnings release for the third quarter of 2026 is the clearest reference point for this setup. Sales reached US$125.48 million with net income of US$18.32 million, and management guided fourth quarter revenue to a range of US$118 million to US$126 million. GaN demand and industrial end markets supported higher gross and operating margins, even with gate driver supply limited by packaging and PCB capacity.
That same update also flagged a planned quarterly dividend increase to US$0.22 from 2027, which matters if you care about total return but also sharpens the question of payout coverage, given current earnings and a 2.19% yield that is not well covered. For catalysts, the focus stays on execution in GaN, data center, automotive, and energy infrastructure, set against the risk that any revenue miss could pressure a still expensive multiple.
Power Integrations' narrative projects US$689.9 million revenue and US$149.1 million earnings by 2029. This is based on analysts' assumed 15.4% yearly revenue growth and an earnings increase of about US$124 million from US$25.1 million today.
Uncover why Power Integrations' fair value indicates a 78% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses less on GaN potential and more on execution risk if industrial, data center, EV, and energy storage projects fail to translate design wins into sustained shipment volumes. Those bullish analysts were penciling in about US$748.5 million of revenue and US$176.8 million of earnings for Power Integrations by 2029 before this earnings release, so their more optimistic storyline could still evolve as the latest numbers filter through.
Explore 3 other Power Integrations fair value estimates, including one that suggests as much as 99% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Power Integrations research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Power Integrations. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Power Integrations' overall financial health at a glance.
Looking for more investment ideas beyond Power Integrations?
If the Power Integrations story has sharpened your thinking, broaden the search window and compare it with other companies that fit different risk and return profiles using the Simply Wall St Screener.
- For investors who want income at the core of their portfolio, scan a focused set of 8 dividend fortresses that combine higher yields with detailed fundamentals.
- If capital preservation and steadier profiles matter most to you, filter for 29 resilient stocks with low risk scores that score well on resilience and downside protection.
- When you are hunting for underfollowed opportunities with strong numbers, sort through 19 high quality undiscovered gems that pair quality metrics with limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com