


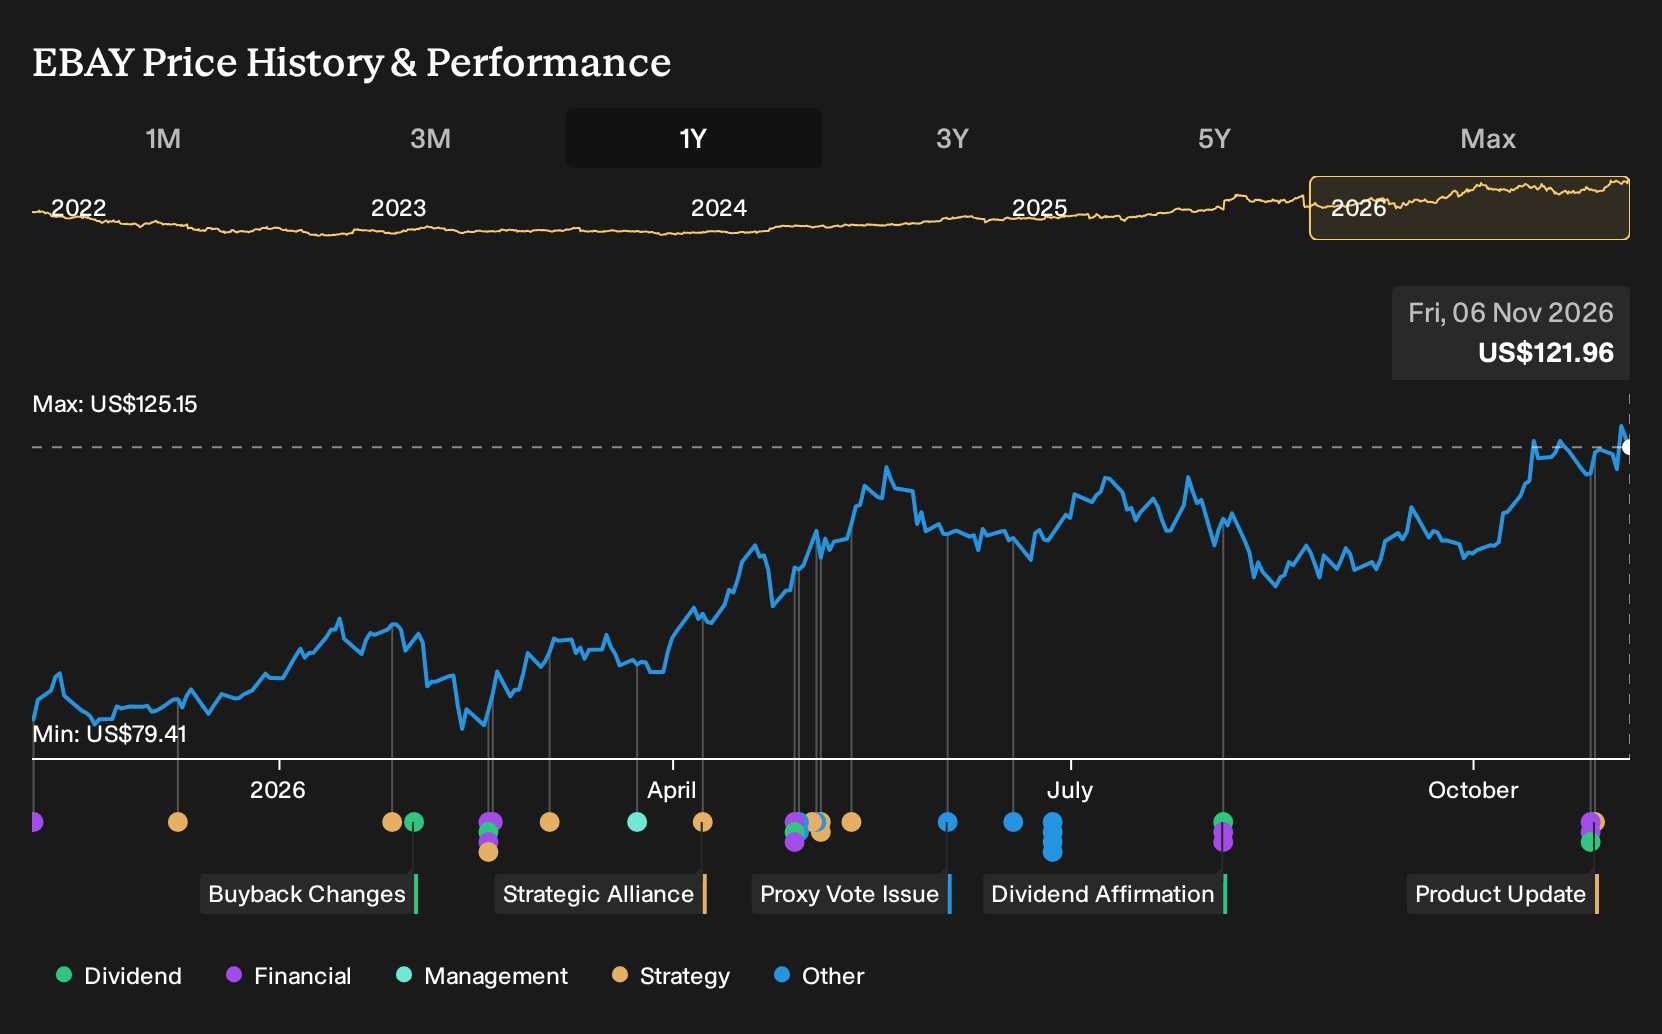
- eBay reported third quarter 2026 results with sales of US$3.206b and net income of US$497m, alongside updated guidance for the fourth quarter and full year.
- The mix of higher 2026 year to date sales of US$9.429b and only modestly higher net income of US$1.559b highlights ongoing cost and margin pressures that matter for how investors view eBay's marketplace performance.
- This article reviews how eBay's investment narrative is affected by its third quarter earnings mix and full year revenue guidance.
eBay Investment Narrative Recap
To own eBay, you need to believe its marketplace can keep attracting high value buyers while the company tightens up on costs. The latest quarter shows that higher sales are not flowing cleanly into profit, so the near term catalyst is better margin execution rather than just more GMV or revenue.
The biggest operational risk is that trust programs, Depop integration and higher transaction losses keep eating into earnings faster than eBay can offset them with advertising and payments revenue. Third quarter numbers and full year guidance keep that risk firmly on the table rather than changing it in a material way.
The most relevant update for that story is the new guidance for the fourth quarter and full year 2026. Management set expectations for GAAP net revenue of US$3.19b to US$3.24b in the fourth quarter and US$12.62b to US$12.67b for the year, alongside diluted GAAP EPS from continuing operations of US$0.82 to US$0.87 for the quarter and US$4.26 to US$4.31 for 2026.
For you as a shareholder, those ranges frame the near term earnings bar that eBay now has to execute against while managing cost pressures and transaction losses. Hitting or missing these figures will matter for how the market judges progress on trust features, Depop and higher margin ad and payments products as potential future catalysts.
eBay's current analyst narrative points to revenues of US$15.1b and earnings of US$2.9b by 2029. These figures are built on an assumed 6.9% yearly revenue growth rate and an earnings increase from US$2.1b today to US$2.9b in the forecast period, which is a rise of about US$0.8b in profit.
Uncover how eBay's fair value compares with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts focus on eBay turning programs like eBay Live and vehicles into long run profit engines, with earlier forecasts that revenues could reach about US$16.6b and earnings US$3.6b by 2029. Those views look more upbeat than consensus and may shift once the latest earnings and Most Wanted car auction are fully digested.
Explore 4 other eBay fair value estimates, including one that suggests up to 30% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your eBay research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for eBay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review eBay's overall financial health at a glance.
Looking For More Investment Ideas Beyond eBay?
If the latest eBay earnings update has you thinking about portfolio balance, it can help to widen the lens and scan for other businesses that fit your risk, income, or quality preferences using the Simply Wall St Screener.
- For investors who want income resilience, review a selection of stocks that have paid out at least 5% in dividends in our 8 dividend fortresses.
- If capital preservation and steadier fundamentals matter most to you, filter for companies that score well on financial strength and low risk using the 29 resilient stocks with low risk scores.
- When you are hunting for quality that the market might be overlooking, start with a curated 19 high quality undiscovered gems that focuses on strong fundamentals with less crowd attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com