


Strong jobs data and higher rate expectations are pulling small caps in two directions at once, rewarding sturdier balance sheets while punishing heavy borrowers. That push and pull is where opportunity often hides, as investors sort companies that can absorb pricier debt from those that struggle. This article walks through three financially healthier U.S. small-cap stocks exposed to the latest macro shock and explains why their profiles may matter for your watchlist.
The three stocks highlighted below are just a starting sample, since the same filters surfaced 39 more small caps with financial profiles and storylines that are not covered here but may deserve a closer look.
To hunt for your own potential ideas, analyze and compare candidates directly inside the U.S. small-cap companies with strong balance sheets and low interest-rate sensitivity screener.
Hudson Technologies (HDSN)
Overview: Hudson Technologies provides refrigerant gases, reclamation and efficiency services that help U.S. commercial and industrial customers keep cooling systems running reliably and within regulations.
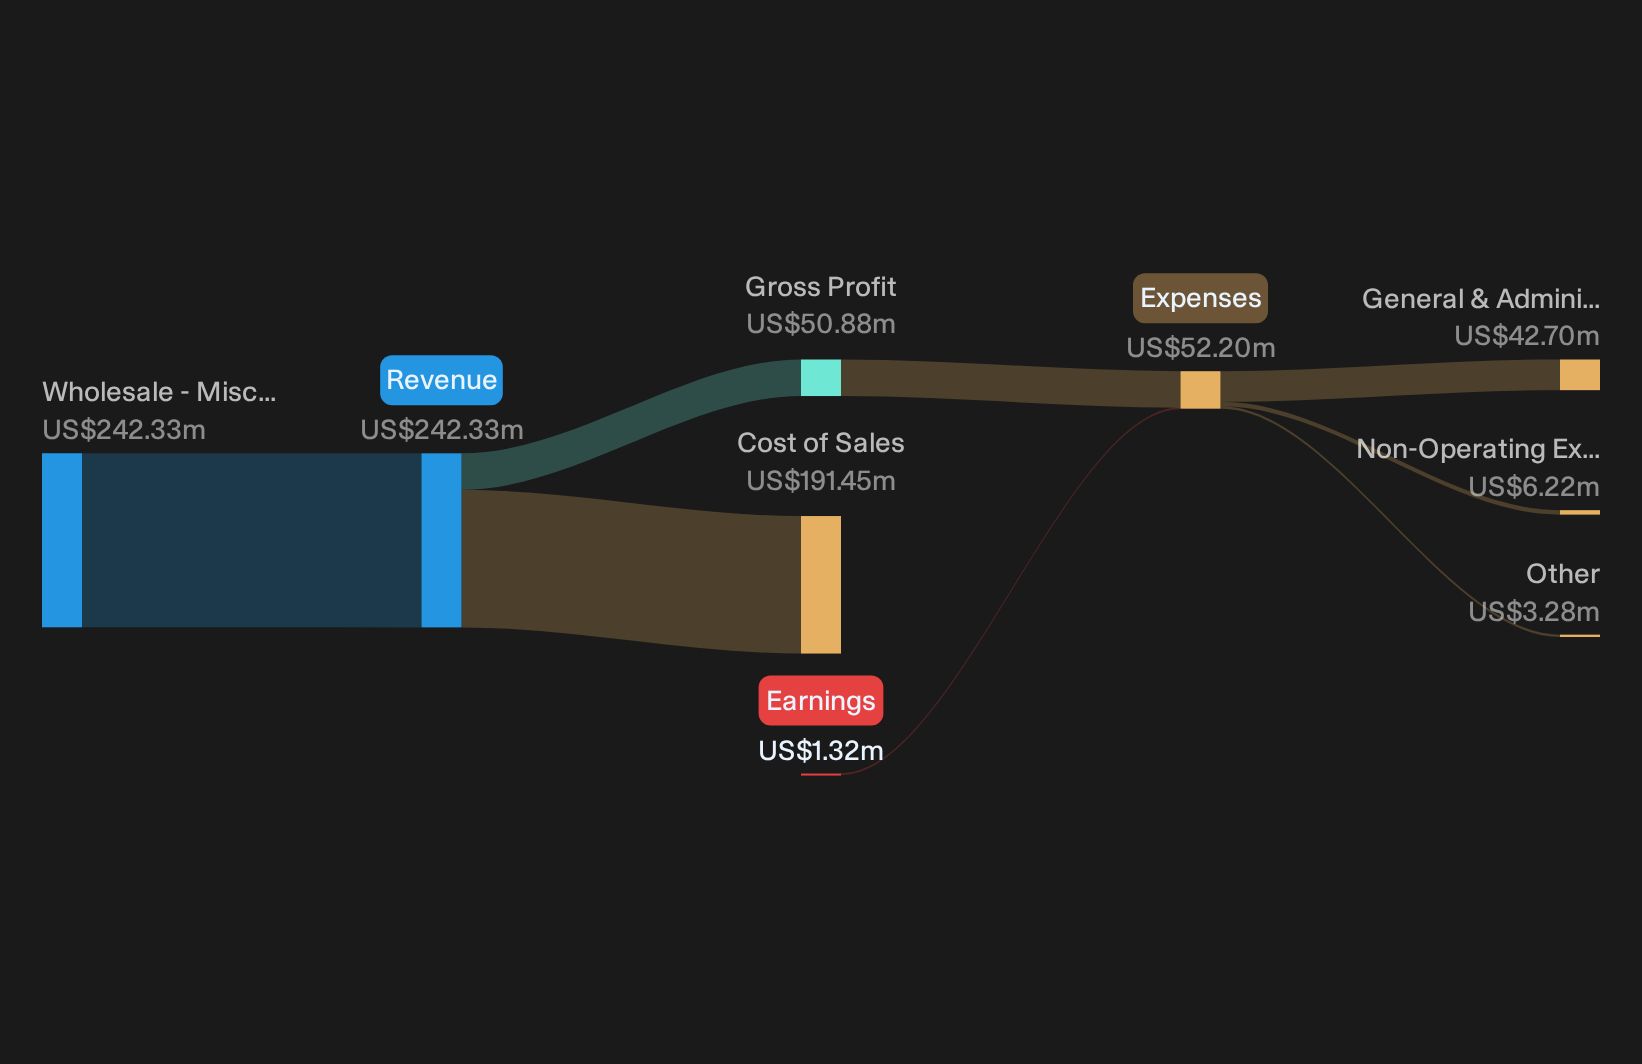
Operations: Hudson Technologies generated US$242 million in wholesale miscellaneous revenue, virtually all from customers in the United States.
Market Cap: US$172 million
Hudson Technologies fits this screener as a small U.S. refrigeration specialist with an asset-light model. In this business, balance sheet strength can matter as much as end-market demand.
"Although regulatory rules in California and New York create defined demand for certified reclaimed refrigerant from January 2027, persistent illegal imports in the millions of pounds and excess channel inventory can keep HFC prices depressed, which would cap Hudson Technologies’ revenue per pound and limit any improvement in gross margin and earnings."
What happens if that pressure on pricing collides with a single key shift in how much reclaimed product the market actually needs?
If you want to see how that pricing risk could be masking Hudson Technologies’ next chapter, read the full narrative for Hudson Technologies for the full picture.
Clearfield (CLFD)
Overview: Clearfield designs and supplies fiber management and connectivity gear that helps broadband providers build and upgrade high speed networks efficiently.
Operations: Clearfield reported US$153.7 million in revenue, with about US$147.5 million from the United States and US$6.2 million from other regions.
Market Cap: US$390 million
Clearfield fits this financial health screen as a U.S.-focused broadband equipment maker that relies on a capital-light, often net cash balance sheet rather than heavy borrowing. This can matter when rate expectations move higher.
"Clearfield is poised to benefit from expanding broadband adoption in underserved regions, as reflected by ongoing government infrastructure support and continued rural fiber deployments, positioning the company for sustained revenue growth as deferred BEAD-funded projects materialize in upcoming periods."
What happens to Clearfield’s earnings power if a single assumption about future broadband build intensity or customer ordering patterns shifts again?
If that single assumption feels like the real swing factor, read the full narrative for Clearfield to see how Clearfield’s risk and opportunity profile could be quietly accelerating.

Zumiez (ZUMZ)
Overview: Zumiez is a specialty retailer selling youth-focused apparel, footwear, accessories and board sports gear, with a strong U.S. presence and relatively low leverage.
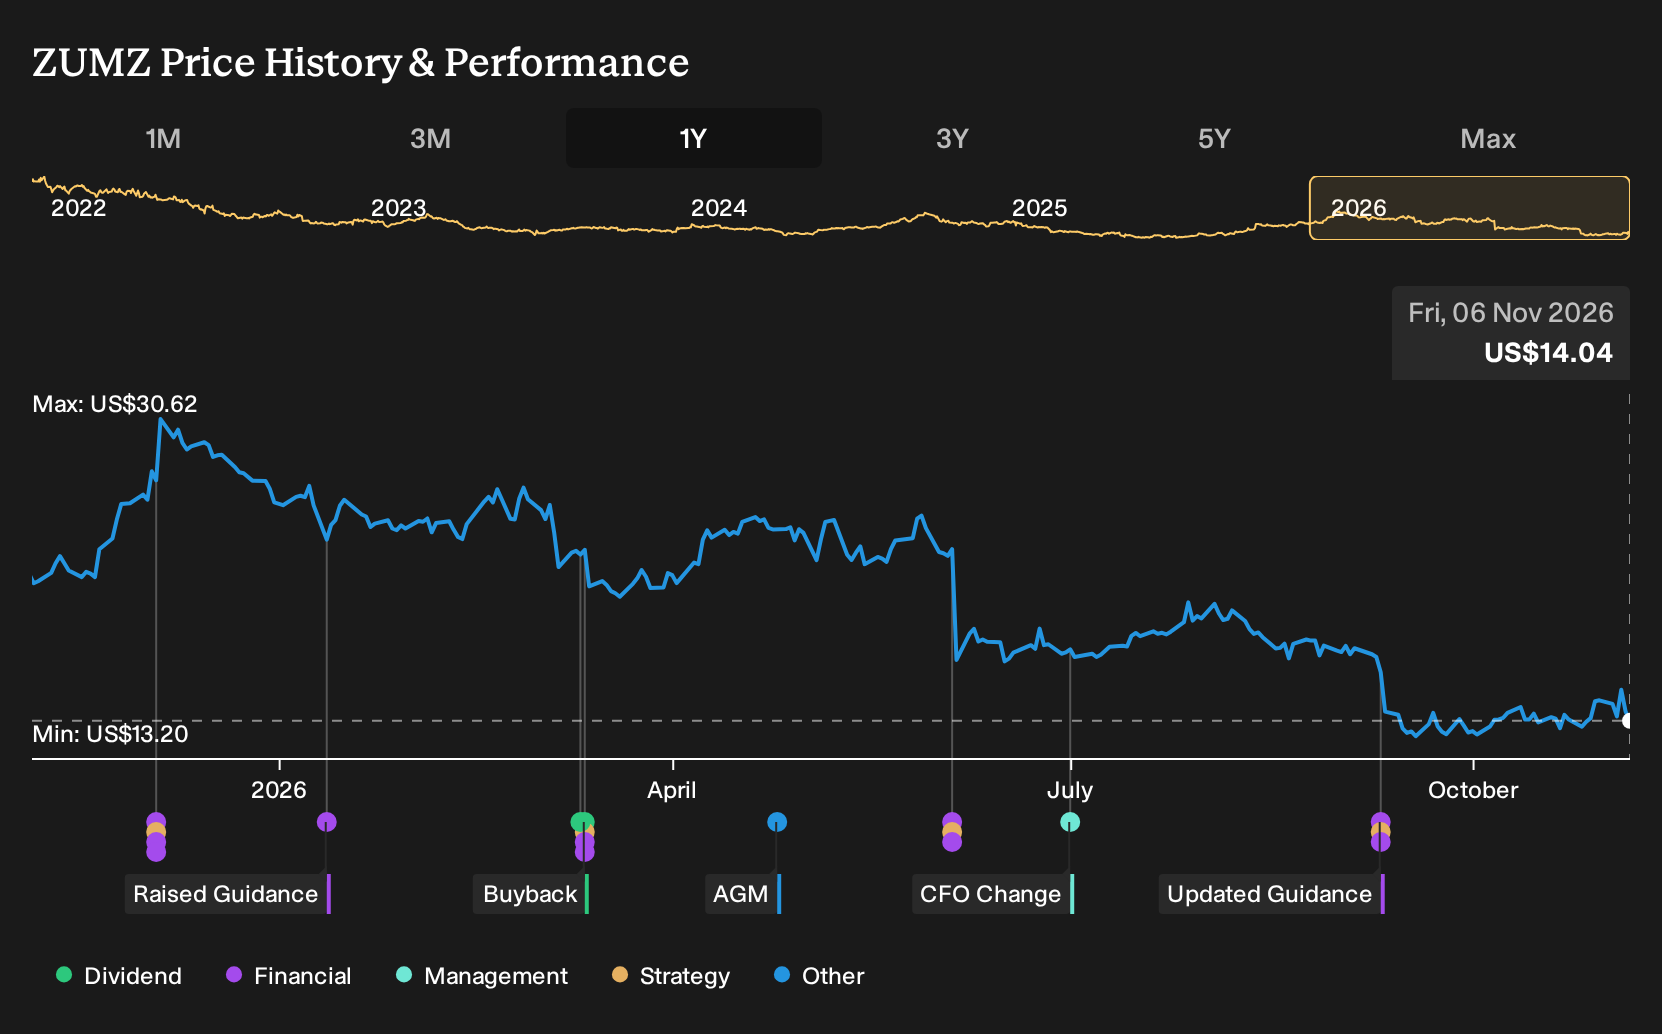
Operations: Zumiez generates about US$932.8 million from retail apparel, primarily in the United States at US$706.5 million, with Canada, Europe and Australia contributing the rest.
Market Cap: US$215.2 million
Zumiez fits this small-cap financial health screen because its balance sheet tends to be conservative while its core shopper depends heavily on employment and wage trends.
"Proactive supply chain diversification and reduction of China exposure (targeting less than 20% from any single country by 2026) mitigates tariff and geopolitical risks, enhancing gross margins and reducing future cost volatility. This may support more stable earnings."
The real swing factor may be how one less visible pressure on customer demand interacts with that careful financial footing over the next few years.
That quieter demand pressure is the real story, and the full narrative for Zumiez shows how Zumiez could turn that into accelerating leverage on its cleaner balance sheet.
Seeking Fresh Alternatives Before They Fly
Market momentum can flip fast, and the best under the radar ideas often move first. Scan fresh candidates before the crowd, while it matters, and get in early.
- Target sturdier payouts from companies that aim to keep income streams flowing even when prices swing by scanning this curated set of 8 dividend fortresses.
- Hunt for quietly compounding businesses where strong cash generation meets disciplined balance sheets using a focused group of 39 high quality undervalued stocks.
- Zero in on growth powered by real adoption of machine learning tools across industries by reviewing a hand picked mix of 41 profitable AI stocks that aren't just burning cash.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com