


Starwood Property Trust (STWD) just posted third quarter 2026 results, reporting higher revenue alongside a sharp swing into loss. That combination of stronger top line and heavier red ink is what investors are reacting to.
The earnings shock has landed on a stock that was already under pressure. Starwood Property Trust’s share price is down 26.75% over the past 90 days and 34.58% year to date, while the 1 year total shareholder return has declined 26.47%. This points to fading momentum as investors reassess both income prospects and balance sheet risk.
Scan how other income focused plays are holding up under similar pressure by checking our curated 8 dividend fortresses alongside Starwood Property Trust after these results.
Starwood Property Trust now trades well below its recent levels, after a quarter that raised fresh questions about earnings quality. Is that drop enough to justify stepping in today, or does patience still look cheaper?
Most Popular Narrative: 36% Undervalued
At a last close of $12.05, the most followed narrative on Starwood Property Trust pegs fair value at $18.88, which frames the recent selloff as a valuation gap rather than just a sentiment slide.
The current valuation implies the share price does not fully reflect the potential earnings contribution from resolving about $1.9b of nonaccrual and REO assets, the growth in the $3.1 to $3.2b infrastructure portfolio, and the ramp of the $2.7b net lease platform. This supports the view that Starwood Property Trust is undervalued and that the market is cautious about dividend sustainability.
See why 51 investors see Starwood Property Trust as 36% undervalued.
Result: Fair Value of $18.88 (UNDERVALUED)
Still, Starwood Property Trust faces two clear swing factors: dividend coverage that currently trails payouts and a US$1.9b nonaccrual and REO book that needs timely resolution.
Find out about the key risks to this Starwood Property Trust narrative.
Another View: SWS DCF Model Paints A Tougher Picture
The crowd narrative on Starwood Property Trust leans on a fair value of $18.88, yet the SWS DCF model lands in a very different place. On that cash flow view, estimated value sits at $6.02, which frames the current $12.05 price as expensive rather than cheap. Which lens do you trust more for a long term income play?
Look into how the SWS DCF model arrives at its fair value.
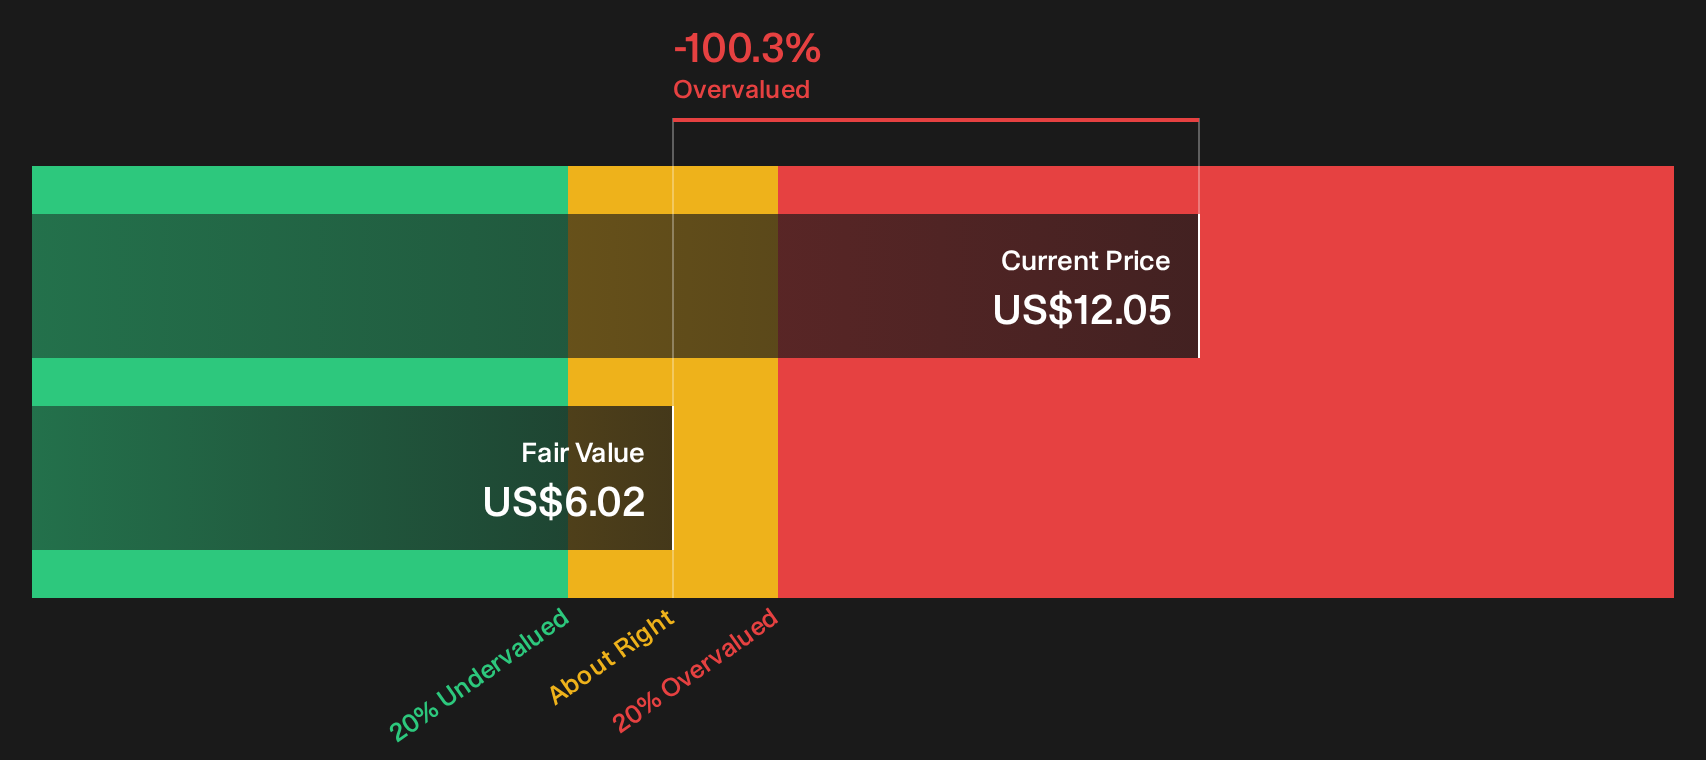
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Starwood Property Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Starwood Property Trust so far. If you want to move fast and evaluate the trade-off yourself, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Starwood Property Trust?
If Starwood Property Trust has sharpened your focus on risk, income and entry price, do not stop here. Broaden your watchlist and pressure test your next moves with a wider field of candidates.
- Target resilient income by reviewing a curated set of higher yielding payers through the 8 dividend fortresses.
- Hunt for mispriced quality by scanning the 39 high quality undervalued stocks that combine solid fundamentals with more appealing valuations.
- Protect the downside first by filtering for companies on the 29 resilient stocks with low risk scores that score well on financial strength and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com