


Hillman Solutions (HLMN) just posted third quarter results showing higher sales alongside sharply lower net income, while also trimming full year net sales guidance. This combination gives investors fresh information to reassess the stock.
The mixed earnings picture and trimmed outlook have arrived after a choppy year for Hillman Solutions, with the share price up 19.88% over the past month but still down 4.48% year to date. That rebound, set against a 5.02% decline in 1 year total shareholder return and a 19.71% gain over 3 years, suggests short term momentum is improving while the longer term record remains uneven as investors reassess both growth potential and risk after the latest results and guidance cut.
Compare Hillman Solutions to a curated group of peers under fresh earnings pressure by scanning the 39 high quality undervalued stocks, which pairs balance sheet strength with discounted valuations.
Hillman Solutions just rallied hard while guiding net sales slightly lower and reporting thinner profit. Is this move a clearer read on the underlying business, or a fast swing in sentiment that valuation now needs to test?
Most Popular Narrative: 31% Undervalued
Hillman Solutions closed at $8.32, while the most followed narrative pegs fair value at $12.00 using a 9.87% discount rate. That gap frames the recent earnings wobble as a valuation question rather than just a quarter to quarter story.
The ongoing rollout and utilization of the Robotics & Digital Solutions platform, including the MinuteKey 3.5 kiosks that are being deployed across thousands of locations with EBITDA margins near 30% to 32%, provides a scalable source of higher margin revenue that can have a meaningful impact on overall earnings quality.
See why 1 investors see Hillman Solutions as 31% undervalued.
Result: Fair Value of $12.00 (UNDERVALUED)
Still, the Hillman Solutions narrative can crack if weakness in Protective Solutions persists and if returns on invested capital remain stuck near the low single digits.
Find out about the key risks to this Hillman Solutions narrative.
Another View On Hillman Solutions Using Market Multiples
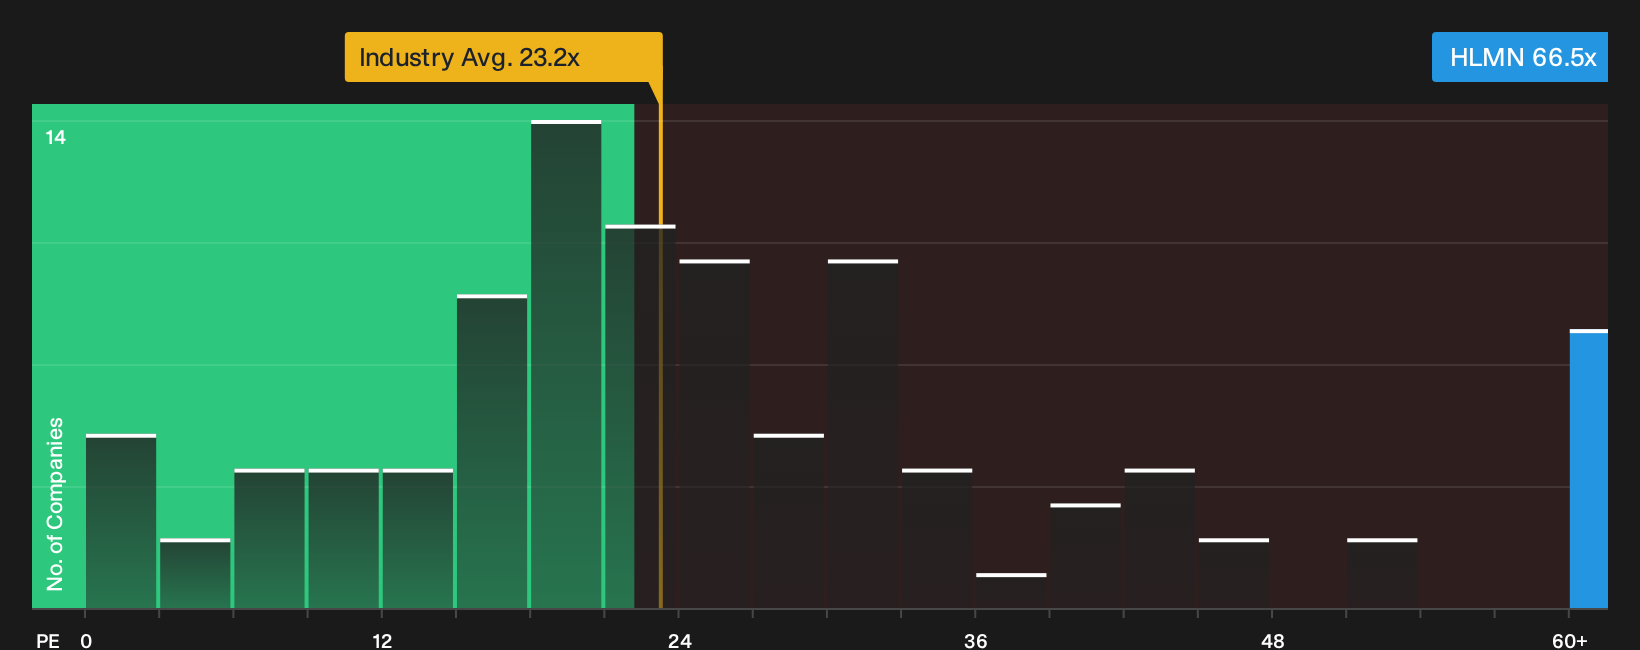
The DCF style fair value narrative presents Hillman Solutions as materially undervalued around $8.32 per share. A simple P/E check tells a very different story. The stock trades on about 66.5x earnings, compared with roughly 23.1x for the US Machinery group and a fair ratio estimate of 43.2x.
That gap means investors today are paying a much richer multiple than both peers and the fair ratio suggest. This raises the risk that any disappointment in delivery against forecasts could affect the share price more than the DCF framework implies. Which lens feels more realistic for how you expect the next few years to unfold for Hillman Solutions.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Hillman Solutions story so far. Act while the data is fresh, review the underlying figures, and weigh the 3 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Hillman Solutions?
Use fresh data while momentum and risk are front of mind, and scan other candidates where valuation, balance sheets, and income potential might line up more cleanly for you.
- Target potential mispricings by running through the 39 high quality undervalued stocks that filters for high quality businesses trading below fundamental estimates.
- Strengthen your downside protection by reviewing the 29 resilient stocks with low risk scores focused on resilient companies with lower risk profiles.
- Hunt for tomorrow's quiet winners by checking the 19 high quality undiscovered gems that surfaces lesser known stocks with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com