


Q3 results and dividend move put Artisan Partners Asset Management in focus
Artisan Partners Asset Management (APAM) came back into focus after reporting third quarter and nine month 2026 results, alongside a fresh variable dividend tied to cash generated in the September period.
That dividend decision came after a busy stretch for Artisan Partners Asset Management. The share price climbed 15.94% over the past month, despite a decline of 8.04% over 90 days and a year-to-date fall of 5.51% in share price terms. Meanwhile, the 3-year total shareholder return of 37.82% and 5-year total shareholder return of 17.08% indicate momentum that has developed over a longer horizon as investors reassess both growth prospects and risk around the latest earnings and payout news.
Scan Artisan Partners Asset Management alongside hand picked dividend payers that convert quarterly cash into shareholder income, using the 8 dividend fortresses as a starting universe.
Artisan Partners Asset Management now combines a high cash payout with earnings that held up through the latest quarter. The real tension sits in the price. Are you paying up for quality, or still getting a deal?
Most Popular Narrative: 11% Overvalued
Against the last close at $39.13, the most followed narrative pegs Artisan Partners Asset Management at a fair value of $35.25, which frames the recent rally as pricing in more than the base case for flat revenues and modest margin gains.
The main factor that has to go right is that growth in credit, alternatives, and broader distribution channels offsets ongoing equity outflows and the wind down of the U.S. Value team.
New and recently added strategies in areas such as credit, alternatives and multi asset offerings increase execution risk, since returns on these investments and associated fundraising still need to scale sufficiently to offset the modest 2.8% annual revenue growth and declining EPS reported over the past five years.
See why 23 investors see Artisan Partners Asset Management as 11% overvalued.
Result: Fair Value of $35.25 (OVERVALUED)
Still, the narrative can break if equity outflows deepen beyond recent US$10.5b pressures, or if new credit and alternative strategies fail to scale as planned.
Find out about the key risks to this Artisan Partners Asset Management narrative.
Another View: Artisan Partners Asset Management Through Earnings Multiples
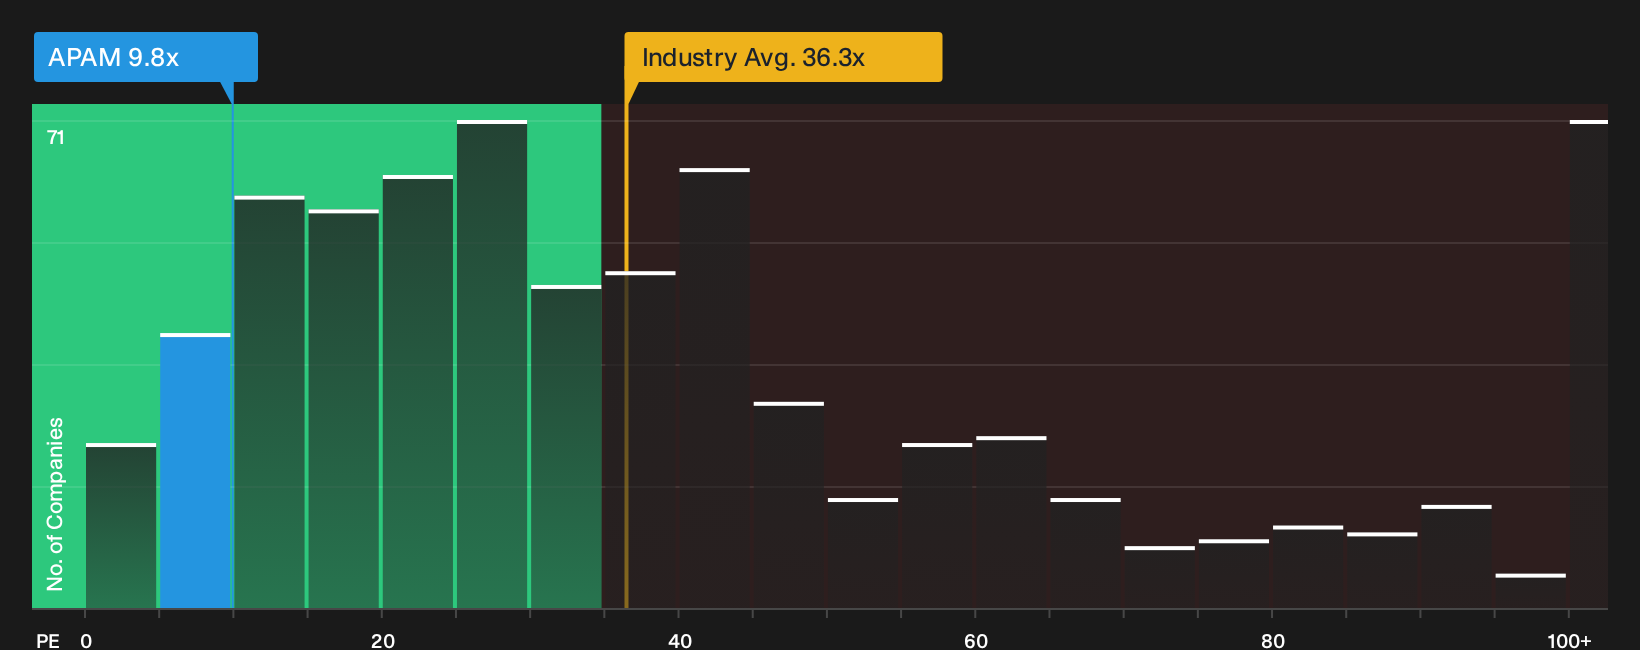
The first narrative framed Artisan Partners Asset Management as about 11% overvalued using analyst targets and margin assumptions. On a simple P/E lens, the picture looks less stretched. APAM trades on 9.8x earnings, compared with a fair ratio of 10.1x and a US Capital Markets average of 36.7x, while peers sit around 18.7x. That gap points to a stock priced more cautiously than both its sector and direct comparables, even as analysts expect revenue to grow only 0.3% a year and earnings to decline 1.2% a year over the next three years. The question is whether that discount reflects those softer forecasts enough, or if investors are still paying too much for a 10.3% dividend that is not well covered by free cash flow.
For a closer look at how these earnings ratios might shift if sentiment or sector conditions change, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about whether Artisan Partners Asset Management is priced for its risks or its potential upside right now? Move quickly from headline impressions to hard data by weighing 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Artisan Partners Asset Management?
If Artisan Partners Asset Management has you thinking more broadly about risk, income, and value, it is worth lining up a few fresh candidates beside it.
- Target steadier portfolios by scanning companies that pass strict quality checks and carry conservative risk profiles through the 29 resilient stocks with low risk scores.
- Hunt for mispriced opportunities by filtering for strong fundamentals and supportive valuations using the 39 high quality undervalued stocks.
- Build a watchlist of resilient payers by focusing on balance sheets and earnings strength with the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com