


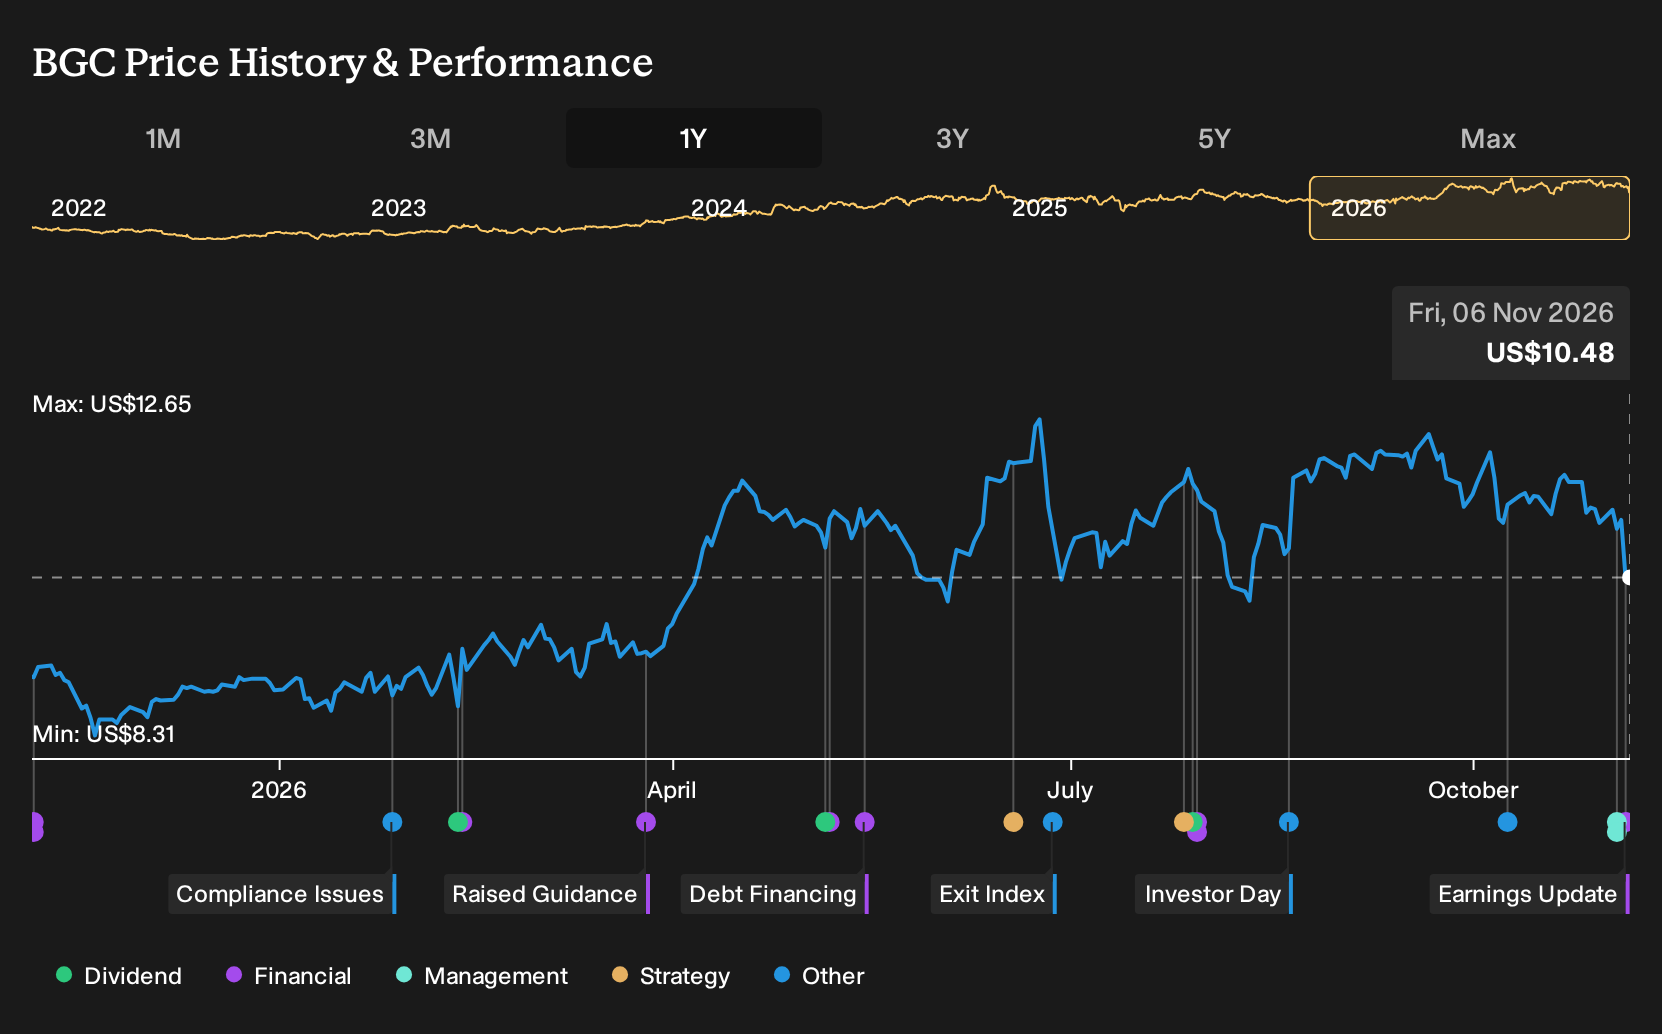
- BGC Group reported third quarter 2026 revenue of US$832.56 million and net income of US$71.29 million, with basic earnings per share from continuing operations of US$0.15, alongside credit rating upgrades to BBB+ and A- from KBRA and JCRA.
- The business highlighted its first fully AI-brokered institutional trade in listed equity derivatives and continued to push electronic volumes through its FMX platform, while also announcing that Co-CEO JP Aubin will shift to Vice Chairman at year end 2026.
- This article now examines how BGC Group's reported quarterly performance and AI-brokered trading milestone relate to the broader investment narrative.
Scan how BGC Group's AI push and trading update compare with other potential candidates by reviewing a curated set of 52 AI infrastructure stocks in the market right now.
What Is BGC Group's Investment Narrative?
To own BGC Group, you need to buy into a story where a traditional brokerage leans heavily on electronic trading, AI workflows and data to keep volumes flowing across rates, FX, equities and commodities, while carrying a balance sheet that uses more debt than some investors might like. The latest quarter adds evidence on execution. Record Q3 revenue of US$832.56 million, higher net income of US$71.29 million and credit upgrades to BBB+ and A, plus a small US$0.02 dividend, all point to a business that is currently handling its capital intensity and technology spend without obvious strain.
The near term hinges on whether BGC Group can keep growing electronic and FMX volumes, convert its first fully AI brokered trade in listed equity derivatives into repeatable flow and build a real market around compute infrastructure contracts. Leadership changes matter here. JP Aubin shifting from Co CEO to Vice Chairman at year end 2026 keeps him engaged but places more day to day execution on the remaining Co CEOs just as AI and electronic platforms scale. Forecasts that point to slower revenue growth than the wider US market, together with high leverage and one off items in recent earnings, frame the main risks if trading conditions cool.
That said, beneath the AI headlines and record quarter, one structural pressure on BGC Group still hangs over the story...
There's only one way to know the right time to buy, sell or hold BGC Group. Head to Simply Wall St's company report for the latest analysis of BGC Group's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BGC Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BGC Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BGC Group's overall financial health at a glance.
Looking For More Ideas Beyond BGC Group?
If BGC Group has sharpened your focus on where to deploy capital next, it can help to line it up against other opportunities that match different risk and income preferences.
- If you want potential income combined with resilience, start by scanning a curated group of 8 dividend fortresses that emphasise yield with a focus on durability.
- For readers who care most about financial strength and balance sheet quality, work through a list of solid balance sheet and fundamentals (24 results) to see which businesses currently pair low leverage with healthier fundamentals.
- If you are hunting for opportunities that the broader market may not be paying much attention to yet, sort through a hand picked pool of 19 high quality undiscovered gems that blend quality metrics with lower visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com