


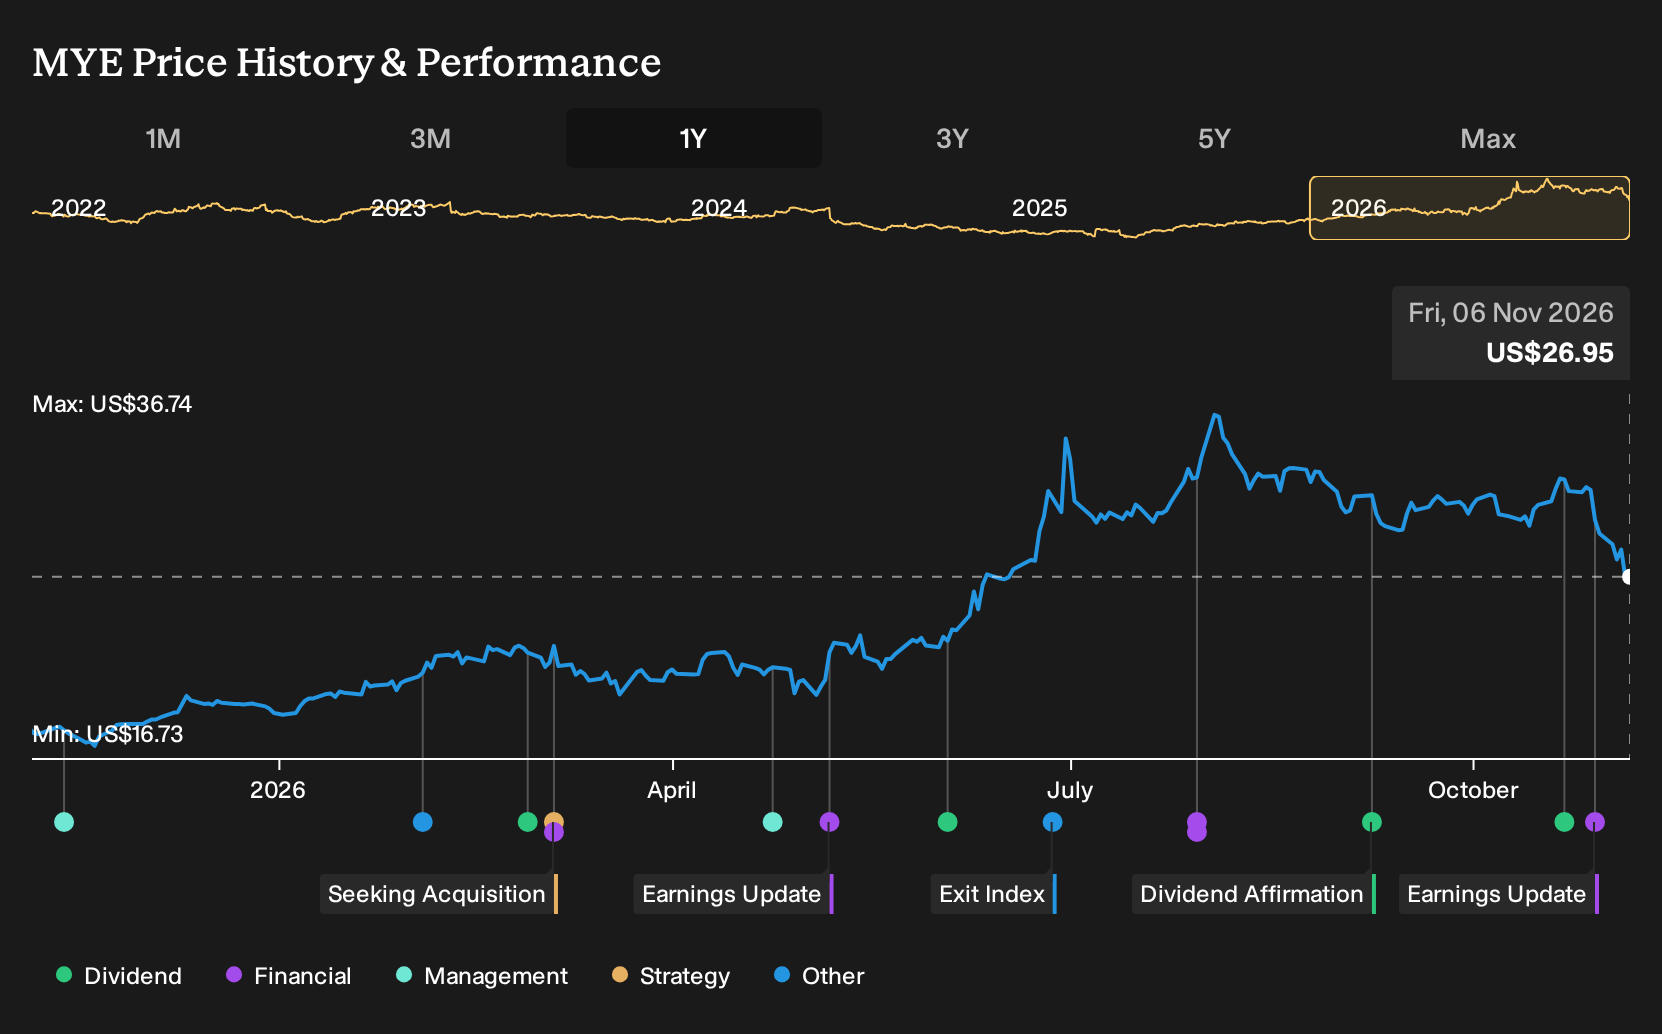
- Myers Industries reported third quarter 2026 results, with sales of US$171.34 million compared with US$158.47 million a year earlier and a net loss of US$0.865 million versus prior net income.
- The mixed picture included higher year to date sales of US$515.12 million compared with US$483.37 million, while net income for the nine months declined to US$17.34 million from US$23.6 million, highlighting pressure on profitability despite top line progress.
- We will now look at how Myers Industries' investment narrative compares with higher quarterly revenue but a swing to a net loss.
Compare Myers Industries' latest earnings swing with a hand-picked 39 high quality undervalued stocks that also show stronger balance sheets and cash generation profiles.
Myers Industries Investment Narrative Recap
To own Myers Industries, you need to be comfortable with a story where operational improvement and portfolio focus matter more than smooth quarterly earnings. The latest report shows higher sales but a move to a small loss, which puts more attention on how well the firm can manage input costs and pricing over the next few quarters.
The main short term swing factor remains execution in higher margin infrastructure and defense resin products, supported by the Focused Transformation cost program. The biggest risk is still resin price pressure and softer end markets like U.S. RVs, which the recent net loss underlines rather than fundamentally changes.
The third quarter 2026 earnings announcement is the clearest lens for this. Myers Industries reported sales of US$171.34 million and a net loss of US$0.865 million, plus nine month net income down to US$17.34 million. Earnings per share stayed positive on a continuing operations basis, which provides some cushion to the longer term efficiency story.
This mix of higher revenue and softer profitability ties directly into the existing catalysts. Record infrastructure and defense opportunities, cost savings from Focused Transformation, and prior balance sheet work all still matter, but execution risk appears more visible. For you as a shareholder, that makes resin costs, order stability, and cash generation key items to watch after this quarter.
Myers Industries' current earnings of US$50.7 million are set against analyst expectations for US$95.2 million of earnings on US$677.3 million of revenue by 2029. That forecast implies revenue declining 7.1% per year and an earnings increase of about US$44.5 million by the 2029 estimate year.
Uncover why Myers Industries' fair value indicates a 37% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community span roughly US$37 to about US$60 per share, which signals very different views on Myers Industries. You are looking at a small sample, but it already reflects how far opinions can diverge. Consider resin cost risk, RV softness, and infrastructure or defense demand before deciding which camp you lean toward, and explore more community viewpoints to test your own thesis.
Explore another Myers Industries fair value estimate, including one that suggests it could be worth just $37.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Myers Industries research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Myers Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Myers Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Myers Industries?
Once you understand where Myers Industries fits in your portfolio, it can help to line it up against other opportunities that offer different mixes of quality, risk, and income. The Simply Wall St Screener is built for exactly that comparison, letting you filter by balance sheet strength, earnings profile, and dividend yield in just a few clicks.
- If resilience matters most to you, start with companies that pair steadier financial profiles with measured risk using the 29 resilient stocks with low risk scores.
- For investors who care about underlying financial strength and clean balance sheets, sort through a list of solid balance sheet and fundamentals (24 results) that can sit alongside a position in Myers Industries.
- If you want ideas that are not widely followed yet still supported by solid fundamentals, scan a curated 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com