


- Summit Therapeutics reported a third quarter 2026 net loss of US$208.39 million and a nine month loss of US$613.51 million, with basic and diluted loss per share from continuing operations at US$0.26 for the quarter and US$0.78 for the nine month period.
- Investors now have a clearer picture of Summit Therapeutics’ funding capacity after shareholders approved an increase in authorized common stock to 2 billion shares, which could shape how the company finances its ivonescimab program and broader late stage pipeline.
- The focus now is on how Summit Therapeutics’ narrower losses and expanded authorized share capital may influence the longer term investment narrative.
Summit Therapeutics Investment Narrative Recap
To own Summit Therapeutics, you need to support the idea that ivonescimab can transition from a cash-consuming late-stage project to a commercial product across multiple tumor types. The latest quarter still shows heavy losses, with a US$208.39 million deficit and no product revenue. Slightly narrower losses do not change that core reality.
The key near-term catalyst remains clinical and regulatory progress, particularly around the HARMONi program, since one lead drug supports a very broad trial footprint. The biggest risk is straightforward: ongoing trial, launch, or uptake setbacks could keep cash burn high for longer, especially with no offsetting sales.
The most directly relevant update is the amendment that lifts authorized common stock to 2 billion shares within a total of 2.02 billion authorized shares. For a business with a US$613.51 million loss over nine months and zero revenue, that additional headroom gives management more options to raise capital if needed to keep the ivonescimab program moving.
For shareholders, that creates a clear tension between funding the late-stage pipeline and potential dilution. The broader investment case around Summit Therapeutics, including the many Phase III trials and partner programs, still centers on whether future data support eventual commercialization strongly enough to justify continued capital needs.
Summit Therapeutics' current analyst narrative points to forecast revenue of US$1.2b and projected earnings of US$197.7 million by 2029. That implies a shift from the reported earnings loss of US$856.1 million today to forecast positive earnings in 2029, an earnings swing of roughly US$1.1b. Consensus assumptions effectively treat this as a move from zero revenue to the projected top line by the end of the forecast period.
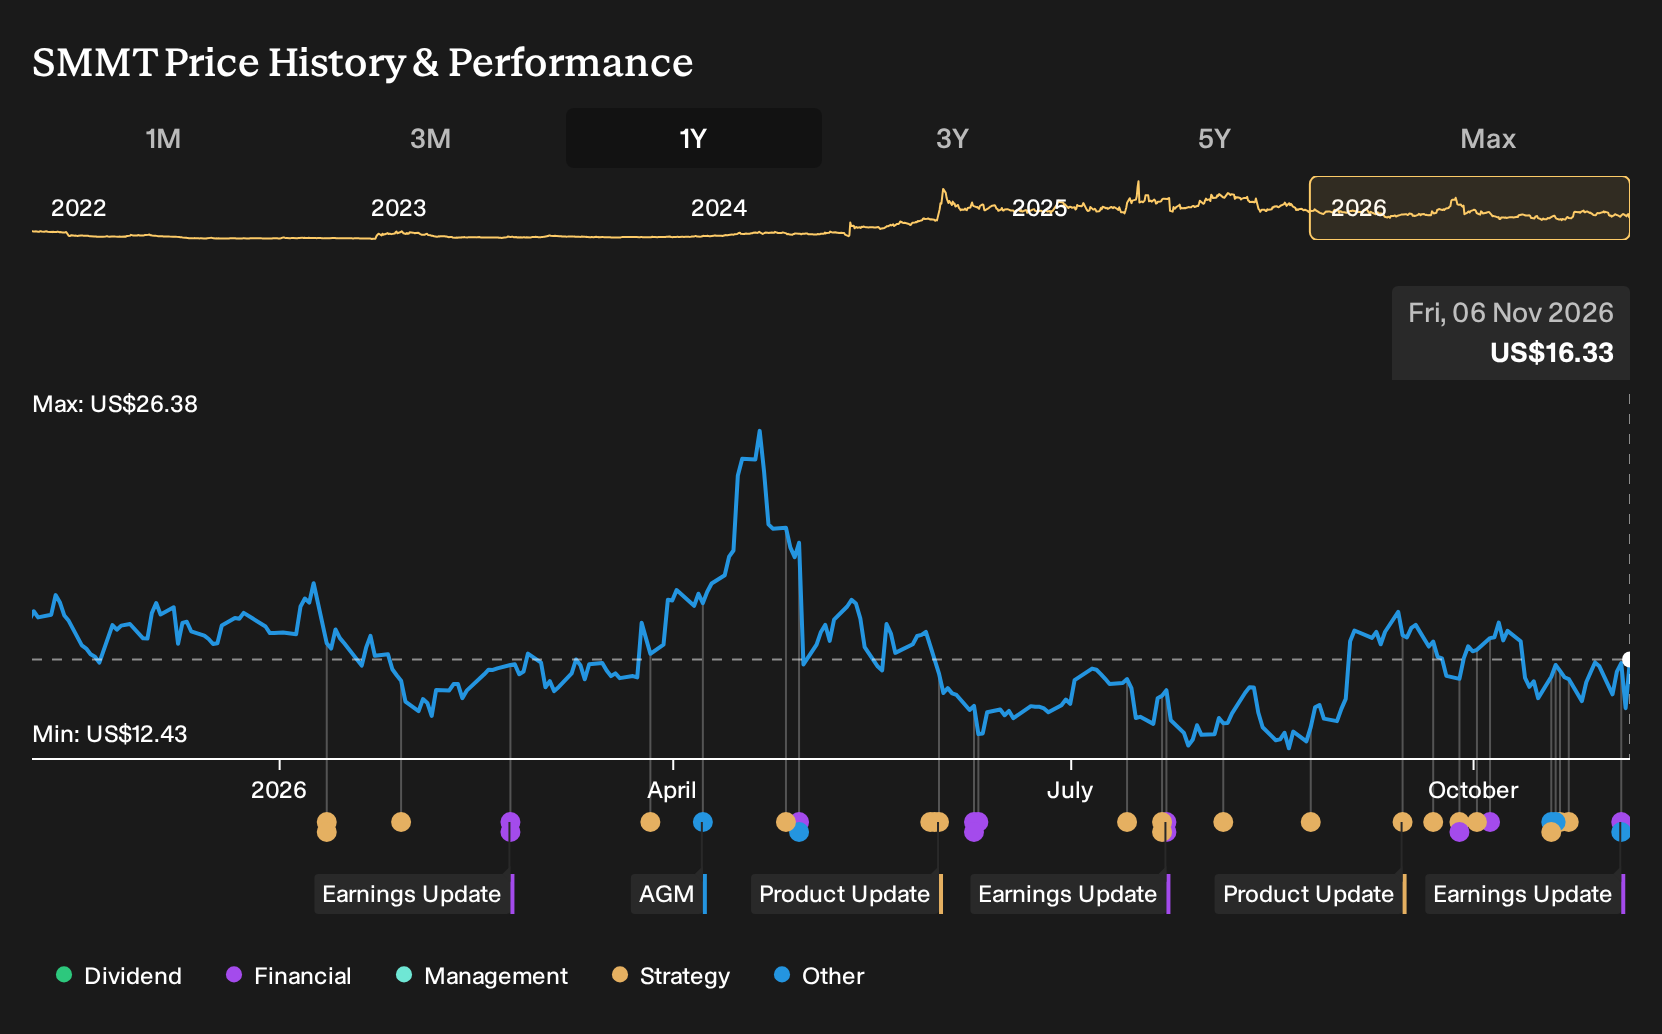
Uncover why Summit Therapeutics' fair value indicates an 84% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate storyline leans hard into dilution risk. Those more pessimistic analysts were only modeling about US$16.8 million in 2029 revenue and roughly US$2.9 million in earnings, with a very high implied P/E multiple. That view treats Summit Therapeutics’ expanded share count and ongoing cash burn as far more problematic, and the new results could shift those assumptions.
Explore 4 other Summit Therapeutics fair value estimates, including one that suggests as much as 27% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Summit Therapeutics research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Summit Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Summit Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Summit Therapeutics?
If the Summit Therapeutics story has you thinking about position sizing, risk tolerance, and where it fits in your wider portfolio, it can help to line it up against other opportunities with very different profiles. The Simply Wall St Screener gives you a quick way to do that by filtering for the types of businesses that balance or complement a high-risk biotech like this one.
- For investors who want potential upside with strict balance sheet discipline, scan a list of solid balance sheet and fundamentals (24 results) that can help anchor a riskier basket.
- If value is your priority and you want to focus on quality at a sensible price, sort through 39 high quality undervalued stocks that match tighter fundamentals and pricing filters.
- When you are hunting for less obvious opportunities that the market may not be focused on yet, cast a wider net across 19 high quality undiscovered gems that still show strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com