


RLJ Lodging Trust earnings event and why it matters now
RLJ Lodging Trust (RLJ) just released third quarter and nine month results that show higher sales, higher reported revenue and a move to net income from a loss a year ago. Investors now have fresh numbers to reassess the stock.
The fresh earnings update lands after a powerful run in the share price, with a 63.92% year to date share price return and a 12.67% 90 day share price return. Total shareholder return over one year sits at 84.81%, suggesting recent momentum has been strong on the back of improving results.
Scan how RLJ Lodging Trust compares with a curated group of rebound candidates in our 39 high quality undervalued stocks, which is built to highlight stronger balance sheets and solid cash generation potential.
RLJ Lodging Trust now has improving profitability and a powerful recent share price run on the table. The next step is simple. Are investors paying a fair price for that progress or stretching too far?
Most Popular Narrative: 4% Overvalued
RLJ Lodging Trust last closed at $12.54, a touch above the most followed fair value estimate of $12.00 that applies a 10.45% discount rate to the narrative cash flow and earnings assumptions. That small gap puts more weight on whether the underlying business drivers actually play out as outlined.
Management’s focus on growing higher margin non room revenues through food and beverage concepts, reuse of underutilized space and expanded markets has already led total revenue to perform better than RevPAR. Combined with a lean operating model, this can support hotel EBITDA margins and free cash flow.
See why 3 investors see RLJ Lodging Trust as 4% overvalued.
Result: Fair Value of $12.00 (OVERVALUED)
Still, a heavier tilt to urban events and sizeable renovation spend means RLJ Lodging Trust could see earnings swing if travel patterns or project returns disappoint.
Find out about the key risks to this RLJ Lodging Trust narrative.
Another View: Market Pricing Versus Cash Flow For RLJ Lodging Trust
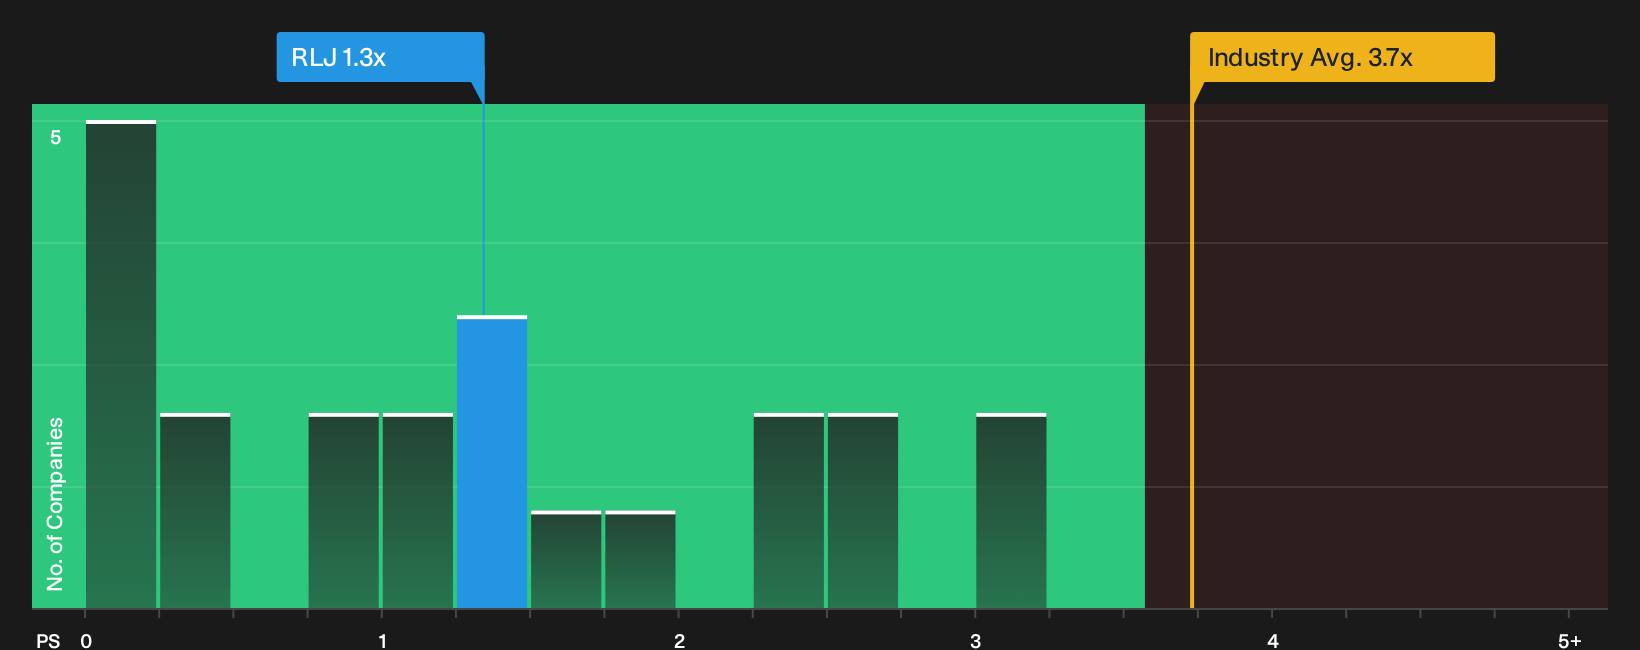
The earlier narrative pegged RLJ Lodging Trust as about 4% overvalued at $12.54 against a $12.00 fair value line. Yet on a simple P/S basis, the picture flips. RLJ trades around 1.3x sales versus a fair ratio of 1.9x and a 3.8x industry average, which points to a meaningful valuation gap that some investors might see as room for repricing.
That split between a richer narrative fair value and a cheaper sales multiple raises a practical question. Which signal would you lean on when market sentiment swings next: the story or the ratio, and how much mismatch are you comfortable holding through See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Momentum and mixed signals can blur the picture fast. Pull up the data, weigh both sides, and stress test your own thesis against the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond RLJ Lodging Trust?
You have fresh context on RLJ Lodging Trust, so do not stop there when you can scan other opportunities that might fit your goals just as well.
- Target resilience first and review 29 resilient stocks with low risk scores to help steady your portfolio when volatility picks up.
- Hunt for mispriced quality and scan the 19 high quality undiscovered gems before other investors catch on and narrow the opportunity set.
- Prioritise balance sheet strength and filter through the list of solid balance sheet and fundamentals (24 results) so you are not caught holding fragile businesses when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com