


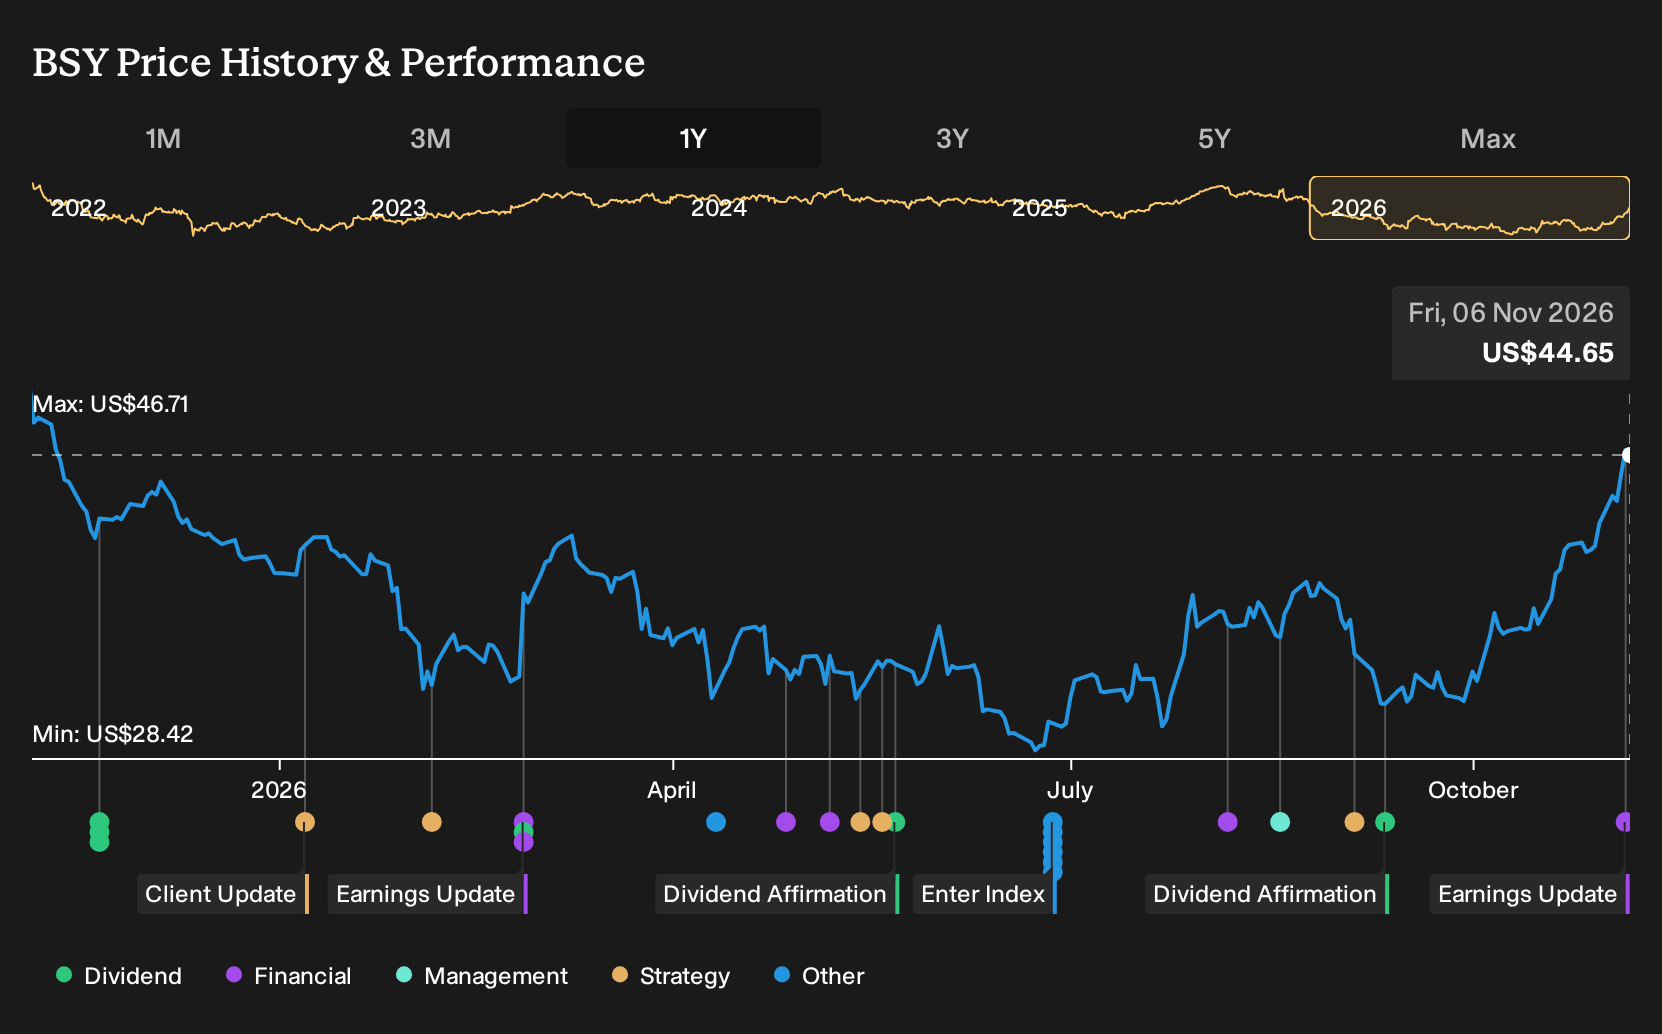
- Bentley Systems reported Q3 2026 revenue of US$421.51 million and net income of US$89.93 million, with basic and diluted EPS from continuing operations of US$0.29, and raised its annual recurring revenue growth outlook after completing the Cohesive divestiture and Eliis acquisition.
- The combination of stronger recurring software metrics, high retention rates and a tighter focus on core infrastructure and asset analytics indicates that Bentley Systems is reshaping its business mix toward subscription heavy, infrastructure centric software economics.
- This article examines how Bentley Systems' raised ARR guidance, supported by infrastructure demand, affects the longer term investment narrative.
Compare Bentley Systems' subscription heavy infrastructure focus with a curated set of peers by scanning 52 AI infrastructure stocks, which could be riding similar demand for data rich engineering software.
Bentley Systems Investment Narrative Recap
For a shareholder in Bentley Systems, the big picture is simple. You need to believe that high recurring software usage in infrastructure and asset analytics can keep compounding, and that AI assisted design becomes a meaningful layer on top. The raised ARR outlook and strong Q3 earnings support that operating thesis without radically changing it.
The near term swing factor stays the same. Execution on large Asset Analytics deals and E365 renewals needs to line up with the upgraded ARR targets. The key risk is that contract timing or sector softness in Resources and grid projects affects the pace of subscription growth against those higher expectations.
The most relevant recent move for this story is Bentley Systems lifting its 2026 constant currency ARR growth guidance to 12.5% to 13.5%. That increase leans on solid Q3 software metrics, high net revenue retention around 110%, and account retention of 99%, which together underline how much of the model is tied to sticky customers.
That updated outlook now sits alongside the Cohesive divestiture and the Eliis acquisition, which push the mix further into infrastructure centric and subsurface modeling software. For catalysts, it keeps attention on whether Asset Analytics consumption and early AI workflows can build on this higher ARR base, while any lumpiness in large contracts remains the main operational risk.
Bentley Systems' current analyst narrative points to revenues of US$2.2b and earnings of US$515.1 million by 2029. That profile is built on 11.1% yearly revenue growth and an earnings increase of about US$225 million from US$290.0 million today.
Uncover why Bentley Systems' fair value is effectively aligned with its current price.
Exploring Other Perspectives
One bullish twist on Bentley Systems focuses on AI monetization as a potential accelerator. Before this Q3 beat, the most optimistic analysts were already penciling in earnings of about US$601.3 million by 2029 on roughly 11.9% annual revenue growth. You can now compare that view with the new ARR guidance and decide which story feels closer to your own.
Explore 2 other Bentley Systems fair value estimates, including one that suggests as much as 21% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bentley Systems research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bentley Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bentley Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Bentley Systems?
Once you have a view on Bentley Systems, it can help to compare that thesis with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, scan a curated set of companies using the 39 high quality undervalued stocks.
- For investors who care most about resilience, stress test your portfolio ideas against a 29 resilient stocks with low risk scores that focuses on stability first.
- If you prefer to start with financial strength and then work backward to the story, filter candidates through a list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com