


- Amkor Technology reported third quarter 2026 sales of US$1,990.56m and net income of US$190.61m, with both basic and diluted EPS from continuing operations above the prior year period.
- The company paired this earnings strength with fourth quarter guidance and a completed US$32m buyback tranche, which together highlight management’s focus on capital returns while funding advanced packaging and capacity expansion.
- We will now look at how Amkor Technology's third quarter net income shapes the broader investment narrative around capacity and earnings.
Scan beyond Amkor Technology and compare its earnings and capital return profile with a curated group of 39 high quality undervalued stocks that also pair cash generation with disciplined balance sheets.
Amkor Technology Investment Narrative Recap
To own Amkor Technology, you need to believe its heavy investment in advanced packaging and global capacity eventually gets used efficiently. The third quarter showed solid earnings power while the firm is still in build out mode, which supports that case. The key near term swing factor remains how quickly AI data center and high performance programs convert into consistent factory loading.
The biggest operational risk has not changed. Large new facilities, especially in the U.S., could sit underutilized and weigh on margins if demand or customer ramps fall short. The latest earnings and guidance help frame the range of outcomes but do not materially change that core risk reward equation.
The most relevant update for that debate is Amkor Technology’s fourth quarter 2026 outlook. Management guided net sales to US$1.9b to US$2.0b and net income to US$160m to US$185m, or US$0.65 to US$0.75 per diluted share. That range gives you a cleaner view of earnings power while capex and footprint expansion are still running high.
For a shareholder, this guidance links directly to the main catalysts and worries. It shows how the business expects to convert AI, Computing and Automotive programs into near term profit, while still absorbing Communications softness and relocation of SiP capacity. In the context of sizeable capital commitments and a volatile share price, execution over the next few quarters will likely matter more than any modelled fair value revision.
Amkor Technology's current earnings of US$619.5m are set against analyst expectations for US$845.3m of earnings on US$10.2b of revenue by 2029, implying 11.2% yearly revenue growth and an earnings increase of about US$225.8m by that forecast year.
Uncover why Amkor Technology's fair value indicates a 101% potential upside to its current price, which could narrow quickly.
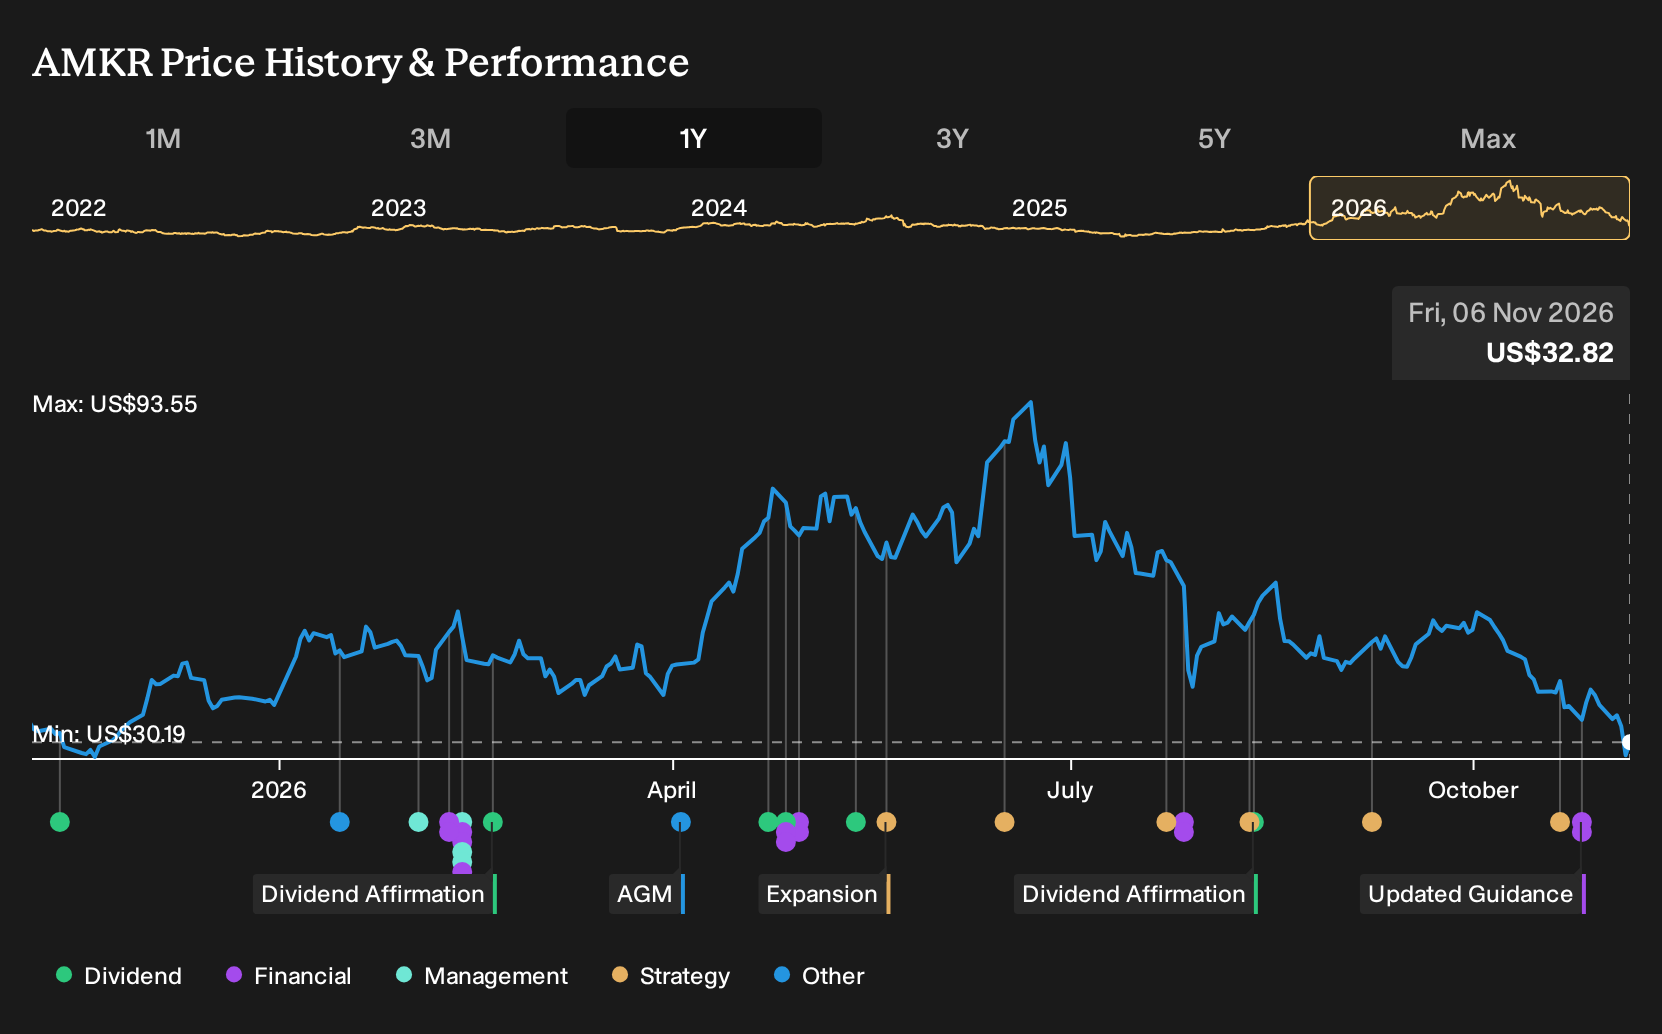
Exploring Other Perspectives
One alternative view puts Amkor Technology’s Arizona expansion front and center as a potential upside swing factor. Bullish analysts, working off pre-earnings assumptions, were modeling revenue of about US$10.9b and earnings of roughly US$1.3b by 2029, far above the consensus US$10.2b and US$845.3m. That more optimistic camp may now revisit those numbers, and readers can compare both narratives to decide which appears closer to their own expectations.
Explore 5 other Amkor Technology fair value estimates, including one that suggests there could be as much as 180% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Amkor Technology research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amkor Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amkor Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Amkor Technology?
If you want to stress test your view on Amkor Technology, it can help to line it up against other opportunities with clear financial profiles and different risk and reward setups.
- For investors who care most about quality at a reasonable price, scan a curated 39 high quality undervalued stocks that combine solid fundamentals with prices that may still be catching up.
- If capital preservation ranks high on your checklist, filter for 29 resilient stocks with low risk scores that pair steadier risk scores with more resilient balance sheets.
- Those hunting for stronger financial footing can start with a list of solid balance sheet and fundamentals (24 results) and use it as a shortlist for deeper research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com