


McDonald's (MCD) is back in focus after its third quarter 2026 report showed higher revenue, earnings and earnings per share, along with new plans for value menus, digital offers and AI driven efficiency gains.
After a sharp post earnings rally, McDonald's share price is still down 8.8% year to date. The 1 year total shareholder return of 5.4% in decline contrasts with a 5 year total shareholder return of 23.9%, suggesting long term holders have fared better than recent buyers.
Scan how McDonald's compares on quality and value factors alongside a curated group of resilient consumer stocks using the 29 resilient stocks with low risk scores.
For McDonald's, a 6.6% earnings pop and a share price still down for the year create a simple tension. Are investors re-rating the business, or are they just swinging back from overly gloomy sentiment as the valuation resets?
Most Popular Narrative: 18% Overvalued
Compared with McDonald's last close at $276.52, the narrative fair value of $233.67 implies a meaningful valuation gap that leans cautious on the current share price.
In summary, this narrative forecasts that McDonald's will expand its margins through increased efficiency in its operations (possibly with the aid of AI) but will also experience slower revenue growth, potentially below the economy's growth rate, given the maturity of the business and a decrease in consumer spending.
See why 62 investors see McDonald's as 18% overvalued.
Result: Fair Value of $233.67 (OVERVALUED)
Still, two pressure points could flip that McDonald's valuation story. A deeper pullback in consumer spending or structurally higher funding costs would challenge the fair value assumptions.
Find out about the key risks to this McDonald's narrative.
Another View On McDonald's Valuation
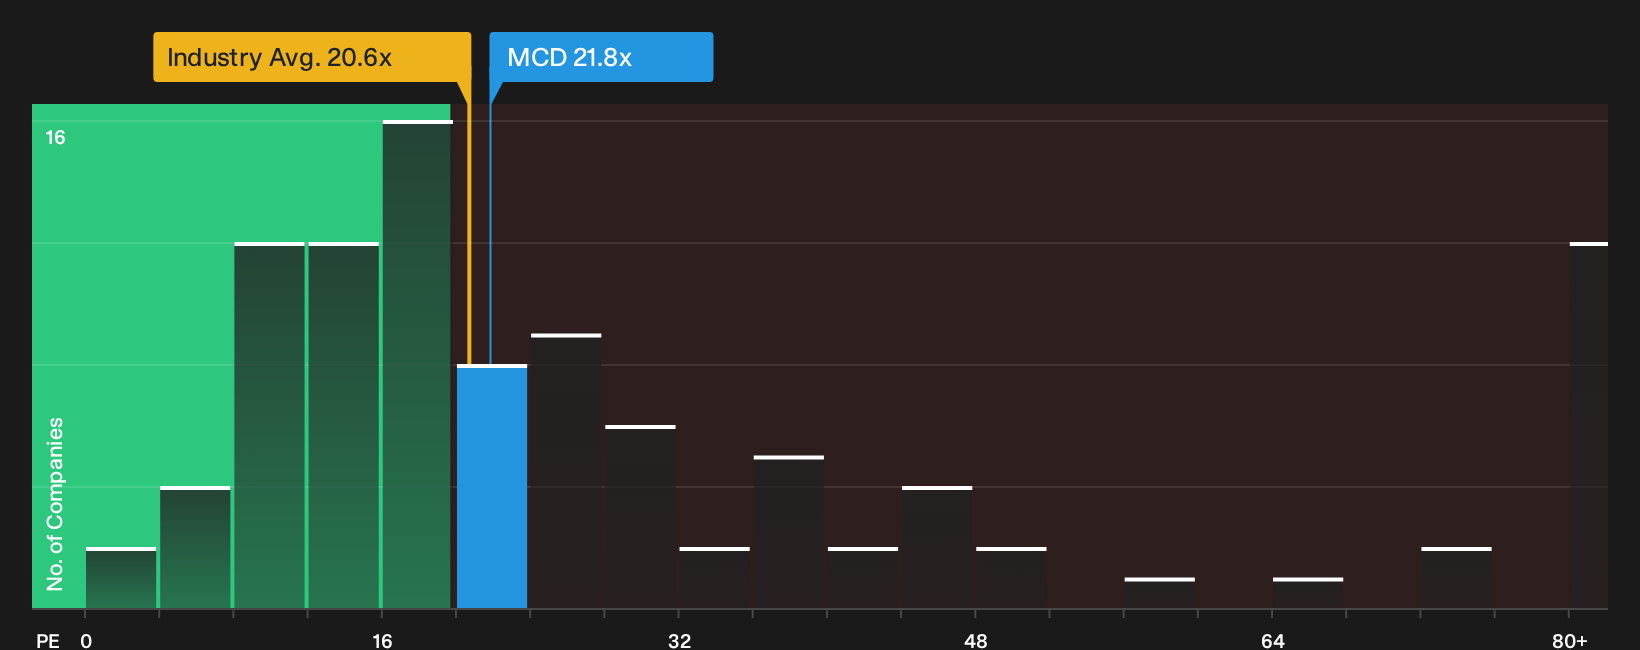
The narrative fair value pegs McDonald's at $233.67, which sits below the current $276.52 share price and leans cautious. Using a different lens, the current P/E of 21.8x is far lower than peers at 41.4x and below a fair ratio of 27.9x, which signals less valuation risk than the overvalued label suggests.
That gap between a cautious narrative price and a relatively modest earnings multiple leaves a simple question for investors: Is the crowd overestimating long term earnings pressure, or is the P/E discount already doing some of that work for you See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on McDonald's valuation story so far. Act while the data and sentiment are fresh, and weigh both sides by reviewing the full 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond McDonald's?
If you stop with McDonald's, you risk missing other opportunities. Let fresh ideas challenge your watchlist and sharpen how you think about risk and reward.
- Target resilient potential by reviewing companies that appear both sturdy and financially disciplined through the list of solid balance sheet and fundamentals (24 results).
- Hunt for possible mispriced opportunities by scanning the 19 high quality undiscovered gems that combine strong fundamentals with lower market attention.
- Strengthen your income playbook by assessing high yield opportunities that may offer durable payouts using the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com