


How the latest earnings and guidance reset the Alarm.com story
Alarm.com Holdings (ALRM) just turned in a quarter that topped market expectations and raised its full year outlook, while also folding in the CellGate acquisition to deepen its SaaS footprint.
The third quarter print put revenue at US$279.44 million, ahead of forecasts and above the US$256.40 million figure reported a year earlier. Adjusted earnings per share also came in stronger than analysts had pencilled in.
Headline net income for the period was US$34.44 million compared with US$35.34 million a year ago. The beat investors focused on therefore came from better than expected adjusted profitability rather than a jump in bottom line profit.
Investors have already reacted to this reset in expectations. Alarm.com Holdings shares are up 18.93% on a 1 month share price return and 26.91% on a year to date share price return, feeding into a 30.43% 1 year total shareholder return even though the 5 year total shareholder return is down 24.23%. This hints that momentum has recently picked up after a weak longer stretch as the market reassesses the risk and reward trade off around SaaS growth, guidance and acquisitions like CellGate.
Spot 19 high quality undiscovered gems that, like Alarm.com Holdings after this earnings beat and guidance lift, could be quietly resetting expectations before the wider market catches on.Alarm.com Holdings now trades almost exactly on the average analyst target, while some intrinsic value estimates sit materially higher. Is the recent rerating already enough, or is the gap still too wide to ignore?
Most Popular Narrative: 3% Overvalued
Alarm.com Holdings last closed at $65.03, slightly above the narrative fair value of $63 that applies a 9.16% discount rate, so the current price leans ahead of that central estimate without moving far away from it.
The analysts have a consensus price target of $63.0 for Alarm.com Holdings based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $85.0, and the most bearish reporting a price target of just $40.0.
See why 2 investors see Alarm.com Holdings as 3% overvalued.
Result: Fair Value of $63 (OVERVALUED)
Still, tariff related pressure on hardware and slower account or billings growth could weaken Alarm.com Holdings recurring SaaS engine and unsettle that fair value story.
Find out about the key risks to this Alarm.com Holdings narrative.
Another View: Alarm.com valuation through the earnings lens
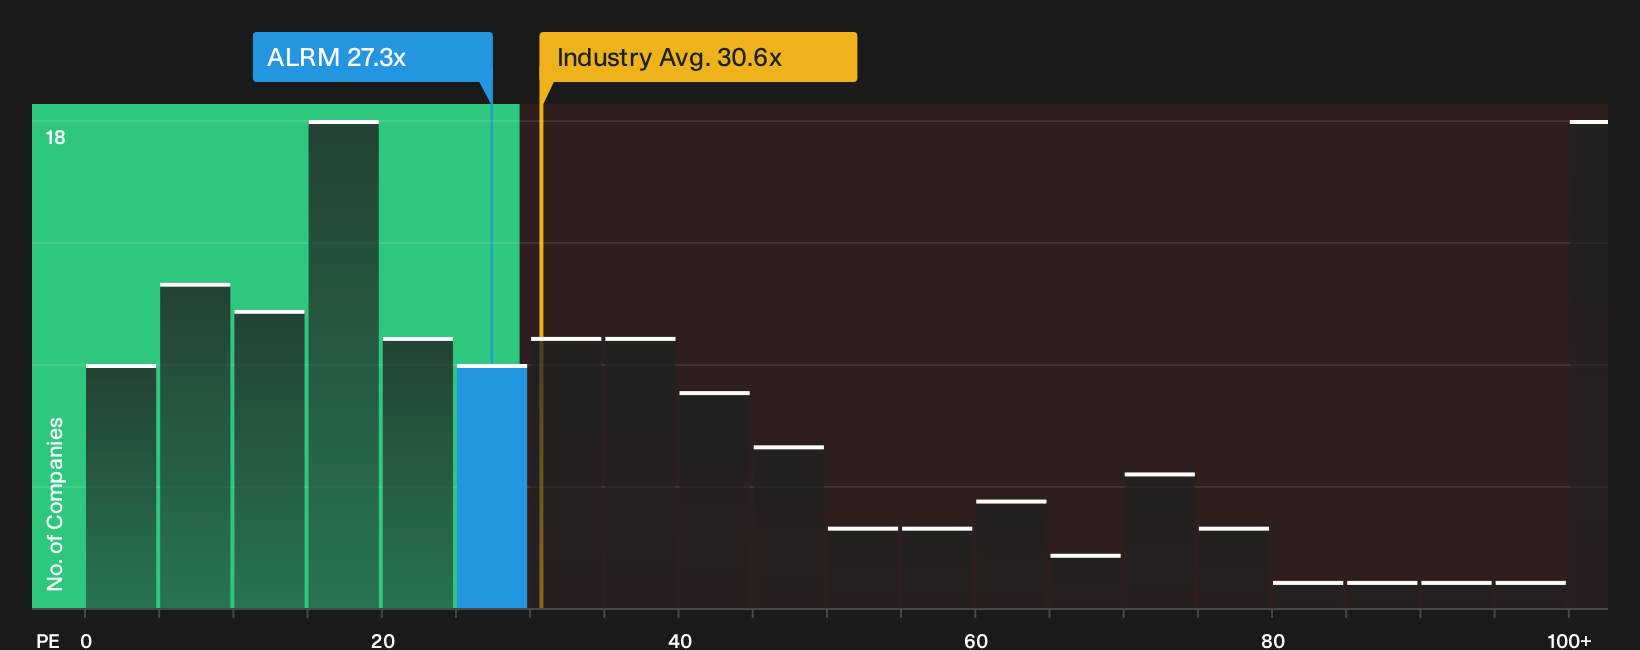
On one hand, the narrative model pegs Alarm.com Holdings as slightly overvalued at $65.03 against a $63 fair value. On the other, the P/E tells a different story. The stock trades on 27.3x earnings versus a 50.7x peer average and 30.2x for the wider US Software group, yet the fair ratio sits lower at 23.3x.
So investors are left with a split screen: a market that prices Alarm.com below many peers on earnings, but still above its own fair ratio, which raises a simple question for you. Does that gap look more like valuation risk if sentiment cools, or a price you are comfortable paying for the business you see today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on value and risk often create the most interesting setups, so move quickly, review the data, and test Alarm.com Holdings against your own framework. To weigh both sides of the story in one place, start with our breakdown of 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Alarm.com Holdings?
Do not stop with a single ticker when a whole field of opportunities is sitting open in front of you. Give yourself options, test your thinking, and let the data show you which ideas deserve a spot on your watchlist.
- Target potential mispricing by scanning a curated pool of quality candidates through the 39 high quality undervalued stocks.
- Strengthen your focus on resilience by filtering for companies with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Balance return potential with smoother ride potential by running a focused search across the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com