


Politics just rewrote the script for U.S. domestic infrastructure and industrial reshoring stocks, and that shift now feeds directly into how you think about risk, regulation, and supply chains. A tougher line on governance, rising consumer cost pressures, and trade war flare ups create both pressure and possibility for companies tied to onshore manufacturing. This article walks through three stocks exposed to that story and explains why their setup may deserve a closer look.
The three stocks below are a small sample of what reshoring and domestic infrastructure exposure can look like in liquid, U.S. large caps. The full screen surfaced 34 more companies with equally detailed business stories that are not covered here.
If you want to go straight to the source and sort through those high quality candidates yourself, analyze and compare them using the U.S. Domestic Infrastructure & Industrial Re‑Shoring Stocks screener.
Advanced Drainage Systems (WMS)
Overview: Advanced Drainage Systems designs and manufactures plastic pipes and water management systems that handle stormwater and wastewater for U.S. infrastructure projects.
Market Cap: US$9.25b
Advanced Drainage Systems plugs directly into the reshoring and domestic infrastructure theme because its pipes and stormwater systems sit under the very roads, farms, and industrial sites that onshore production depends on. This positioning puts real-world water management at the center of this policy shift.
"Ongoing climate change and increasing frequency and severity of extreme weather events are driving up the necessity for advanced stormwater management and resilient drainage infrastructure, which can support long term volume growth for Advanced Drainage Systems and underpin revenue expansion."
The real swing factor is how one cost pressure interacts with that demand backdrop and either protects or squeezes future profitability.
That cost pressure is exactly what the full narrative for Advanced Drainage Systems unpacks, showing where input inflation, pricing power and policy could be quietly reshaping the investment case.
Minerals Technologies (MTX)
Overview: Minerals Technologies supplies mineral based products and environmental solutions that support U.S. construction, manufacturing, packaging, and infrastructure projects.
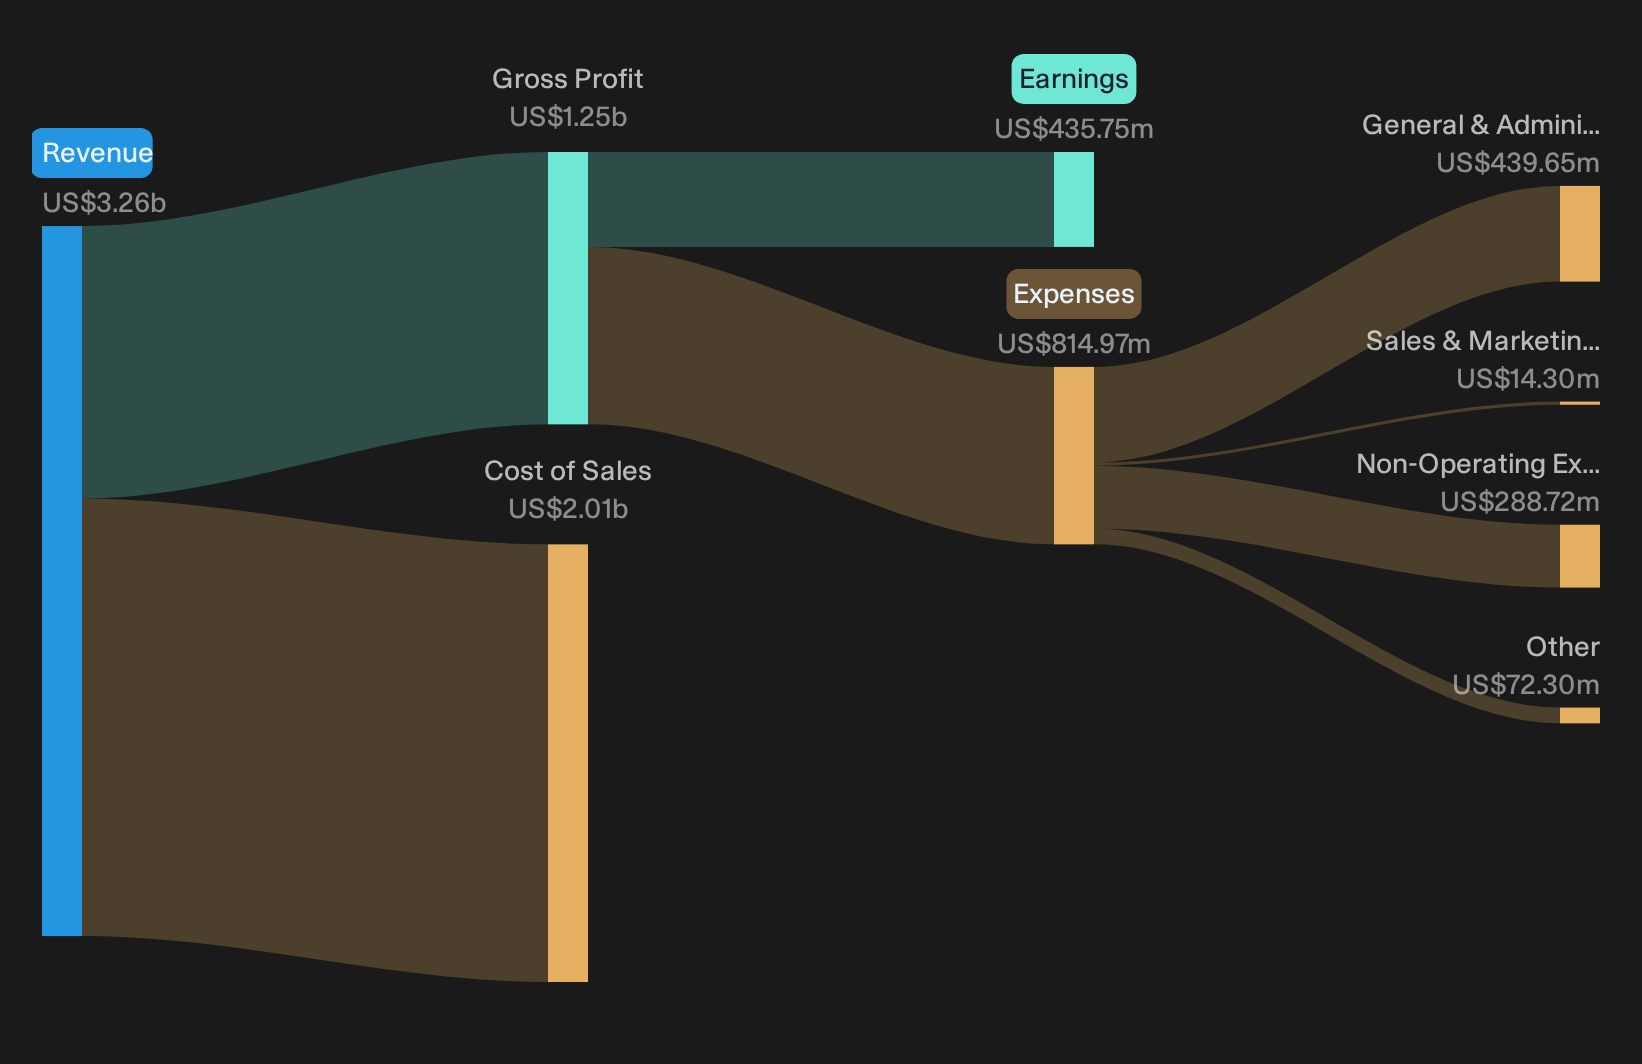
Operations: Minerals Technologies generates about US$1.1b from Consumer & Specialties and US$1.0b from Engineered Solutions, with significant U.S. revenue.
Market Cap: US$1.9b
Minerals Technologies (MTX) matters for this reshoring screen because its materials and infrastructure solutions connect directly to U.S. factories, foundries, and water systems that onshore production relies on.
"PFAS remediation solutions like FLUORO-SORB, already installed in about 10 municipal drinking water plants and specified in roughly 10 more, together with growing pilot activity in multiple regions, can expand Minerals Technologies’ addressable market and support higher environmental product revenue and operating income."
The key consideration for investors is how one unresolved cost and funding pressure interacts with that demand opportunity and influences future margins.
That margin question is exactly what the full narrative for Minerals Technologies unpacks, showing how PFAS remediation economics, funding mix and any hidden cost pressure could be accelerating or quietly masking the story.

Cardinal Infrastructure Group (CDNL)
Overview: Cardinal Infrastructure Group provides heavy civil contracting and site development across high growth southeastern U.S. markets tied to domestic infrastructure projects.
Operations: Cardinal Infrastructure Group generates about US$663 million from Heavy Construction, with all reported revenue currently coming from U.S. projects.
Market Cap: US$297 million
Cardinal Infrastructure Group is effectively a pure play on U.S. infrastructure and reshoring, since its crews build the roads, utilities, and industrial sites that domestic manufacturing needs to exist in the first place.
"Although record backlog of US$866 million and a larger mix of commercial and industrial projects offer multiyear revenue visibility, longer and less predictable deployment schedules in those projects compared with residential work can create crew underutilization periods like those seen in Charlotte, with potential ongoing effects on adjusted EBITDA."
What really matters now is how one quiet shift in project mix ultimately filters through to the earnings power investors are paying for.
That shift in mix is exactly what the full narrative for Cardinal Infrastructure Group unpacks. It reveals how backlog, execution risk and capital intensity could be decoupling Cardinal Infrastructure Group’s earnings power from headline revenue.

Curious About The Next Wave Of Opportunities
Fresh ideas move first. Breakout themes gain momentum while they are still under the radar for now. Do not get caught chasing. Act now and get in early.
- Spot potential breakouts earlier than the crowd by scanning curated small caps using the 9 elite penny stocks with strong financials.
- Ride the momentum of real businesses behind AI infrastructure by assessing the companies inside the 52 AI infrastructure stocks.
- Target resilient cash generators before they start flying by reviewing the curated list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com