


Albertsons Companies has seen its stock lose ground over the past few years, which now puts extra focus on a simple question for you as an investor: whether the current share price makes sense when set against its sales base.
- Over the past 5 years, the share price has fallen 44%, which puts extra weight on whether the revenue the supermarket group generates can still underpin today’s valuation.
- The recent US$900 million legal judgment in Washington State, along with possible appeal costs, may change how you think about the cash that Albertsons can retain from its sales to support its equity value.
- Your read on Albertsons Companies is one view; the desks covering it have another. See what analysts think Albertsons Companies's shares could be worth.
The issue now is whether Albertsons Companies' current market value is adequately supported by its sales when you look at the stock’s recent performance and these developments.
If you want a second reference point alongside Albertsons Companies and this legal overhang, a focused screen of 29 resilient stocks with low risk scores can help you find other lower risk ideas to research next.
Does Albertsons Companies Look Undervalued on Sales?
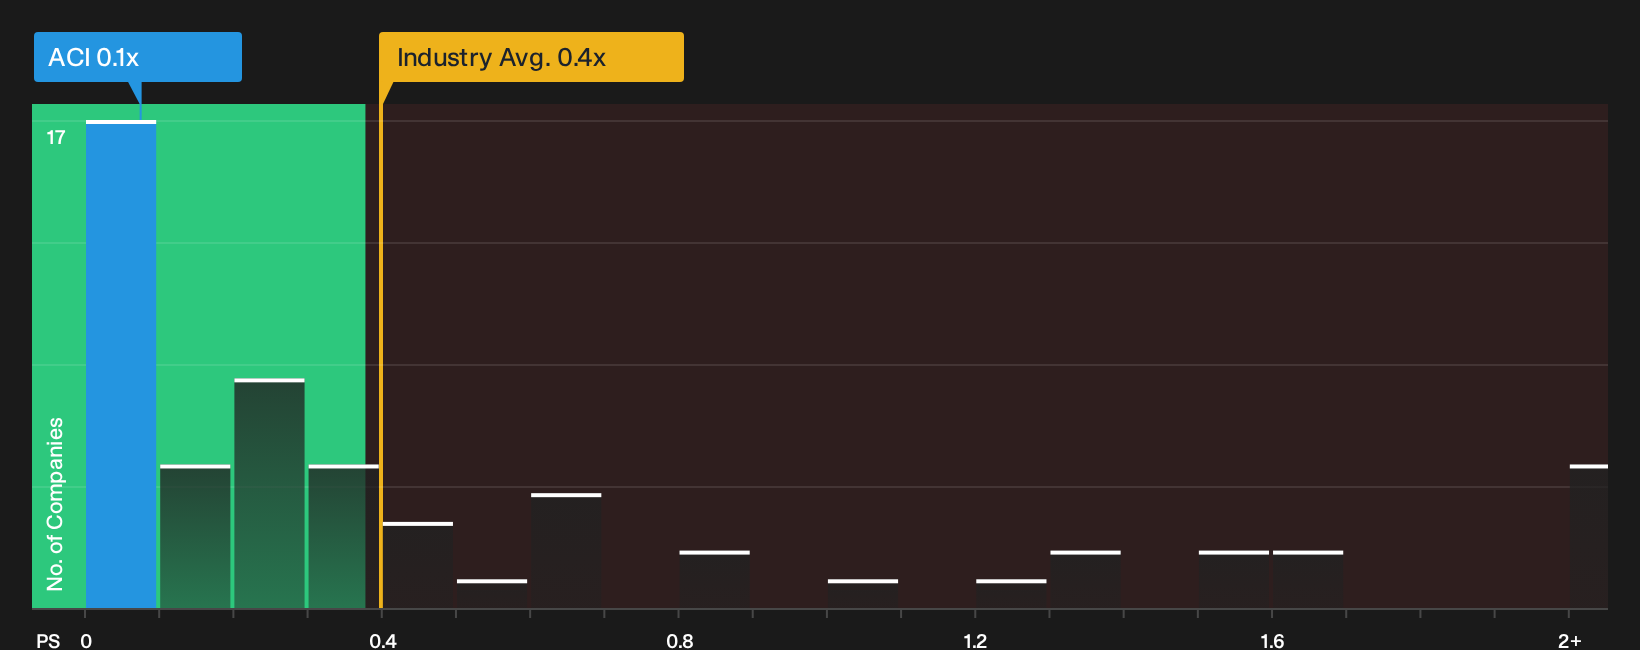
The P/S ratio suits Albertsons Companies because grocery chains are often judged on what investors pay for each dollar of store and online sales. On that score, the stock trades on a P/S multiple of about 0.1x, which is far below the wider Consumer Retailing industry on roughly 0.4x and even further below a peer group average of about 1.4x.
Because the recent US$900 million Washington State opioid judgment raises questions about future cash available to shareholders, it is striking that the current P/S still screens as undervalued against a Fair Ratio that already factors in the group’s risks and business profile. The gap suggests the market is pricing Albertsons with a heavy discount to the level implied by its revenue base and that investors are assigning a low value to each dollar of supermarket sales, relative to both sector norms and the tailored Fair Ratio model. Explore the numbers behind Albertsons Companies's P/S valuation.
The Albertsons Companies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Albertsons Companies' stock pick up where this valuation puzzle leaves off by explaining which combinations of future sales trends, profitability, and earnings power would need to hold for the shares to be worth materially more or less than today’s price, and by setting these out on the Community page. Rather than a single headline multiple or model result, each narrative lays out its underlying assumptions so you can compare them with reported numbers as they arrive.
Bulls and bears on Albertsons Companies are reading the same playbook on digital, costs and loyalty, then drawing very different conclusions.
Bull case: 9% undervalued
"Growth in loyalty and retail media, with more than 51 million loyalty members who spend several times more than non members, is turning Albertsons Companies data and traffic into higher margin revenue streams..."
Discover why this Narrative puts Albertsons Companies at 9% undervalued.
Bear case: 28% overvalued
"The ACI Edge restructuring and centralization are intended to deliver about US$200m of run rate savings by fiscal 2027, but the concurrent leadership uncertainty, including the announced CFO retirement and external questions around the CEO, increases execution risk..."
Explore why this Narrative puts Albertsons Companies at 28% overvalued.
One more Albertsons Companies puzzle that sits beyond the numbers
Valuation frames what you pay, but the people steering Albertsons Companies and the way their rewards line up with your outcomes can reshape the whole risk and return story. See who runs Albertsons Companies and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com