


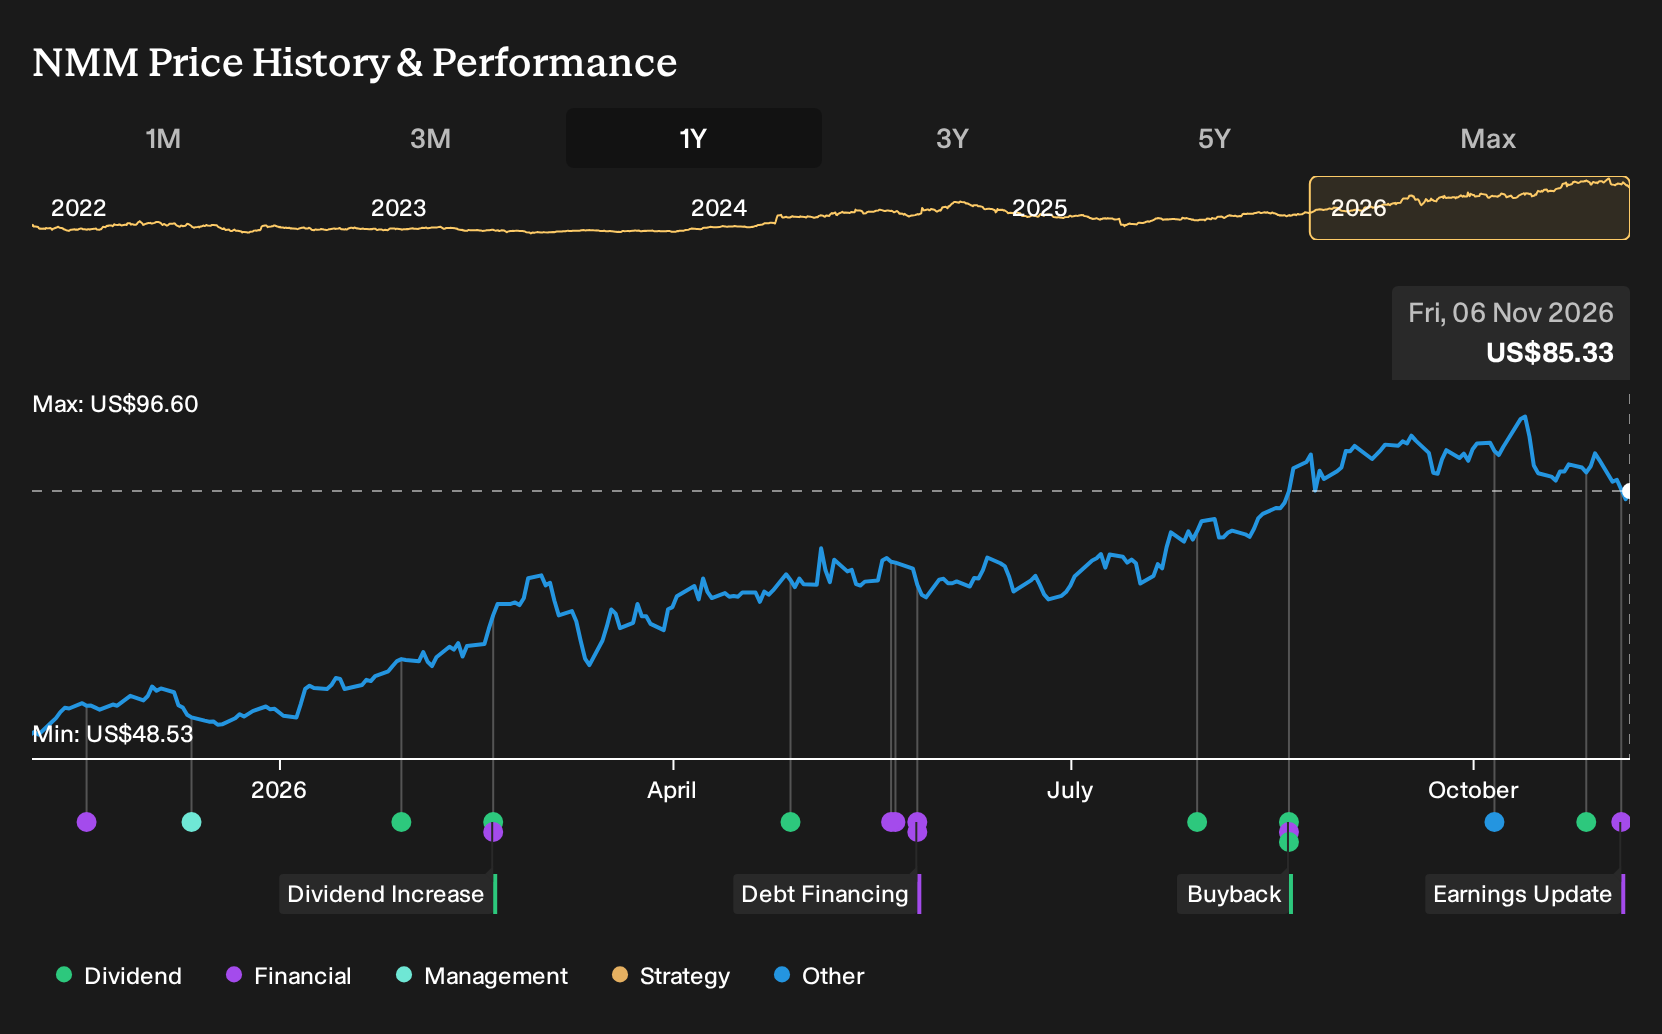
- Navios Maritime Partners reported Q3 2026 sales of US$431.96 million and net income of US$185.66 million, with basic and diluted earnings per unit from continuing operations of US$6.42, and for the first nine months sales of US$1.19914b and net income of US$459.92 million with earnings of US$15.83 per unit.
- The partnership paired this strong earnings release with a quarterly cash distribution of US$0.06 per unit and continues to highlight a contracted revenue backlog of about US$4.4b and an ongoing fleet renewal plan that aims to keep vessels younger and more fuel efficient than much of the global fleet.
- We will now look at how Navios Maritime Partners' investment narrative may shift in light of this strong Q3 net income performance.
Compare Navios Maritime Partners' earnings story with a hand picked group of shipping and infrastructure players by scanning the list of solid balance sheet and fundamentals (24 results), which may complement this kind of contracted cash flow profile.
Navios Maritime Partners Investment Narrative Recap
To own Navios Maritime Partners, you need to be comfortable with a shipping business that leans heavily on a large, contracted backlog and a younger, fuel efficient fleet, while carrying meaningful debt and newbuilding commitments. The Q3 2026 earnings print, with US$185.66 million in quarterly net income, reinforces that the current operating setup can support this model.
The immediate swing factor remains execution on the 29 vessel pipeline and associated US$290 million to US$329 million of remaining equity needs. Strong nine month net income of US$459.92 million helps the story, but it does not remove the risk that softer charter markets or higher funding costs could make that build out more demanding on liquidity.
The most directly relevant announcement for this earnings beat is the reaffirmed quarterly cash distribution of US$0.06 per unit, or US$0.24 annualized, payable on 12 November 2026. Navios Maritime Partners is effectively signaling that even after a very profitable period, it is keeping regular cash returns small relative to earnings and contracted revenue.
For you as a unitholder, that decision keeps more cash inside the partnership to support fleet renewal, potential unit repurchases and debt service at a time when analysts expect earnings to drift lower over the next three years. It also underscores that the main catalyst and risk both still sit with how efficiently management turns the current earnings power and US$4.4b backlog into balance sheet strength while funding the remaining vessel program.
Navios Maritime Partners' current analyst narrative points to revenue of US$1.7b and earnings of US$595.1 million by 2029, based on an assumed 3.8% yearly revenue growth rate and a move in earnings from US$447.9 million today to that US$595.1 million level. This represents an increase of about US$147 million.
Discover why Navios Maritime Partners' fair value indicates a 21% potential upside to its current price, which could close sooner than many investors expect.
Exploring Other Perspectives
The Simply Wall St Community only shows two fair value views for Navios Maritime Partners, ranging from US$103 to about US$445.60 per unit, so opinions already span more than a fourfold gap. When you consider this alongside the sizeable newbuilding program and funding needs, it becomes clear why different investors can reach sharply different conclusions. Explore those contrasting viewpoints before forming your own stance.
Explore another Navios Maritime Partners fair value estimate, including one that suggests as much as 422% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Navios Maritime Partners research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Navios Maritime Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Navios Maritime Partners' overall financial health at a glance.
Looking For More Investment Ideas Beyond Navios Maritime Partners?
If the Navios Maritime Partners story has sharpened your focus on balance sheets, cash generation and capital allocation, it can be useful to line it up against other opportunities that share some of those qualities. The Simply Wall St Screener lets you filter for different combinations of financial strength, income potential and growth characteristics so you can build a watchlist that actually matches your own approach rather than someone else's model portfolio.
- For investors who care most about resilient businesses and sleep at night risk levels, start with a 29 resilient stocks with low risk scores that may help you focus on companies with more measured risk profiles.
- If the appeal is finding quality on sale, compare Navios Maritime Partners with a 39 high quality undervalued stocks that filters for stocks where fundamentals and current pricing appear out of sync.
- Income focused readers who want yield supported by balance sheet strength can scan a 8 dividend fortresses and look for payouts that are backed by cash flows rather than just headlines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com