


UL Solutions (ULS) just reported third quarter and year-to-date results that showed higher sales and net income, giving investors fresh numbers to assess the stock after a strong recent month.
Recent news around UL Solutions, including the Ho Chi Minh City lab expansion and new high wind testing services, has arrived alongside a 30 day share price return of 17.16% and a 7 day gain of 5.20%. However, the 1 year total shareholder return is still down 7.57%, which suggests that recent momentum has improved even as longer term holders remain under water.
Spot other testing and compliance specialists that analysts consider potential breakouts by scanning our curated list of 19 high quality undiscovered gems, which is aligned with UL Solutions' latest momentum and contract wins.After a sharp rebound and new contract wins, UL Solutions now asks a straightforward question of prospective investors: Does the current valuation still offer an appealing trade off between potential upside and the risk of a pullback from here?
Most Popular Narrative: 19% Undervalued
On the most followed valuation view, UL Solutions trades below an implied fair value of $96.57, compared with a last close of $78.65. This puts the current debate on whether recent strength already reflects its key business drivers.
Expanded lab capacity in areas such as high voltage EMC, large scale fire testing, energy storage and HVACR, following the increase in 2026 capex guidance to about 8.5% of revenue, is aimed at serving rising testing volumes. This could support revenue growth and asset driven margin improvement as utilization increases. Strong demand for certification testing tied to AI data center equipment, energy transition projects and broader product innovation, with recent double digit revenue growth in this service line, points to a growing pipeline of programs that can add to future revenue and support net margin through a higher mix of complex work.
See why 5 investors see UL Solutions as 19% undervalued.
Result: Fair Value of $96.57 (UNDERVALUED)
Still, the UL Solutions story can change quickly if Risk and Compliance Software weakness persists or if acquisition integration costs continue to run above initial expectations.
Find out about the key risks to this UL Solutions narrative.
Another View: UL Solutions On Earnings Multiples
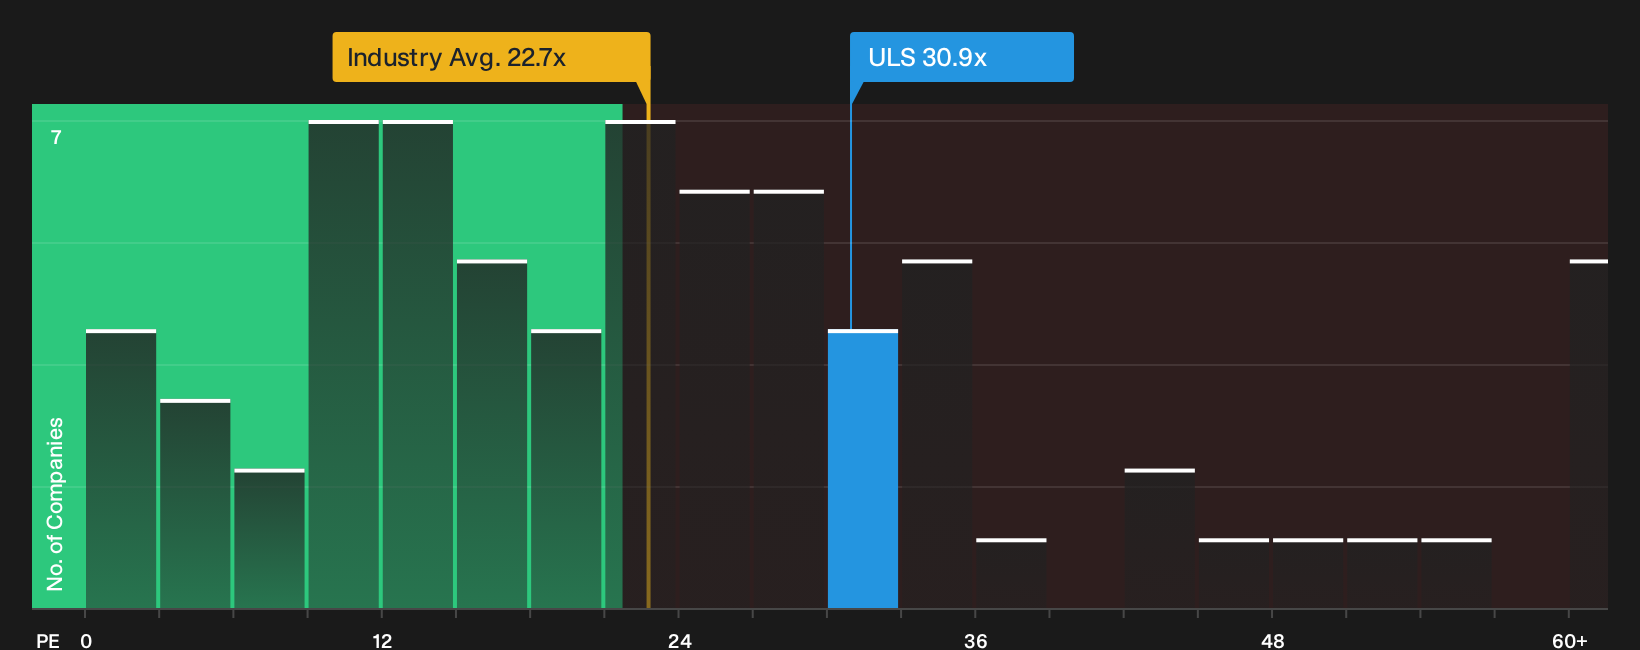
The first narrative presents UL Solutions as undervalued relative to a $96.57 fair value. A different perspective suggests a tougher story. On about 30.9x P/E, the shares trade above the US Professional Services group at 22.9x and above an estimated fair ratio of 18.6x. This points to valuation risk if sentiment cools.
The same premium also appears against direct peers on roughly 26.1x P/E. Investors weighing that 18.6x fair ratio need to decide whether UL Solutions has sufficient staying power in returns and profitability to keep justifying a richer valuation, or whether expectations have already stretched too far.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around UL Solutions is clear, with both caution and optimism in play, so move quickly, review the latest figures, and judge the trade off yourself by weighing its 2 key rewards and 2 important warning signs.
Looking for more UL Solutions style investment ideas?
If UL Solutions has sharpened your focus on quality and pricing power, do not stop here. Broaden your watchlist now with a few targeted screens that surface specific types of opportunities aligned with your risk appetite and income needs.
- Target resilient balance sheets and steady fundamentals by filtering for companies in the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities with strong quality checks by scanning the 39 high quality undervalued stocks before the crowd catches on.
- Build a cash-flow-focused portfolio by shortlisting income ideas from the 8 dividend fortresses while yields remain compelling.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com