


Vontier (VNT) is back in focus after third quarter results topped its own guidance, margins widened and management lifted full year earnings targets, a combination that often reshapes how investors view a stock.
That guidance upgrade has quickly flowed into the price. Vontier’s share price return is up 5.84% over the last day, 30.86% over 30 days and 11.72% year to date, while its 3-year total shareholder return of 31.84% points to momentum that has been building rather than fading.
Spot similar momentum stories by scanning a hand picked group of 39 high quality undervalued stocks that pair earnings strength with compressed expectations.After a jump like that, and with Vontier now trading slightly above the average analyst target yet below some intrinsic estimates, where does a reasonable view of fair value actually land?
Most Popular Narrative: 13% Overvalued
Against Vontier's last close at $42.23, the most followed narrative on Simply Wall St pegs fair value at $37.42, which frames the latest surge as moving ahead of that estimate rather than lagging behind it.
Bull
• Vontier has inherited a proven business system of disciplined capital allocation and continuous improvement from its former parent companies, Danaher and Fortive. u The spinoff from Fortive will allow Vontier to redeploy capital to its business, as its former parent invested less than 5% of its total M&A capital in Vontier.
See why 12 investors see Vontier as 13% overvalued.
According to julio, who built this valuation, that discipline and reinvestment potential still does not offset a fair value that sits about 13% below the current share price, using a 9% discount rate and assumptions for revenue growth and margins that are already reasonably supportive.
Result: Fair Value of $37.42 (OVERVALUED)
Still, Vontier’s story can change quickly if core revenue remains sluggish or if electric vehicle adoption eats into its retail fueling earnings pool.
Find out about the key risks to this Vontier narrative.
Another View: Multiples Paint A Cheaper Picture For Vontier
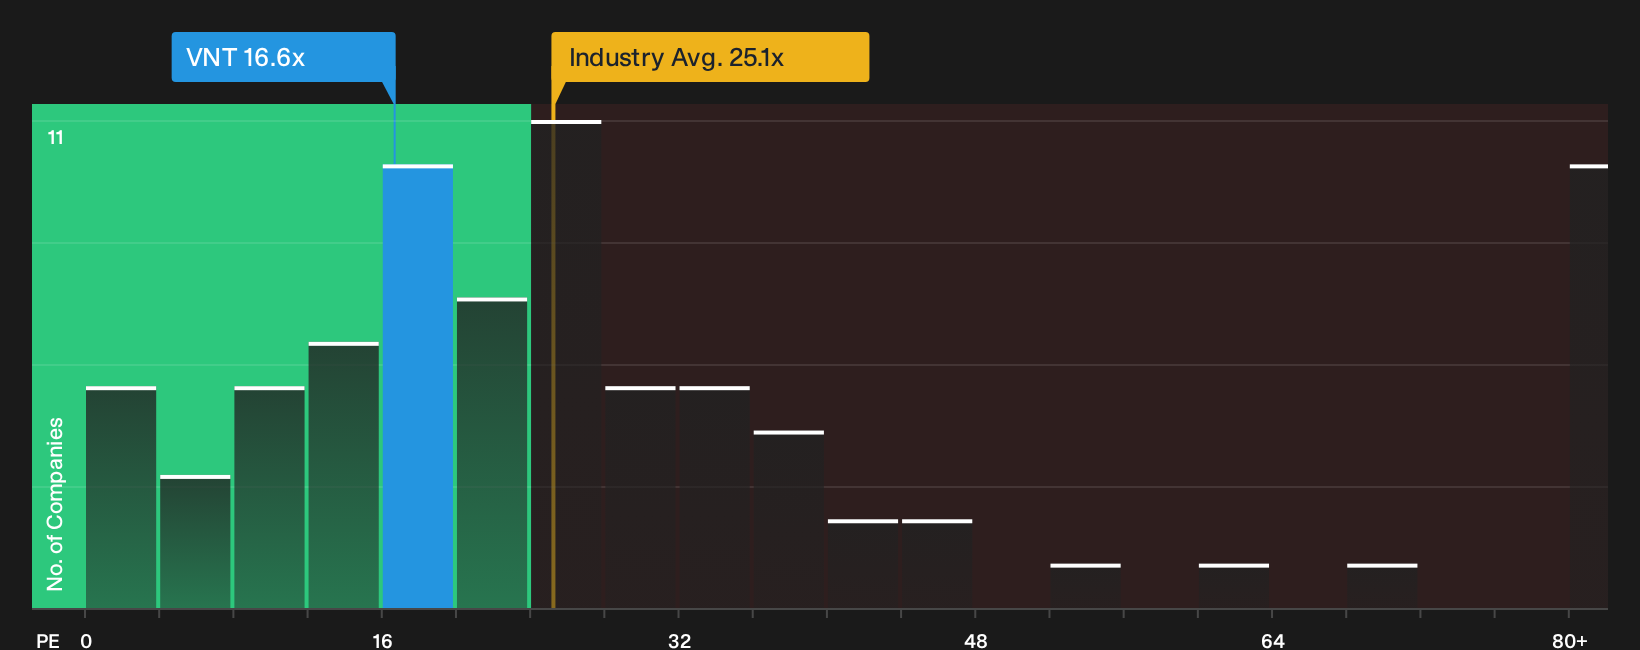
Vontier might look stretched against julio's $37.42 narrative fair value, but the market snapshot from earnings multiples tells a different story. At a P/E of 16.6x, the stock trades far below both the peer average of 70.6x and the US Electronic industry on 24.4x, and also below an estimated fair ratio of 23x.
That gap suggests investors are pricing in meaningful risk already, which reduces room for further derating but also raises questions about how much upside is left if results simply track expectations rather than surprise.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Vontier’s value and risk profile so far. If you want to move quickly and build your own view, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Vontier?
If Vontier’s mixed signals have you thinking about portfolio upgrades, use this momentum to scan wider opportunities before the next round of earnings resets the playing field.
- Target reliable cash engines by focusing on companies with resilient finances and low leverage through a list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities where quality and value intersect using a focused shortlist of 19 high quality undiscovered gems.
- Dial back volatility and protect your downside by concentrating on a curated 29 resilient stocks with low risk scores that keeps fragile balance sheets off your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com