


Hotter October payrolls, firmer wages and a rising chance of another Fed hike have pushed investors to rethink where they want exposure to higher rates and tighter money. That reset can punish long duration growth stocks; however, it can also shine a light on solid, dividend paying US companies with sturdier cash flows. This piece walks through three such stocks exposed to these labor market surprises and explains why they might deserve a closer look now.
The three stocks in the spotlight below are just a sample from this theme. The full screen surfaced 41 more US based value and dividend companies with equally compelling income stories that are not covered here. To identify and analyze the ones that best fit your risk tolerance and income goals, head straight into the US Domestic-Oriented Value and Dividend Stocks screener.
MSC Industrial Direct (MSM)
Overview: MSC Industrial Direct is a US based distributor that supplies metalworking and MRO products and services to industrial and public sector customers.
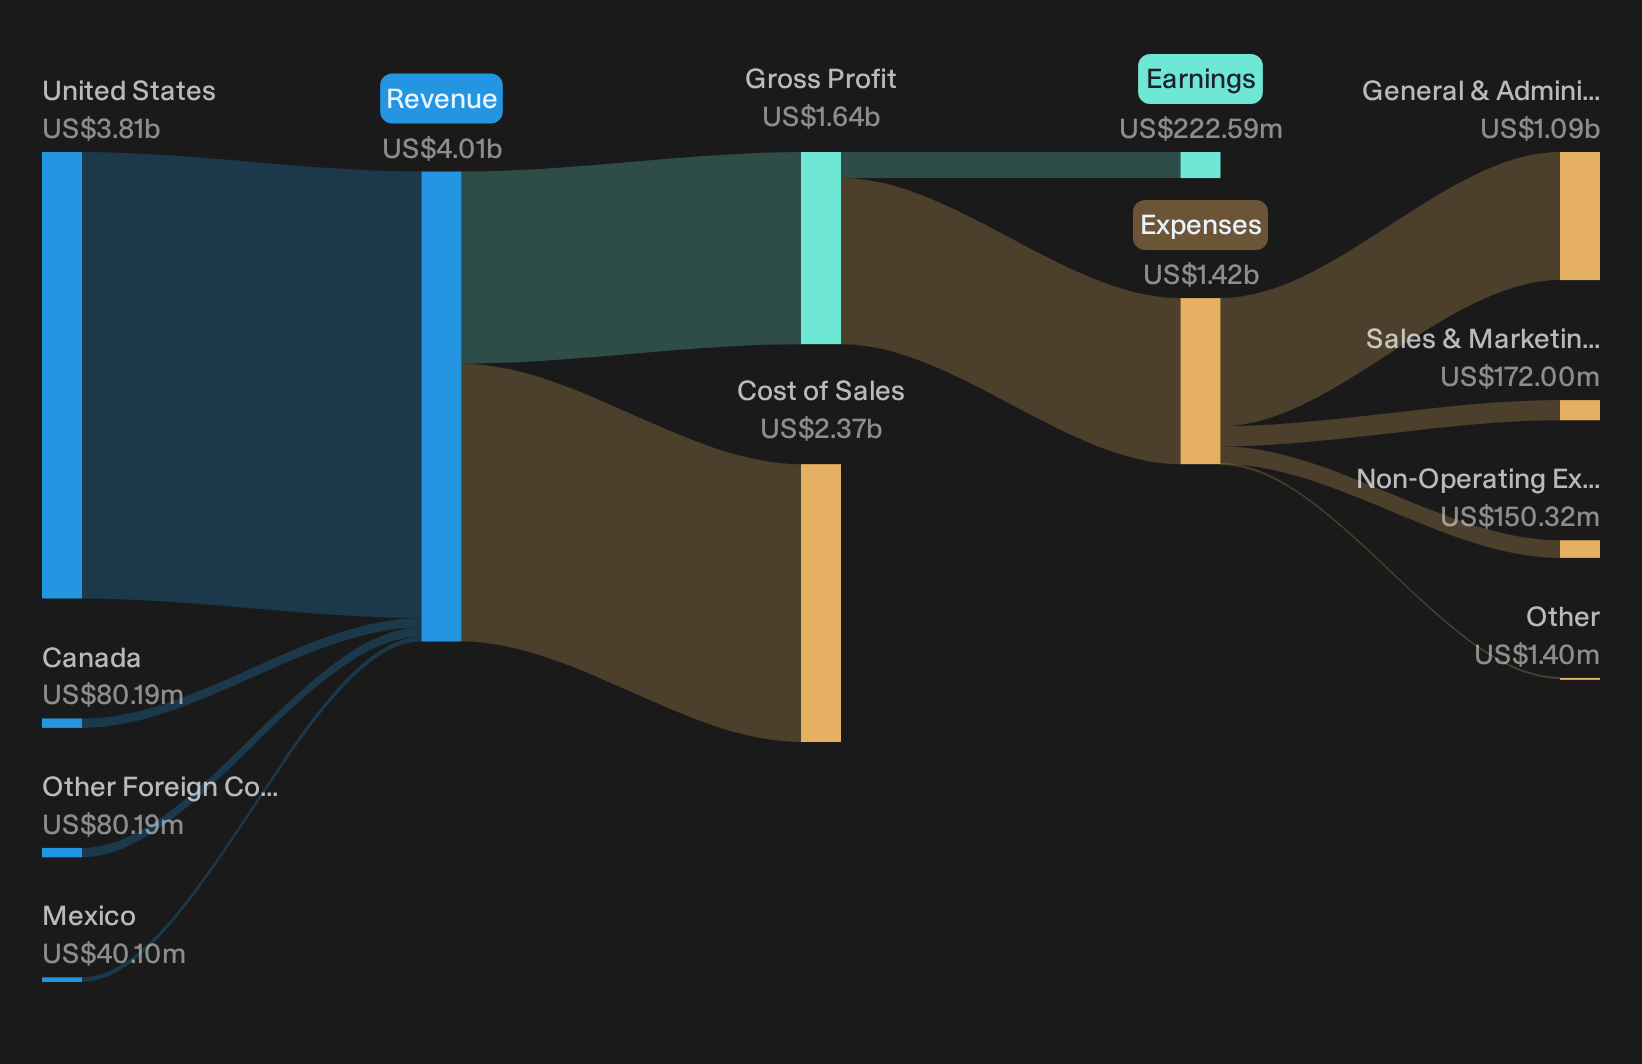
Operations: MSC Industrial Direct generates about US$4.0b in revenue as a distributor of metalworking and MRO products, largely from US customers.
Market Cap: US$6.2b
For a value and dividend screen built around solid US cash generators, MSC Industrial Direct offers a direct link to factory floors and employment driven maintenance spending. This is exactly where tighter money and stronger payrolls can intersect in a portfolio.
"The recent sales organization overhaul compressed volumes in fiscal 2Q and relies heavily on new relationship building across National Accounts and larger Core Customers."
The real swing factor for MSC Industrial Direct now is how one quiet shift in pricing discipline and cost control flows through future margins.
That margin story is where it gets interesting, and the full narrative for MSC Industrial Direct unpacks how pricing discipline, volumes and payroll sensitive demand could be quietly reshaping MSC Industrial Direct's earnings profile.
Union Pacific (UNP)
Overview: Union Pacific runs a large US freight railroad moving agricultural goods, energy products, industrial materials and consumer freight for domestic customers.
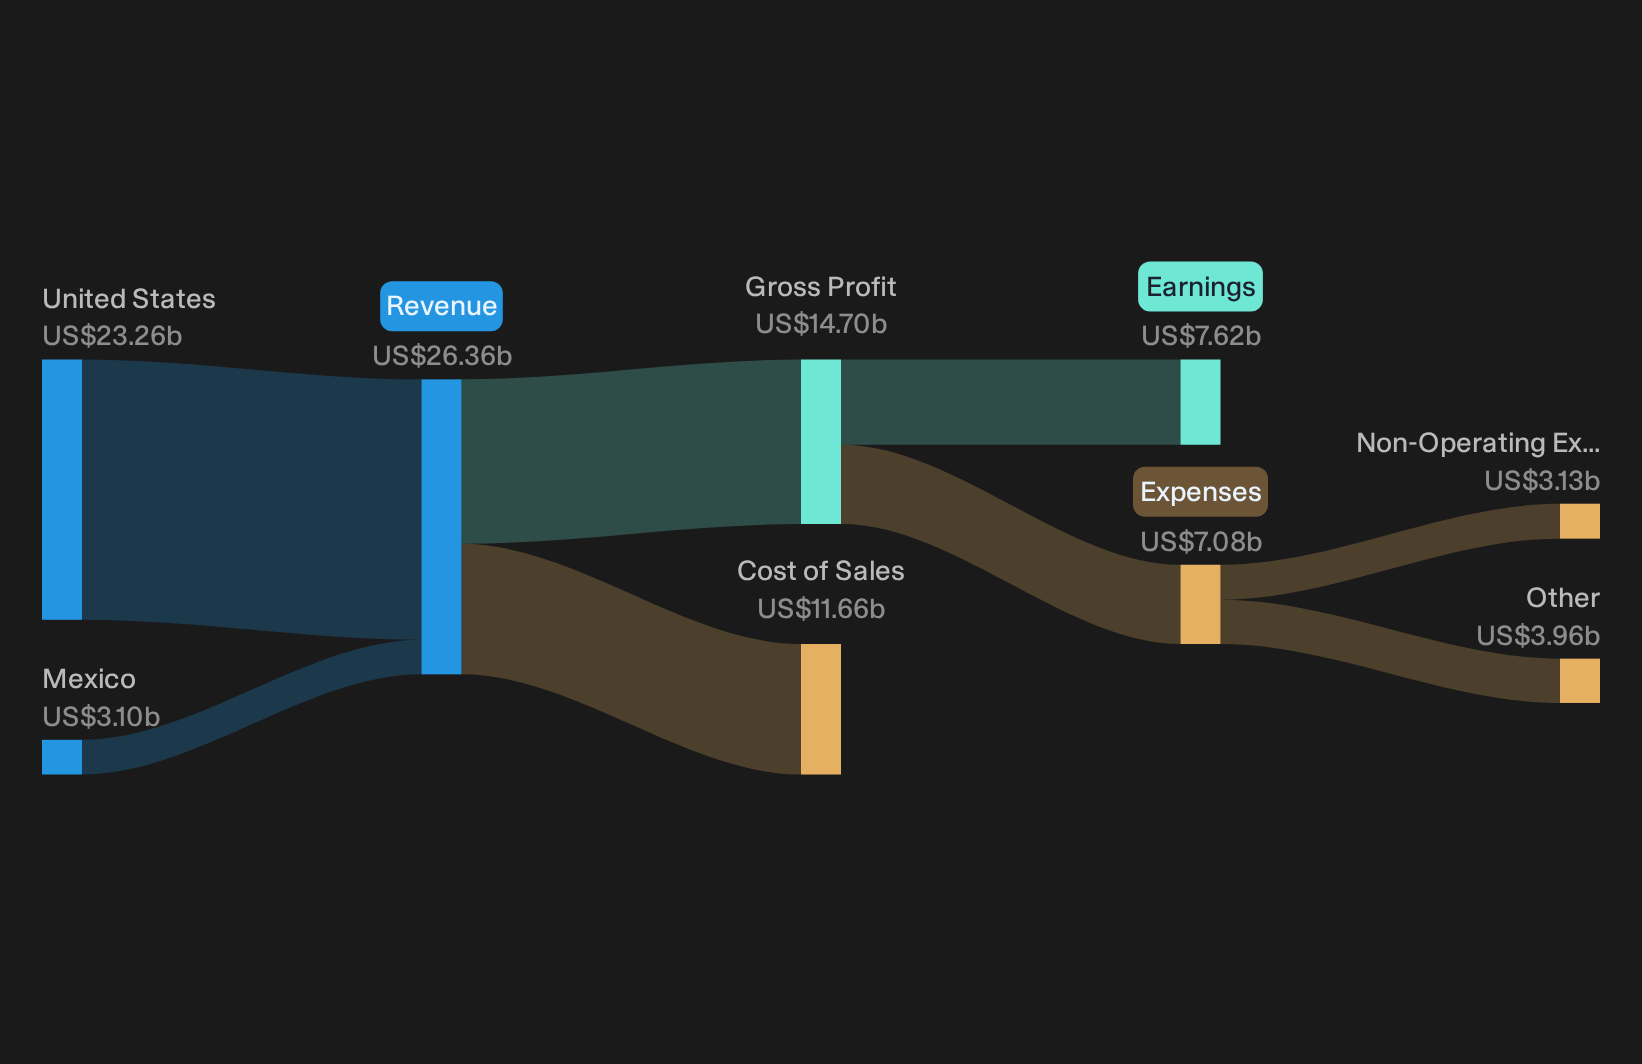
Operations: Union Pacific generates about US$26.4b in railroad revenue, with roughly US$23.3b from the United States and US$3.1b from Mexico.
Market Cap: US$177.1b
For an investor looking at US Domestic-Oriented Value and Dividend Stocks, Union Pacific ties income potential directly to freight demand in a labour and spending backdrop described as resilient, with its rail network providing exposure to how goods move across the country.
"Domestic intermodal remains a key focus, with four consecutive record quarters in both volume and revenue and expectations for a fifth, and continued truck to rail conversion campaigns that could extend volume growth and support freight revenue and earnings."
What matters next is how one unresolved pressure on Union Pacific's cost base interacts with that freight strength to shape future margins.
That margin tension is exactly why the full narrative for Union Pacific digs into where Union Pacific’s efficiency push could accelerate and which cost pressures might quietly be easing.
Hubbell (HUBB)
Overview: Hubbell manufactures electrical and utility equipment that keeps power grids, data centers, and industrial facilities running for US and global customers.
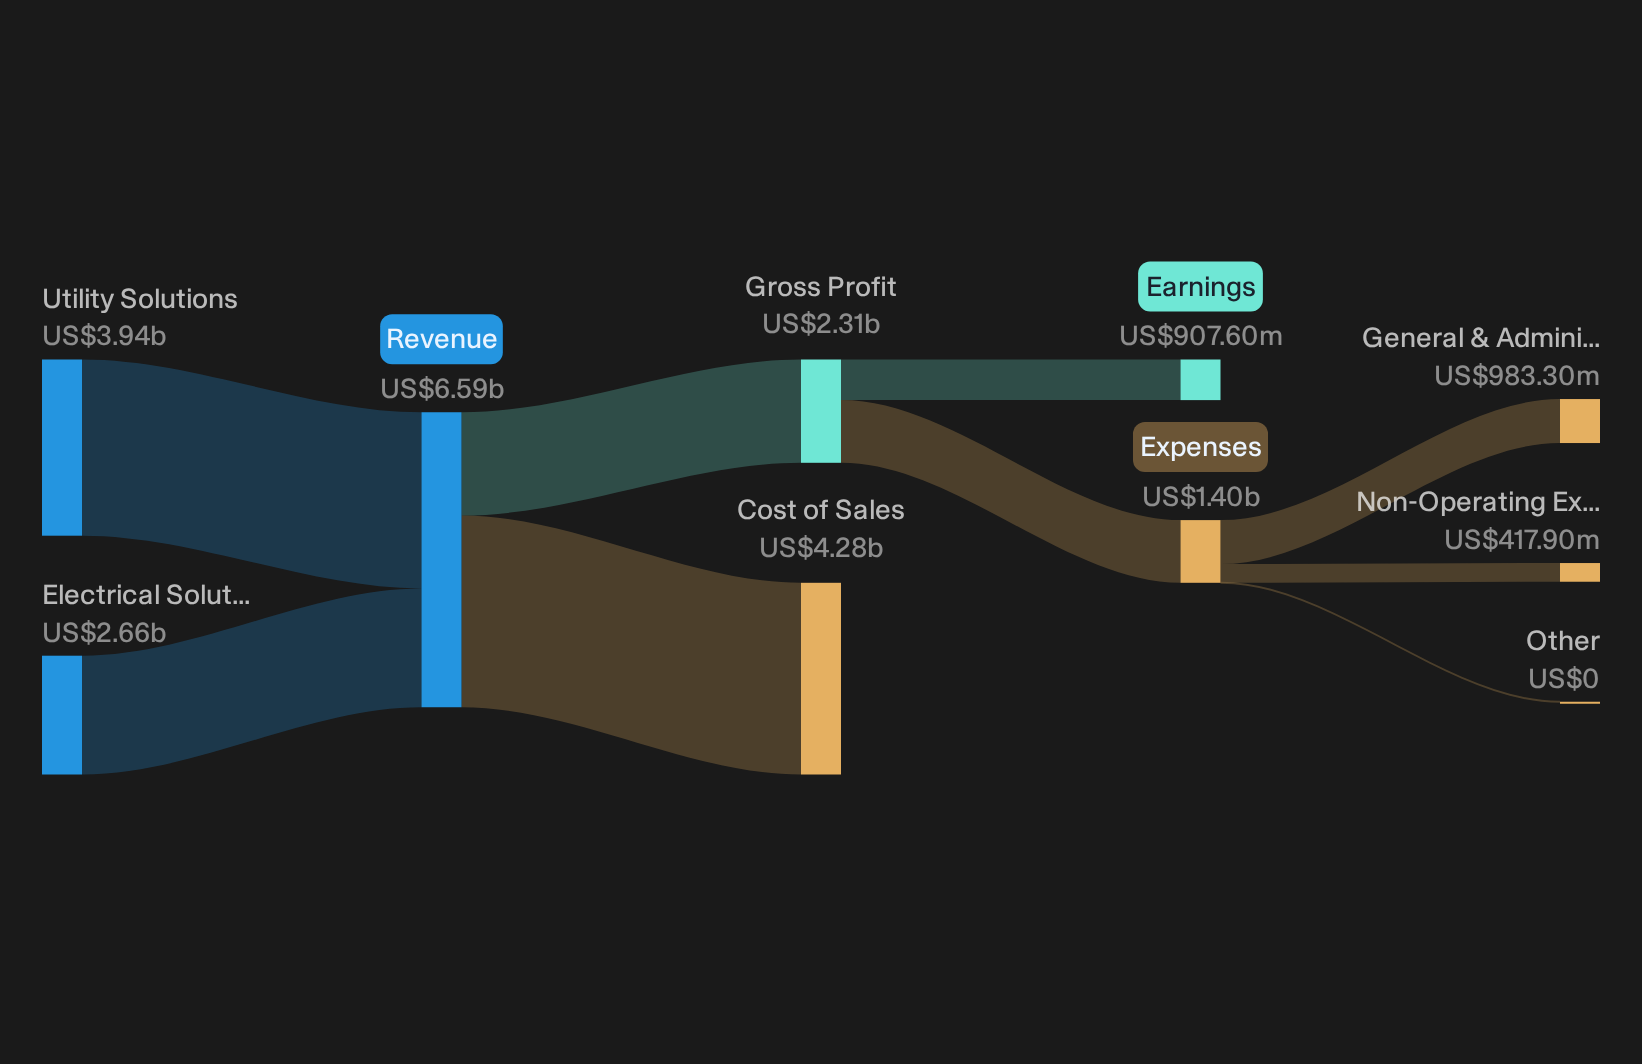
Operations: Hubbell generates about US$3.9b from Utility Solutions and US$2.7b from Electrical Solutions, largely tied to US$6.1b domestic revenue.
Market Cap: US$22.1b
Hubbell fits this income focused US industrial screen as a grid and power infrastructure supplier. Its earnings are closely linked to real economy spending rather than long dated growth stories, which is exactly where higher rates and a firm labor backdrop can shift investor attention.
"Hubbell is entering a long period of elevated spending on grid hardening and modernization, supported by a strong Utility Solutions order book, a first half 2026 book to bill of about 1.2x and projects already extending into 2027, which can support revenue and earnings growth visibility."
What really shapes Hubbell's appeal now is how one quiet trade off between leverage and pricing power filters through future dividend headroom.
That trade off is exactly what the full narrative for Hubbell unpacks, revealing where Hubbell's grid demand, pricing power and balance sheet strength could be quietly accelerating.
Seeking Alternatives Before The Crowd
Markets move fast. The best setups rarely stay quiet for long before momentum builds, prices start flying and ideal entry ranges get caught higher. Scan fresh ideas while it matters and get in early.
- Spot early strength in beaten down quality, then run your filters across the 39 high quality undervalued stocks before valuations re-rate and that window for calm entry prices drops.
- Track cash rich potential compounders, using the curated list of solid balance sheet and fundamentals (24 results) to focus on resilient balance sheets while they sit under the radar for now.
- Ride the next wave in electrification and infrastructure using the hand picked 42 power grid technology and infrastructure stocks while capital is still rotating into these themes and not fully priced in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com