


Salesforce’s agreement to acquire Braze (BRZE) for US$47.50 per share in cash, valuing the business near US$5.66b, has pushed the stock sharply higher and turned attention to the deal terms.
That takeover announcement has reshaped Braze’s trading pattern, with a 60.89% 1 month share price return and a 72.53% 3 month share price return pointing to strong deal driven momentum, while the 63.59% 1 year total shareholder return contrasts with a slightly declining 3 year total shareholder return of 1.10%.
Scan other software stocks showing similar deal driven momentum with our hand picked 39 high quality undervalued stocks, which also pair strong cash generation with healthier balance sheets.
Braze has already re-rated sharply on Salesforce’s US$47.50 per share bid, yet the stock still trades below the offer. How much of the potential upside is already captured in the current price?
Most Popular Narrative: 3.7% Undervalued
Braze is trading at $45.79 compared with a widely followed fair value estimate of about $47.54, which leaves only a modest gap for investors to weigh against the Salesforce offer at $47.50.
The agreement for Salesforce to acquire Braze for about US$5.66b to US$5.9b, combined with a three year collaboration with AWS that includes co selling, incentives and Marketplace distribution, creates potential for wider distribution and larger deal sizes. This can support revenue growth and improved net margins within a larger ecosystem.
See why 18 investors see Braze as 4% undervalued.
Using the 8.46% discount rate in that narrative, the implied fair value sits only slightly above both Braze’s last close and the analyst consensus target of $47.54. The pricing cluster around $47 suggests the market and the most tracked narrative are broadly aligned on what the business is worth as a standalone entity.
That tight band between the fair value, the current share price and the $47.50 Salesforce bid helps frame the remaining spread as mostly deal risk and timing premium rather than a large valuation gap. Anyone assessing Braze at this point is really weighing that residual merger spread against risks such as legal challenges to the transaction, ongoing losses of $113.0 million on $834.2 million of revenue, and the forecast that the company is not expected to reach profitability over the next 3 years.
Result: Fair Value of $47.54 (UNDERVALUED)
Still, deal investigations and the ongoing loss of $113.0 million on $834.2 million of revenue could pressure Braze if legal outcomes or execution disappoint.
Find out about the key risks to this Braze narrative.
Another View: Braze Looks Expensive On Sales
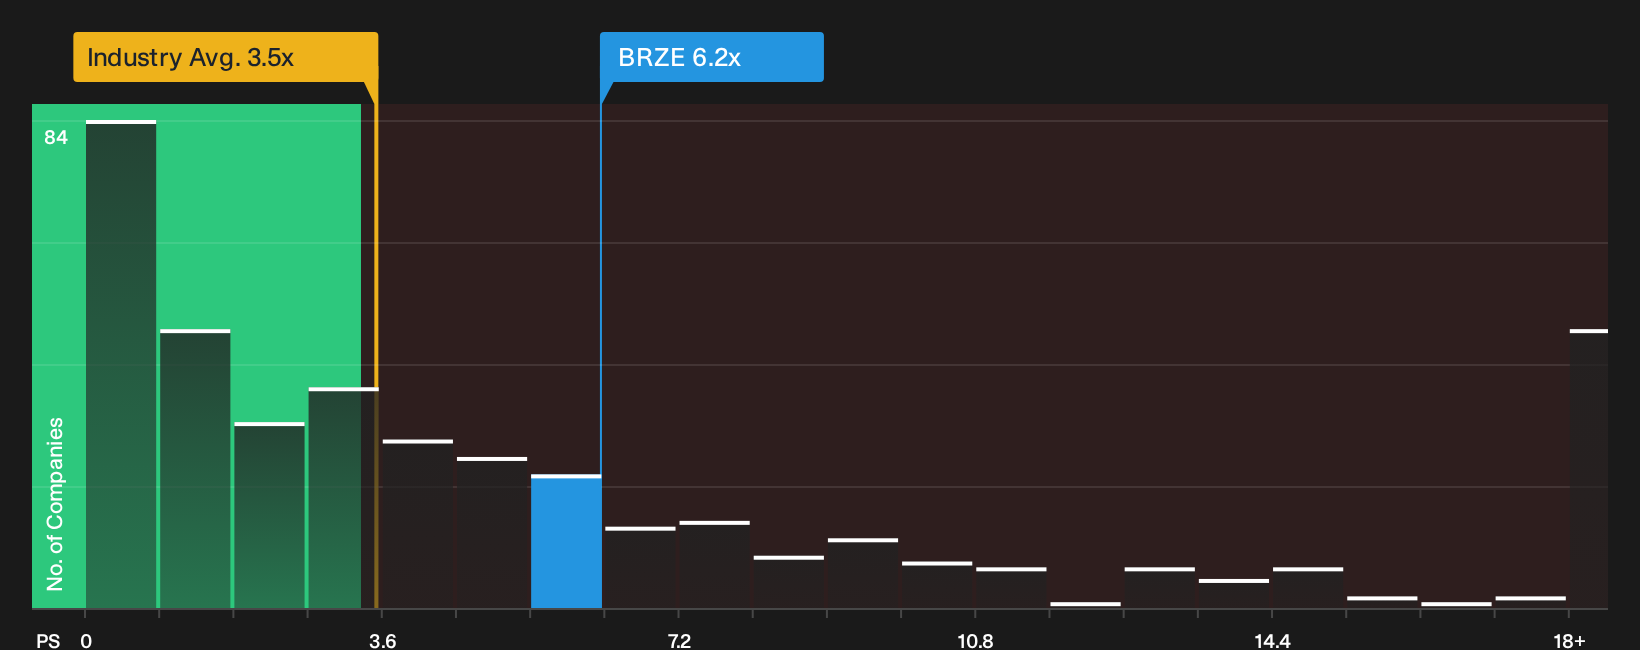
On a simple sales based lens, Braze screens very differently. The stock trades on a P/S ratio of 6.2x, compared with 3.5x for the broader US Software group, a 5.6x peer average and a fair ratio estimate of 4.8x.
That premium means investors are paying materially more revenue per dollar than both the sector and direct competitors. The fair ratio estimate also indicates that the multiple could move lower rather than higher over time. If the Salesforce deal stalls or breaks, how comfortable are you owning Braze on this kind of valuation starting point?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Braze’s value case can be confusing. Move quickly, review the underlying data, and form a view that fits your risk tolerance using the 2 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Braze?
If you stop with Braze, you miss a wider field of opportunities. Use the tools at hand and pressure test your next move across different styles of investments.
- Target resilient compounding potential by reviewing a 8 dividend fortresses that may suit an income focused approach without ignoring quality.
- Hunt for overlooked potential by scanning a 19 high quality undiscovered gems that filters for strong fundamentals hiding outside the usual watchlists.
- Dial down portfolio stress by reviewing a 29 resilient stocks with low risk scores that concentrates on stocks with more robust risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com