


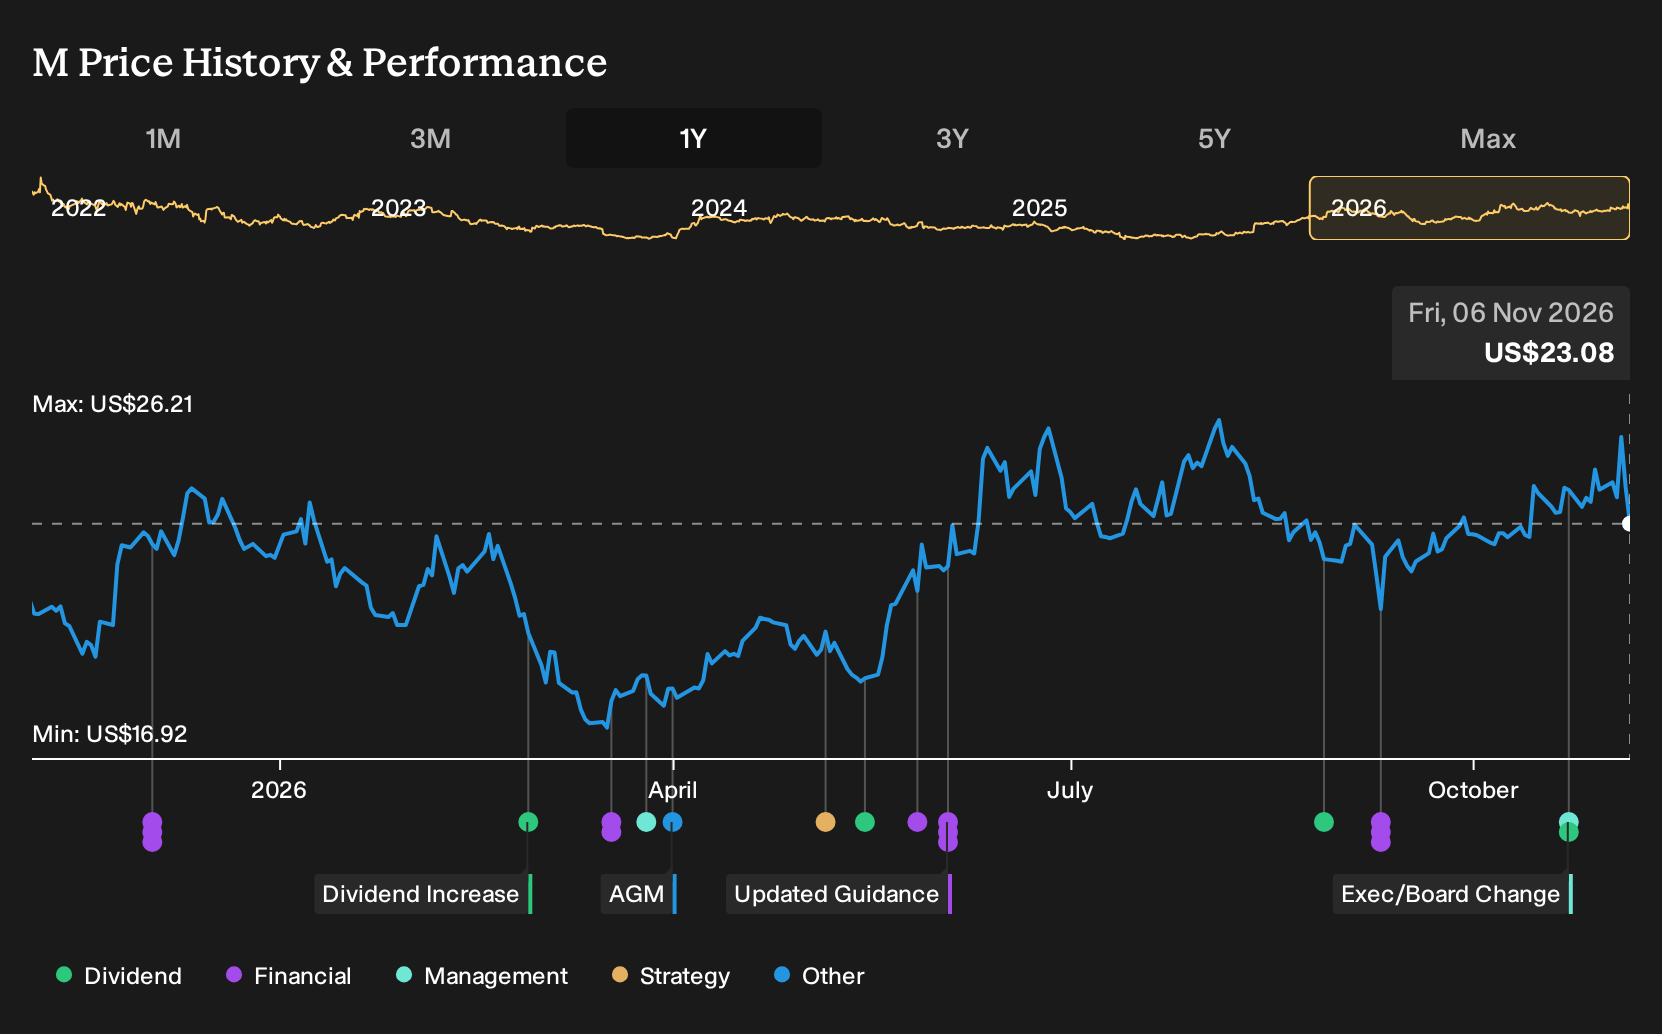
- Macy's recently came under pressure as investors reacted to expectations that the upcoming earnings report will show a lower year over year earnings per share figure.
- The focus has shifted firmly to Macy's core operations, with attention on whether omnichannel investments and store programs can offset the anticipated earnings softness.
- We will now look at how Macy's investment narrative could be affected by expectations for weaker near term earnings in the upcoming report.
Macy's Investment Narrative Recap
Macy's shareholders need to believe the omni channel plan can keep customers engaged even if earnings soften in the near term. The current pressure around an expected EPS decline puts more weight on whether digital, buy online pick up in store, and service upgrades can support sales and help protect margins through better conversion and order values.
The biggest short term catalyst is execution on store optimization and the Reimagine format in those higher productivity locations. The key risk is that ongoing pressure from e commerce rivals and promotional intensity forces Macy's to give up pricing or volume, which could dilute the benefits of recent margin and supply chain efficiency work.
The most relevant backdrop to the recent share pullback is that analysts already expect Macy's earnings to decline by about 2.3% per year over the next 3 years. The market reaction ahead of results is essentially a real time test of how much of that softer EPS path is already reflected in expectations and what a weaker print might signal about execution.
That forecast sits against meaningful work on omni channel investments, Reimagine stores, AI supported supply chain changes and a push into higher AUR and luxury through Bloomingdale's and Bluemercury. For you as an investor, the question is whether these efforts can offset the drag from expected earnings declines and the ongoing risk of market share pressure.
What The Current Forecasts Assume For Macy's
Macy's narrative projects US$20.9b revenue and US$657.7m earnings by 2029. This rests on analysts baking in a 2.8% yearly revenue decline and an earnings decrease of about US$92.3m from US$750.0m today.
Uncover why Macy's fair value indicates a valuation gap that is approximately aligned with its current price.
Exploring Other Perspectives
One alternate angle on Macy's centers on bullish analysts who treat the Reimagine fleet as a potential upside swing, not just a way to cushion earnings pressure. This group was penciling in about US$22.5b of revenue and roughly US$659.1m of earnings by 2029. That is more optimistic than consensus, and the latest EPS worries could easily shift both narratives.
Explore 3 other Macy's fair value estimates, including one that suggests as much as 50% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Macy's research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Macy's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Macy's overall financial health at a glance.
Looking For More Ideas Beyond Macy's?
If you want to balance your Macy's view with a broader watchlist, you can cast the net wider using the Simply Wall St Screener and compare how other businesses stack up on quality, valuation and risk.
- For investors who care most about resilient balance sheets and dependable fundamentals, you can filter the market using our list of solid balance sheet and fundamentals (24 results) to see which businesses currently clear that bar.
- If capital preservation and smoother rides matter to you, you may want to focus on resilience with a curated 29 resilient stocks with low risk scores that screens for companies with lower risk profiles.
- To look for underfollowed opportunities with stronger numbers than their popularity suggests, you can scan the 19 high quality undiscovered gems and see which stocks might merit a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com