


Even when a business is losing money, it's possible for shareholders to make money if they buy a good business at the right price. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. Having said that, unprofitable companies are risky because they could potentially burn through all their cash and become distressed.
Given this risk, we thought we'd take a look at whether Elicio Therapeutics (NASDAQ:ELTX) shareholders should be worried about its cash burn. In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
How Long Is Elicio Therapeutics' Cash Runway?
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. When Elicio Therapeutics last reported its September 2026 balance sheet in November 2026, it had zero debt and cash worth US$31m. Looking at the last year, the company burnt through US$38m. Therefore, from September 2026 it had roughly 10 months of cash runway. That's quite a short cash runway, indicating the company must either reduce its annual cash burn or replenish its cash. You can see how its cash balance has changed over time in the image below.
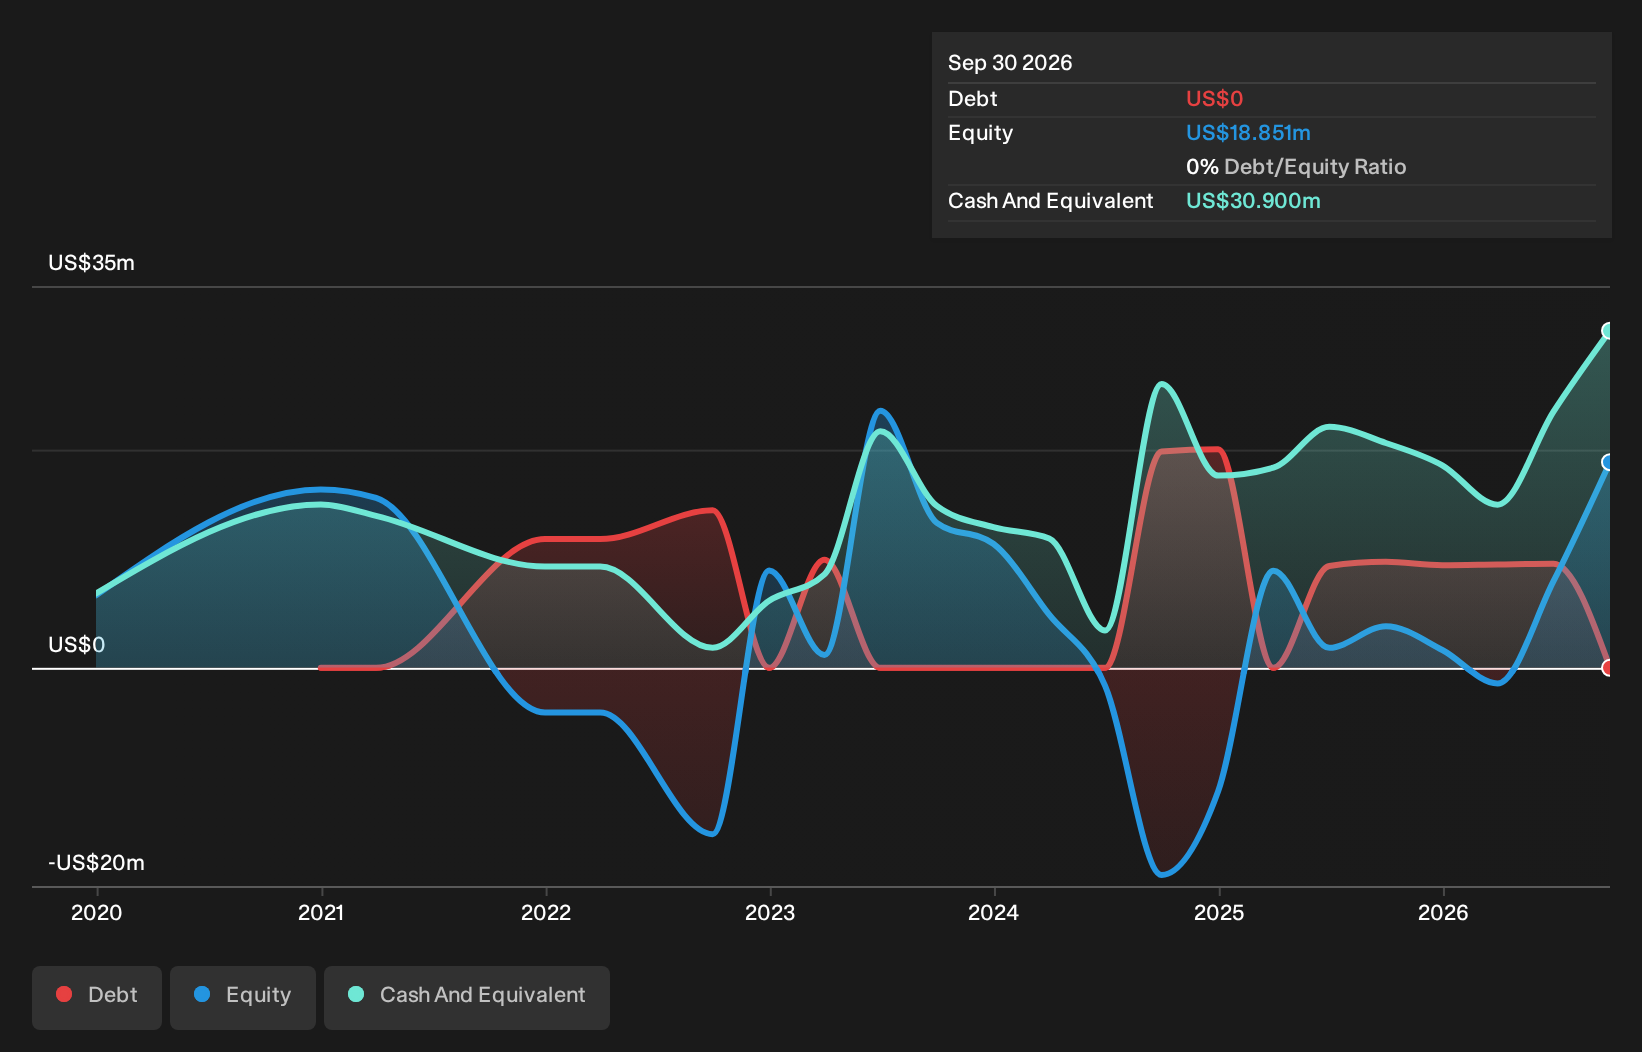
See our latest analysis for Elicio Therapeutics
How Is Elicio Therapeutics' Cash Burn Changing Over Time?
Because Elicio Therapeutics isn't currently generating revenue, we consider it an early-stage business. So while we can't look to sales to understand growth, we can look at how the cash burn is changing to understand how expenditure is trending over time. It's possible that the 3.2% reduction in cash burn over the last year is evidence of management tightening their belts as cash reserves deplete. Clearly, however, the crucial factor is whether the company will grow its business going forward. So you might want to take a peek at how much the company is expected to grow in the next few years.
How Easily Can Elicio Therapeutics Raise Cash?
Even though it has reduced its cash burn recently, shareholders should still consider how easy it would be for Elicio Therapeutics to raise more cash in the future. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
In the last year, Elicio Therapeutics burned through US$38m, which is just about equal to its US$37m market cap. Given just how high that expenditure is, relative to the company's market value, we think there's an elevated risk of funding distress, and we would be very nervous about holding the stock.
So, Should We Worry About Elicio Therapeutics' Cash Burn?
Even though its cash burn relative to its market cap makes us a little nervous, we are compelled to mention that we thought Elicio Therapeutics' cash burn reduction was relatively promising. After considering the data discussed in this article, we don't have a lot of confidence that its cash burn rate is prudent, as it seems like it might need more cash soon. Taking a deeper dive, we've spotted 7 warning signs for Elicio Therapeutics you should be aware of, and 4 of them are a bit concerning.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.