


Hexcel’s bobsled partnership puts its composites in the Olympic spotlight
Hexcel (HXL) is back in focus after joining a new partnership with 47G, Albany Engineered Composites, Nammo Composite Solutions and USA Bobsled/Skeleton to develop advanced composite cowlings for next generation U.S. bobsleds.
For investors tracking Hexcel, the latest bobsled partnership lands after a mixed stretch, with the 90 day share price return down 22.3% even as the 1 year total shareholder return of 17.3% and 5 year total shareholder return of 34.9% point to longer term momentum that has remained intact.
Scan beyond Hexcel and compare this Olympic-grade materials story with other advanced manufacturing plays through a curated set of list of solid balance sheet and fundamentals (24 results)
Supporters view Hexcel’s bobsled work and its recent revenue and net income growth as evidence that the setback in the last 90 days may be overdone. Skeptics emphasize the company’s elevated valuation metrics and the recent share price pressure. The key question is which side the numbers appear to support.
Most Popular Narrative: 19% Undervalued
Hexcel’s most followed valuation narrative pegs fair value at $98.87, which sits above the recent $80.40 close and frames the recent pullback as a pricing gap rather than a verdict on the business.
The main condition is that Hexcel turns the planned roughly $700 million of incremental commercial and defense revenue and its existing capacity into the higher margin profile management is targeting, while containing inflation and start up costs.
The numbers now imply a bullish view on Hexcel, with current margins, cash generation targets and external valuation work together suggesting the share price does not fully reflect the projected earnings and free cash flow profile.
See why 6 investors see Hexcel as 19% undervalued.
Result: Fair Value of $98.87 (UNDERVALUED)
Still, Hexcel’s heavier near term hiring and restart costs, plus long dated Airbus contracts signed before recent inflation, could pressure margins if the timing of demand disappoints.
Find out about the key risks to this Hexcel narrative.
Another View: Hexcel’s Rich Earnings Multiple
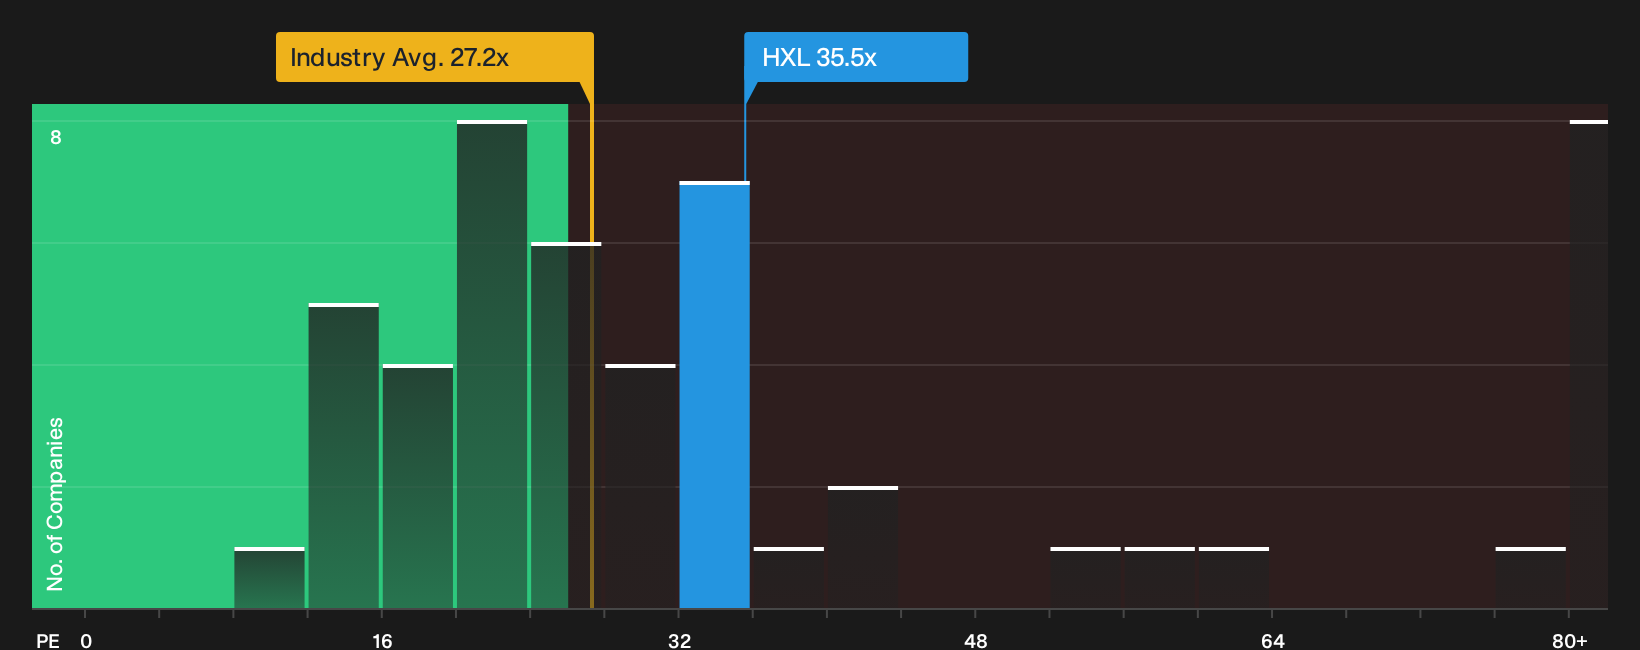
Hexcel may look appealing against a $98.87 fair value, yet the current P/E of 35.5x tells a different story. That is higher than the US Aerospace & Defense industry at 27x and above the 26.7x fair ratio that the market could move toward over time.
If sentiment shifts toward that lower fair ratio, the valuation gap would close from the top down, not by lifting the share price. The key question for investors is whether Hexcel’s earnings profile justifies paying materially more than both sector and fair ratio benchmarks, or if patience is better rewarded elsewhere.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Hexcel’s valuation and risks are clear, so move quickly, review the underlying data, and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Hexcel?
Hexcel’s story is just one angle. Broaden your watchlist now so you are not relying on a single theme when fresh opportunities appear.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (24 results) that filters out weaker financial profiles.
- Hunt for quality at a discount through a focused set of 39 high quality undervalued stocks that may offer stronger value than headline stories like Hexcel.
- Anchor your portfolio with potential income ideas using a hand picked pool of 8 dividend fortresses built around higher yield and durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com