


Centrus Energy has been through a sharp reset, with the share price down heavily this year after a very strong multi year run. The key issue now is whether the current valuation still lines up with what the business is earning. For anyone tracking Centrus Energy today, the question is how that mix of past gains, recent losses and new projects stacks up against its earnings power.
- Over the past 3 years the stock has gained about 107.0%, which puts a lot of past optimism on the line when you weigh the current price against its earnings.
- The push to expand uranium enrichment capacity and build out a secured fuel supply chain can influence earnings quality, capital needs and how quickly any future cash flows might arrive.
- The analysts covering Centrus Energy have run their own numbers. See what analysts think Centrus Energy's shares could be worth.
The stock's next move may depend on whether today's price can be explained by Centrus Energy's current earnings when set against the Fair Ratio benchmark.
If you want more uranium exposure alongside Centrus Energy, a focused stock screen built around 17 nuclear energy infrastructure stocks is a useful next step for broader research.
Has Centrus Energy Run Too Far on Earnings?
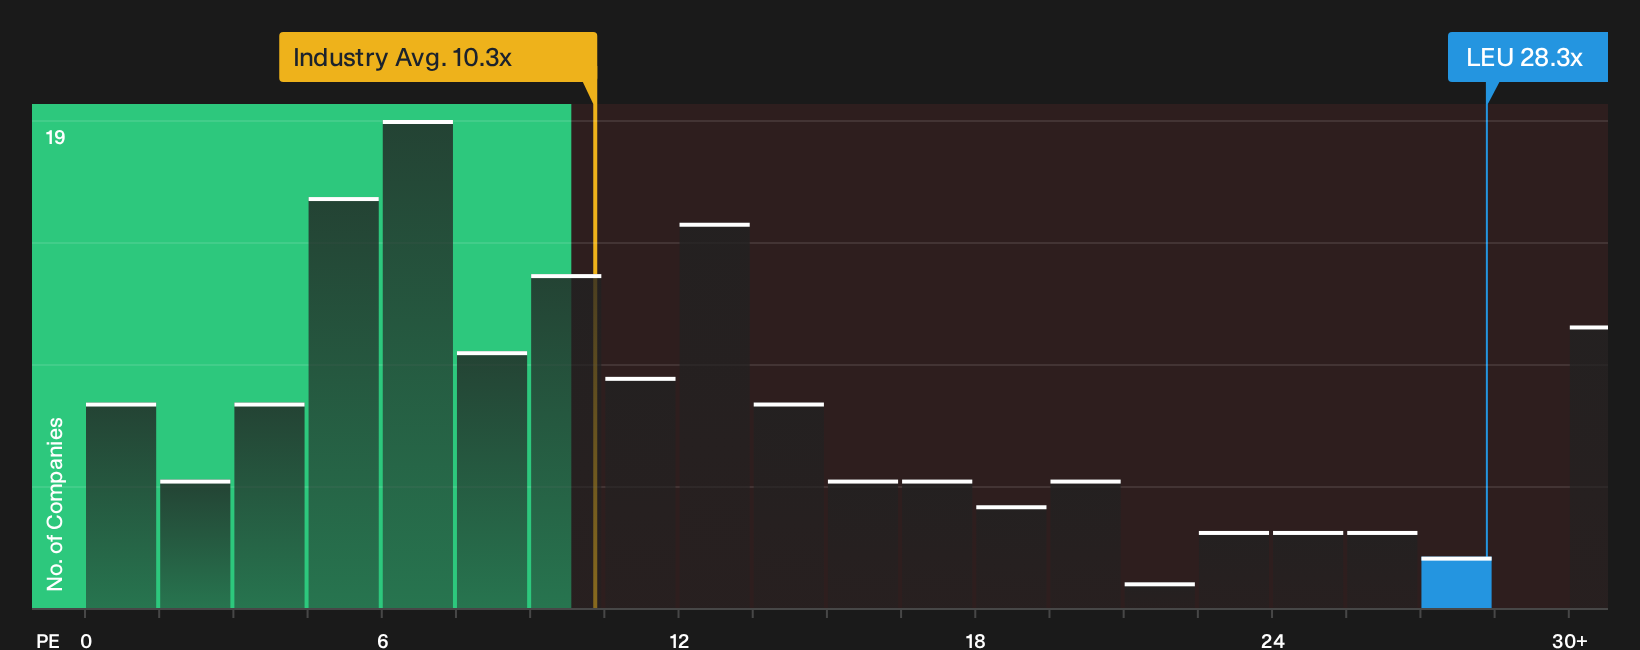
The P/E ratio suits Centrus Energy because earnings are central to how investors are weighing its enrichment backlog against current profitability. On this yardstick, the stock trades at about 28.3x earnings, which is richer than both the broader Oil and Gas sector on roughly 10.3x and the peer group at about 23.4x. That gap suggests buyers are paying a premium for Centrus Energy’s earnings stream compared with more traditional energy businesses and closer nuclear peers.
Recent progress on the Ohio expansion and the growing enrichment backlog has supported sentiment, yet the current P/E still screens as overvalued versus the Fair Ratio benchmark. The Fair Ratio model heavily penalises Centrus Energy for its loss making free cash flow profile and risk factors, so its implied benchmark functions more as a warning flag rather than a precise target. For you as a shareholder or potential buyer, the key question is whether the enrichment buildout, contract visibility and balance sheet strength justify paying a premium multiple for this level of earnings. Explore the numbers behind Centrus Energy's P/E valuation.
The Centrus Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Centrus Energy valuation puzzle leaves off. They spell out which paths for future earnings, growth and margins would need to play out for the stock to be worth materially more or less than it is today on the market. Each scenario ties a fair value to a clear set of potential catalysts and risks for Centrus Energy, so you can track which storyline seems to be matching reality over time.
One of the top community narratives on Centrus Energy: 45% undervalued
"Centrus Energy (LEU) offers the most direct public-market exposure to U.S. HALEU production, a critical bottleneck for advanced nuclear deployment..."
Discover why this Narrative puts Centrus Energy at 45% undervalued.
Centrus Energy’s price is only half the story
Before you decide how Centrus Energy fits in your portfolio, it is worth asking who is steering the business, how their pay is structured and whether those incentives line up with your goals. See who runs Centrus Energy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com