


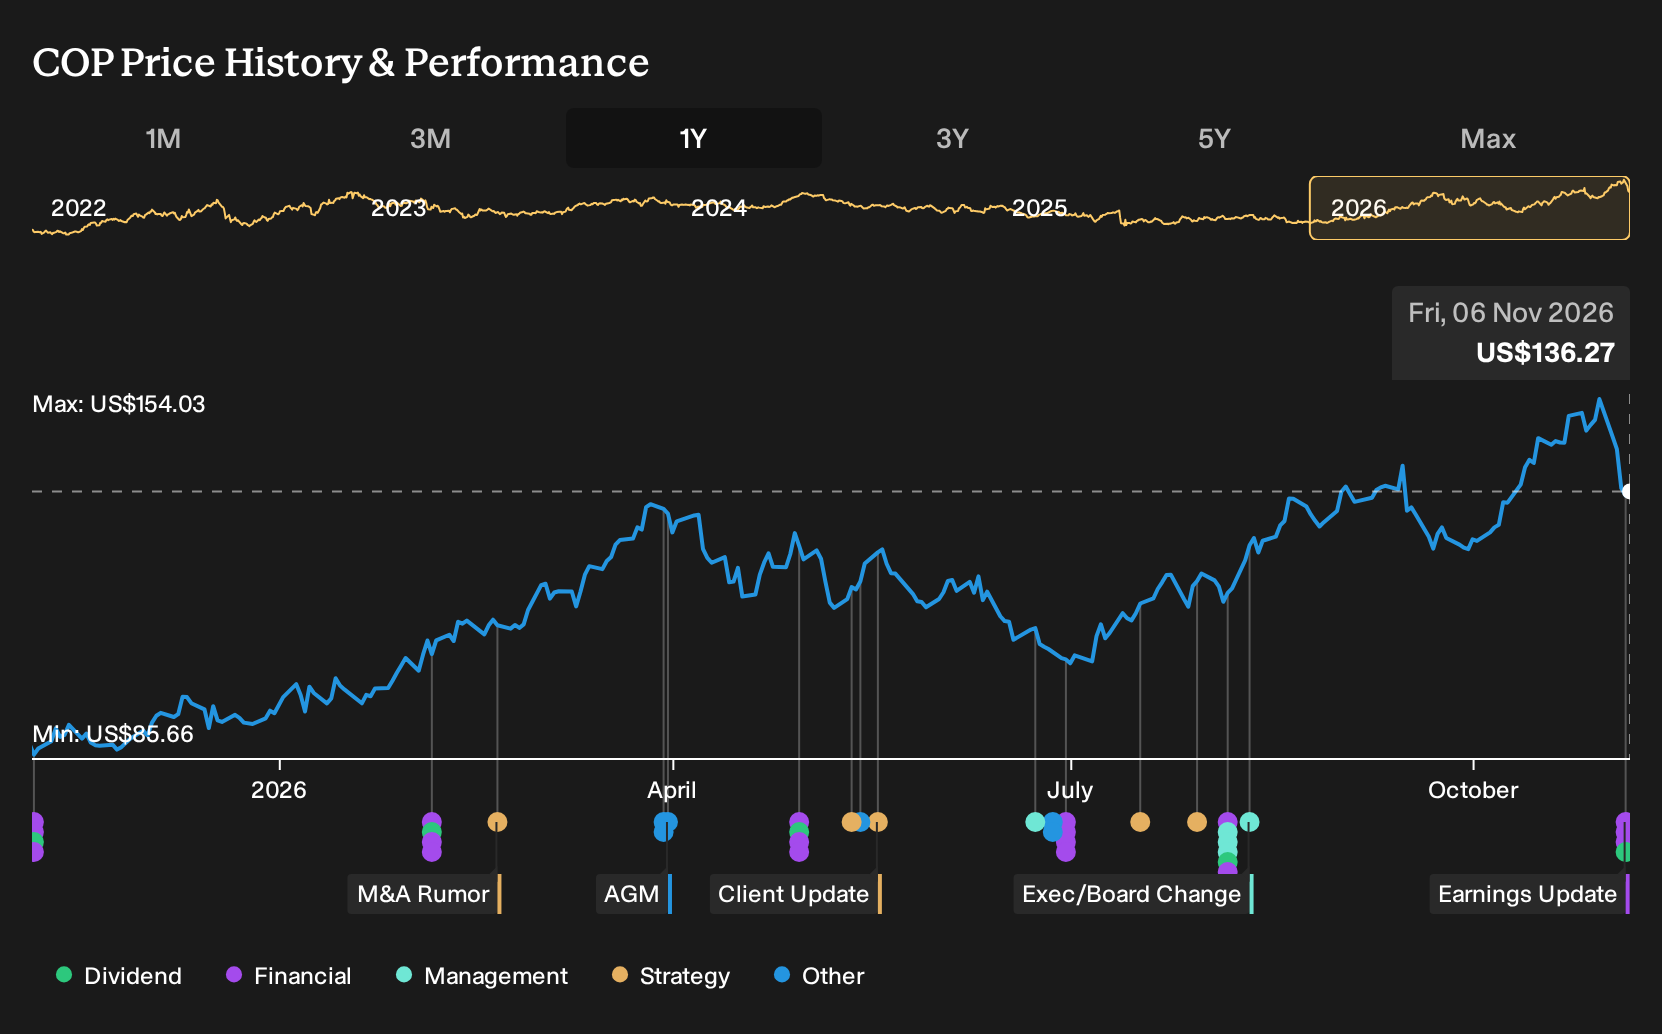
- ConocoPhillips reported strong Q3 2026 results, with revenue of US$20.057b and net income of US$4.001b, alongside an 11% increase in the quarterly dividend to US$0.93 per share.
- Solid cash generation allowed ConocoPhillips to return US$3.4b to shareholders through dividends and buybacks, while production guidance and key long life projects stayed on track despite operational pressures in regions such as Qatar and Surmont.
- The focus now turns to how ConocoPhillips’ stronger earnings and higher base dividend may influence its longer term cash flow investment narrative.
Scan other energy producers with similar cash generation and shareholder return profiles to ConocoPhillips by reviewing the hand picked 39 high quality undervalued stocks that may be flying under the radar.
ConocoPhillips Investment Narrative Recap
To own ConocoPhillips, you need to be comfortable with a business that leans on big, long life projects and a large Lower 48 shale engine to generate cash. The Q3 2026 update reinforced that earnings and cash from operations are currently strong, even as production slipped 2% after asset sales and issues in Qatar and Surmont.
The key near term catalyst remains clean execution on the LNG buildout and projects like Willow, while keeping capital spending disciplined. The biggest risk is that geopolitical or project delays around Qatar, Port Arthur or other large developments reduce expected volumes. The latest results and guidance do not materially change that equation.
The 11% increase in the ordinary dividend to US$0.93 per share is the most relevant announcement for this discussion. Management linked that move to strong free cash flow from Lower 48 assets and a stated plan to return 45% of cash flow from operations through dividends and buybacks, alongside a sizeable Q3 repurchase program.
For investors, the higher base dividend shifts cash returns from an aspiration to a clearer commitment. It also raises the bar for consistent execution. If large projects such as Willow and the LNG portfolio encounter cost, timing or geopolitical setbacks, the need to support this higher payout while also funding growth could become an important pressure point to monitor.
ConocoPhillips' narrative projects US$69.1b revenue and US$11.5b earnings by 2029. This would involve 2.4% yearly revenue growth and about a US$2.2b earnings increase from US$9.3b today.
Uncover why ConocoPhillips' fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the ConocoPhillips story around a sharper free cash flow jump than consensus assumes, helped by long life LNG and Willow projects. Before this earnings release, the most bullish forecasts were looking for about US$76.3b of revenue and US$13.7b of earnings by 2029. Those projections did not yet factor in the Q3 numbers or the 11% dividend raise. You can use this gap between the baseline outlook and the high end scenario as a cue to explore several competing narratives and decide which assumptions feel most reasonable to you.
Explore 3 other ConocoPhillips fair value estimates, including one that suggests as much as 143% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ConocoPhillips research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for ConocoPhillips. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ConocoPhillips' overall financial health at a glance.
Looking for more ConocoPhillips style investment ideas?
If the ConocoPhillips story has helped clarify what you want from cash flow, dividends, and project quality, you can use that blueprint to refine your wider watchlist. The Simply Wall St Screener can help you filter for other businesses that align with the mix of income, balance sheet strength, and risk that suits you.
- For investors who want lower volatility to anchor a portfolio, start by reviewing a curated group of 29 resilient stocks with low risk scores that may help smooth out the ride beside more cyclical holdings.
- If resilience matters more to you than excitement, scan a list of solid balance sheet and fundamentals (24 results) that can help you focus on companies with stronger financial footing.
- When the goal is to pair quality with a more attractive entry point, look through a 19 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com