


- Nexans has signed a subcontract to supply a 420 km MI 110 kV cable system for the 1 GW Corinth Kos HVDC interconnection in Greece, a project aimed at strengthening links between the Dodecanese islands and the mainland. Production lines are expected to run from late 2026 to mid 2028.
- This Greek interconnection order highlights Nexans’ ability to secure large power transmission projects that can support utilization of its high voltage manufacturing assets and reinforce its positioning in grid infrastructure.
- We will now see how Nexans’ investment narrative around electrification and grid projects could be influenced by this Greek HVDC contract.
Scan 42 power grid technology and infrastructure stocks, which could also benefit from large grid and interconnection spending like the new Greek HVDC project awarded to Nexans.
Nexans Investment Narrative Recap
To own Nexans, you need to believe the electrification and grid renewal story can translate into long term, higher quality earnings, even though headline revenue is currently expected by analysts to edge down around 0.5% per year over the next three years. The Greek HVDC win helps illustrate demand for grid cables, but on its own it does not radically change the near term setup.
The key short term swing factor remains execution on large, capital intensive projects and on the enlarged grid footprint, while keeping Electrification margins healthy. The biggest risk right now is pressure on profitability from competition and new industry capacity, especially if order timing turns patchy or recently acquired assets in North America do not deliver expected benefits.
The Corinth Kos contract ties directly into Nexans’ plan to add Power Transmission and Power Grid capacity where demand already exceeds industry supply. Management wants more projects produced and installed with in house assets such as its European grid factories and the Nexans Electra cable laying vessel, and this Greek interconnection order feeds that pipeline.
For catalysts, investors are watching whether a steady flow of HVDC and interconnection work like this supports the thesis of stronger Electrification earnings over time, even as the top line is forecast to be broadly flat. Execution risk stays front and center. Large projects can strain cash, margins and timelines if installation or manufacturing issues emerge or if customers adjust ordering patterns.
What The Greek HVDC Deal Means Against Nexans’ Forecasts
Nexans' narrative projects €7.8b revenue and €516.0m earnings by 2029. This lines up with analysts assuming revenue will decrease by 3.1% per year and implies a €323.0m earnings increase from €193.0m today.
Uncover why Nexans' fair value indicates a 39% potential upside to its current price, which could narrow quickly.
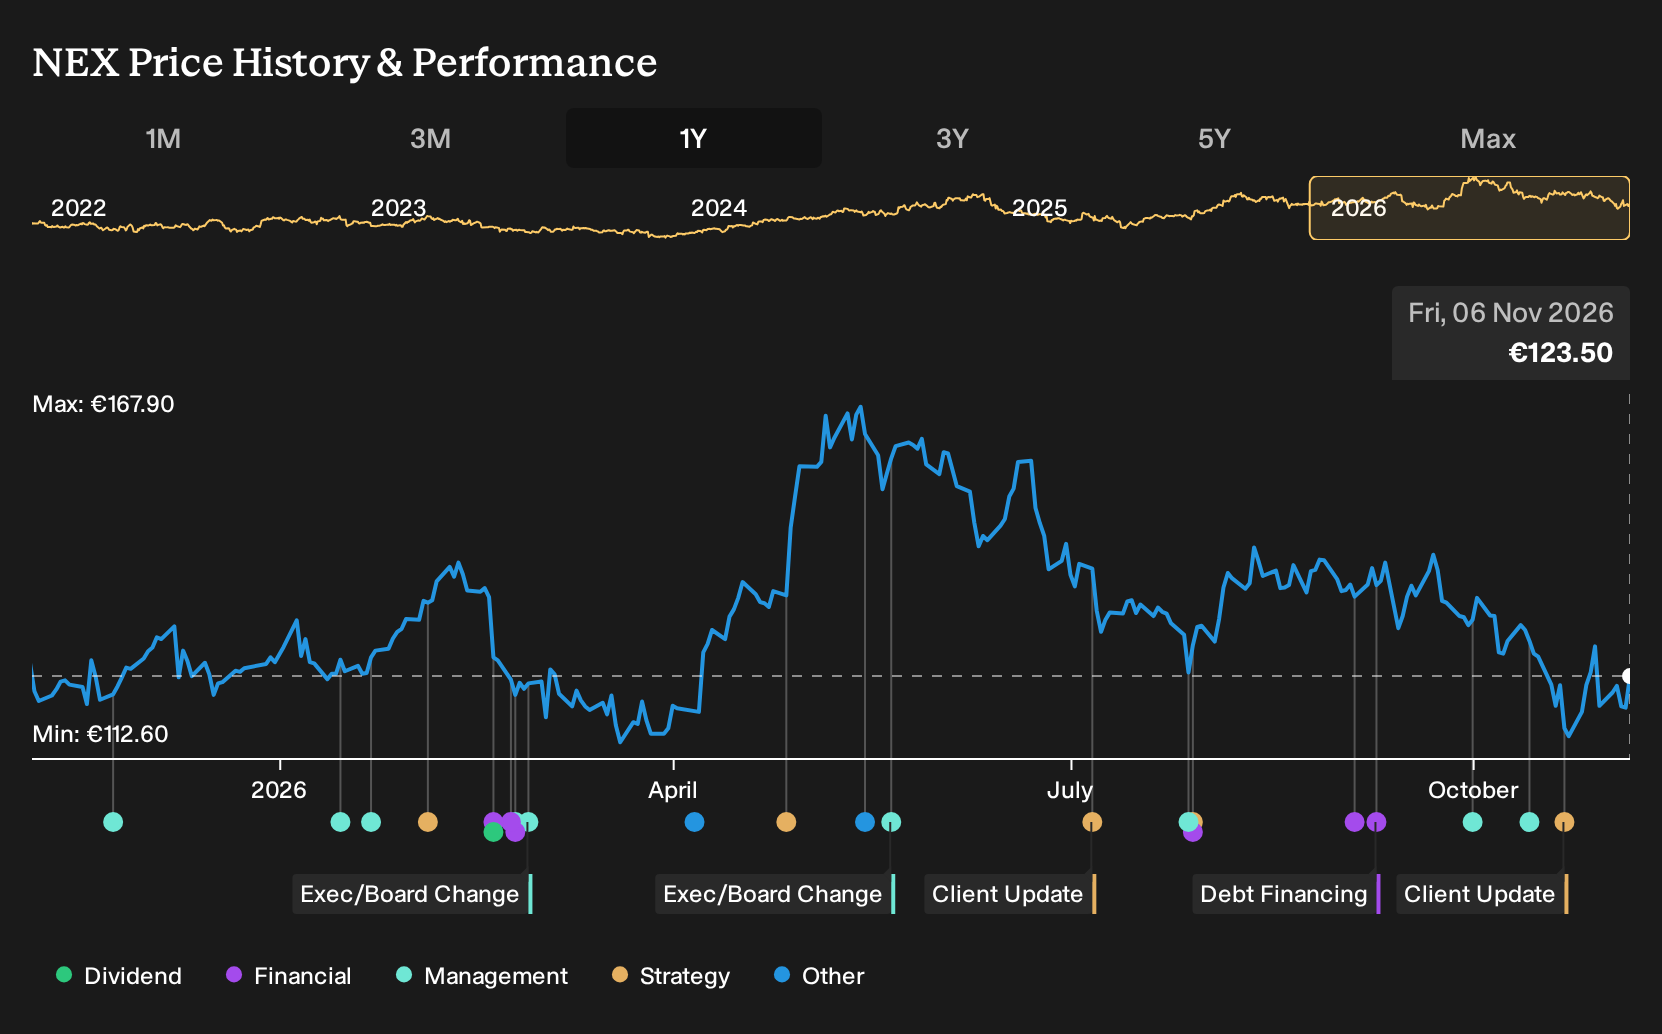
Exploring Other Perspectives
One alternative angle around Nexans focuses on the bullish catalyst of margin expansion. The most optimistic analysts were already pencilling in earnings of about €641.7m by 2029 on roughly €7.8b of revenue, compared with €516.0m in the consensus view. You can treat this Greek HVDC award as a fresh test of which storyline evolves.
Explore 5 other Nexans fair value estimates, including one that suggests there could be as much as 71% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nexans research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nexans. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nexans' overall financial health at a glance.
Looking For More Ideas Beyond Nexans?
If the Nexans story has sharpened your thinking about electrification and grid capacity, use that momentum to widen your opportunity set with a few targeted equity shortlists built in the Simply Wall St Screener.
- If capital preservation is high on your list, scan 212 resilient stocks with low risk scores that may offer a smoother ride through market swings.
- If you want income on top of potential capital gains, look at 232 dividend fortresses that combine meaningful yields with resilient payout profiles.
- If you are hunting for quality that is not already crowded, review 588 high quality undiscovered gems where fundamentals look strong yet market attention is still limited.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com