


- Walmart disclosed a multi year expansion of its partnership with Zipline, backing a US$1.5b funding round that will support the rollout of drone delivery from 300 additional store locations across the United States.
- The enlarged Zipline deal leans on Walmart’s dense store network, which already supports more than 2 million drone deliveries, to push faster fulfillment deeper into its existing retail footprint rather than relying on separate logistics hubs.
- We will now look at how Walmart's broader investment narrative could be influenced by this large scale drone delivery expansion.
Scan for other retailers quietly rewiring logistics like Walmart by tracking the curated 52 AI infrastructure stocks, which could benefit as automated supply chains and drone delivery infrastructure scale up.
Walmart Investment Narrative Recap
To own Walmart, you need to believe its omni channel model keeps pulling more shoppers into higher margin pools like marketplace fees, advertising and memberships while automation holds fulfillment costs in check. The drone expansion fits that story, but the near term catalyst still sits around execution in U.S. e commerce and Walmart Connect, rather than drones themselves.
The biggest current risk stays the same. Rapid delivery, especially on low ticket baskets, and loss making international e commerce can keep net margins under pressure if logistics costs do not move closer to break even. Drone rollout, if inefficiently utilized, could add to that cost drag rather than easing it.
Among recent moves, the expanded commercial agreement with Symbotic looks most relevant to Walmart’s drone push. Management has committed about US$6b over several years to bring more automation into 25 U.S. regional distribution centers, with an eye on e commerce inventory accuracy, storage density and how items flow through the network.
For you as a shareholder, that Symbotic deal sits right next to drones in the same execution question. Walmart is layering automation in the back end while experimenting with ultra fast fulfillment at the edge. The opportunity is a more scalable, fee rich marketplace and Walmart+ ecosystem. The risk is capital tied up in logistics projects that do not materially ease unit economics on fast delivery.
Walmart's current analyst narrative connects a 4.5% yearly revenue growth assumption with current earnings of US$22.1b and a forecast consensus earnings figure of US$29.5b by 2029. This implies an earnings increase of about US$7.4b over that period, as revenues are projected to reach US$839.4b in the same year.
Uncover why Walmart's fair value aligns with its current price.
Exploring Other Perspectives
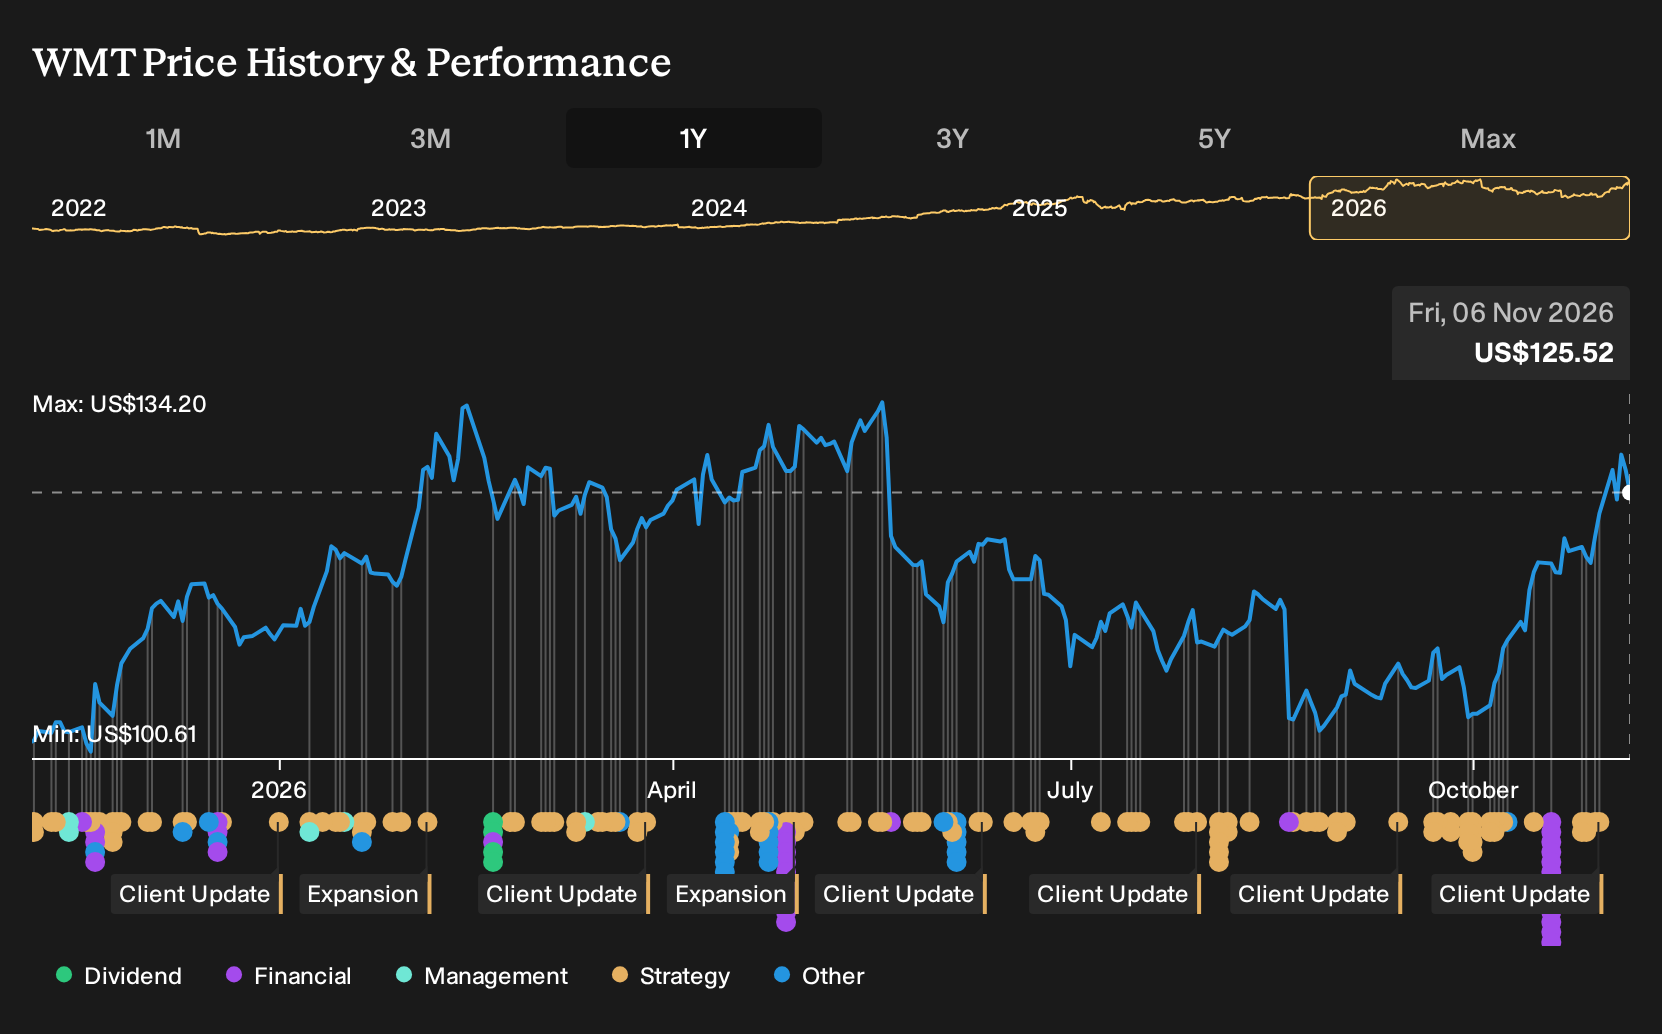
Thirteen fair value views from the Simply Wall St Community span roughly US$66 to US$155 per share, so opinions on Walmart’s pricing are wide apart. Use that spread as a prompt to stress test your own stance against risks around logistics profitability and potential catalysts in drones, health services and energy partnerships such as Base Power.
Explore 12 other Walmart fair value estimates, including one that suggests as much as 23% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Walmart research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Walmart. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Walmart's overall financial health at a glance.
Looking For More Investment Ideas Beyond Walmart?
If this Walmart story has you thinking about where automation, balance sheet strength and steady income streams might intersect, it can help to scan a broader watchlist built around those themes using the Simply Wall St Screener.
- If you want potential bargains with robust fundamentals, start with a focused set of 39 high quality undervalued stocks that may trade below what their quality suggests.
- For investors who care most about resilience and capital preservation, there is a curated pool of 29 resilient stocks with low risk scores that score well on downside protection.
- Income focused readers can zero in on reliable payers by reviewing a targeted group of 8 dividend fortresses offering stronger yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com