


Precinct Properties New Zealand Limited Precinct Properties Investments (NZSE:PCT) has announced a 1 for 1.0625 stock split or significant stock dividend, along with a special cash payout of NZ$0.0555509 per share, both effective 5 November 2026.
At a share price of NZ$1.073124 as of 7 November 2026, Precinct Properties New Zealand Limited Precinct Properties Investments has recorded an 8.02% 1 month share price return, while the share price is still down 15.48% year to date. The 3 year total shareholder return of 12.82% contrasts with a 5 year total shareholder return that is down 11.30%. This points to momentum that has recently improved but remains patchy over a longer horizon as investors weigh the coordinated stock split and special dividend against earlier weakness.
Scan how Precinct Properties New Zealand Limited Precinct Properties Investments stacks up against other income focused plays by reviewing our hand picked list of 232 dividend fortresses in the market today.
For Precinct Properties New Zealand Limited Precinct Properties Investments, a coordinated split and special dividend can signal confidence in the underlying portfolio, or a sentiment reset around a still-uneven track record. How does that compare with the current valuation?
Preferred Price-to-Sales Multiple of 6.6x: Is It Justified?
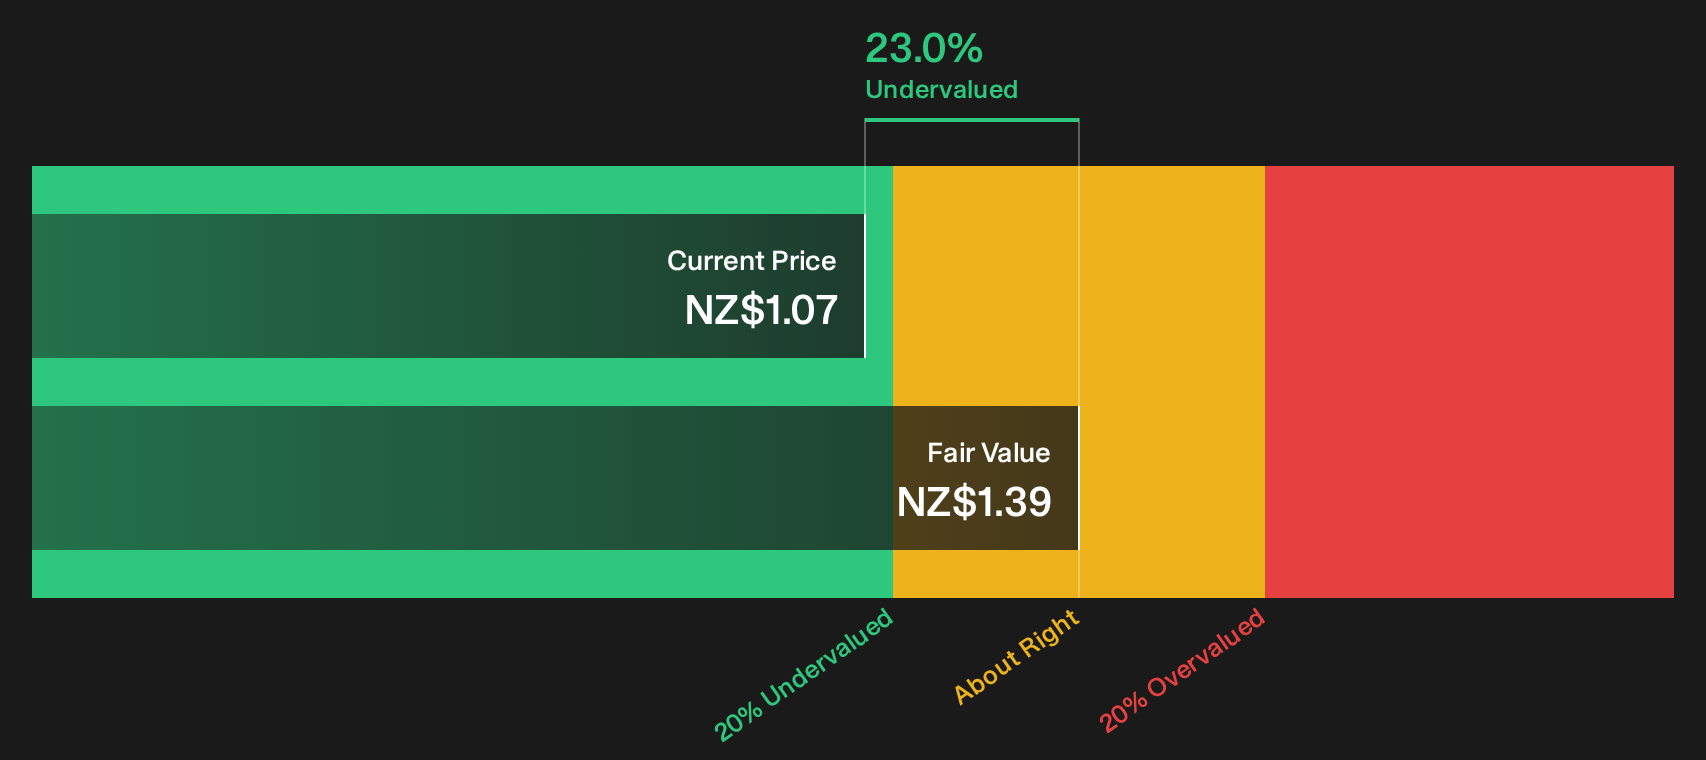
On Simply Wall St's SWS DCF model, Precinct Properties New Zealand Limited Precinct Properties Investments carries an estimated future cash flow value of NZ$1.39 per share, compared with the last close at NZ$1.07, which implies a discount of roughly 23% that investors will weigh against other valuation signals.
That SWS DCF model projects PCT's future cash inflows and then discounts those projections back to today using a required rate of return. This aims to translate long term expectations into a single present value per share. It is a theoretical construct that is very sensitive to assumptions around growth, margins and the discount rate, so it is best treated as one reference point rather than a precise number.
The P/S ratio tells a different story. PCT trades on a P/S of 6.6x, which the data flags as expensive compared with the Global Office REITs average of 4.6x. In simple terms, investors are currently paying more revenue dollars for Precinct Properties New Zealand Limited Precinct Properties Investments than for the broader peer group.
That premium also screens as stretched relative to an estimated fair P/S ratio of 4.8x. This is a level that reflects where the valuation could drift if the market leans more heavily on this regression based fair value anchor. Against that backdrop, the stock screens as rich compared with both the sector and the fair multiple estimate.
Result: Price-to-sales of 6.6x (OVERVALUED)
At the same time, the SWS DCF model suggesting a fair value of NZ$1.39 per share points to a meaningful gap between price and the model's view of long term cash generation for Precinct Properties New Zealand Limited Precinct Properties Investments. That contrast between a rich P/S multiple and a discounted DCF outcome underlines how different valuation tools can highlight very different aspects of the same equity story.
Look into how the SWS DCF model arrives at its fair value.
Still, Precinct Properties New Zealand Limited Precinct Properties Investments faces risks if office demand in Auckland and Wellington softens or if rental assumptions prove too optimistic.
Find out about the key risks to this Precinct Properties New Zealand Limited Precinct Properties Investments narrative.
Another Angle On Precinct Properties New Zealand Limited Precinct Properties Investments
The SWS DCF model actually flips the script. At a share price of NZ$1.07, Precinct Properties New Zealand Limited Precinct Properties Investments screens as undervalued against an estimated cash flow value of NZ$1.39 per share. That is a 23% gap. Which signal would you trust more: the rich P/S or the discounted DCF?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Precinct Properties New Zealand Limited Precinct Properties Investments for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 224 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Precinct Properties New Zealand Limited Precinct Properties Investments can feel messy, so act while the data is fresh and test the thesis yourself. To see how the upside potential stacks against the concerns in one place, run your own eye over the 2 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Precinct Properties New Zealand Limited Precinct Properties Investments?
If Precinct Properties New Zealand Limited Precinct Properties Investments has your attention, do not stop here. Fresh opportunities often emerge where pricing, quality, and income potential intersect most cleanly.
- Target resilient performers by checking out a 212 resilient stocks with low risk scores that keeps volatility in check while still giving your portfolio room to grow.
- Hunt for mispriced quality among 224 high quality undervalued stocks that pair sound fundamentals with price tags many investors have not fully appreciated yet.
- Spot early opportunities in 588 high quality undiscovered gems before attention and liquidity push valuations to levels that leave less room for upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com