


Martin Marietta Materials (MLM) just paired a third quarter earnings beat with higher full year 2026 revenue guidance, leaning on recent acquisitions and a heavier tilt toward aggregates and lime specialties.
Despite the guidance hike, Martin Marietta Materials shares trade around US$518.15 after a recent pullback. The 7 day share price return is down 4.12%, and the 1 day move is lower by 1.83% as investors weigh acquisition related costs against higher revenue expectations.
Compare Martin Marietta Materials' acquisition-driven story with a curated set of construction and materials peers by scanning list of solid balance sheet and fundamentals (24 results) for potential ideas with similar fundamentals.
After a strong run over 30 days but a weaker year to date, Martin Marietta Materials now trades well below recent highs. Does that pullback already reflect the acquisition noise, or are you still paying up?
Most Popular Narrative: 18% Undervalued
Martin Marietta Materials closed at $518.15, while the most followed narrative pegs fair value closer to $633.92. This frames the recent pullback as a valuation gap driven by acquisition execution and margin worries rather than a clean verdict on the business.
The portfolio shift away from cement and ready mix toward higher margin aggregates and specialties, including the completed Quikrete asset exchange, the New Frontier Materials bolt on and the combination with Lhoist North America that adds over 2 billion tons of limestone reserves, is expected to increase the mix of upstream materials with structurally higher margins and free cash flow conversion, which can support earnings quality and cash generation.
See why 12 investors see Martin Marietta Materials as 18% undervalued.
Result: Fair Value of $633.92 (UNDERVALUED)
Still, if diesel and energy costs stay sticky or the SOAR 2030 acquisitions underdeliver on planned synergies, the Martin Marietta Materials upside story could easily stall.
Find out about the key risks to this Martin Marietta Materials narrative.
Another View: Martin Marietta Materials Looks Expensive On Earnings
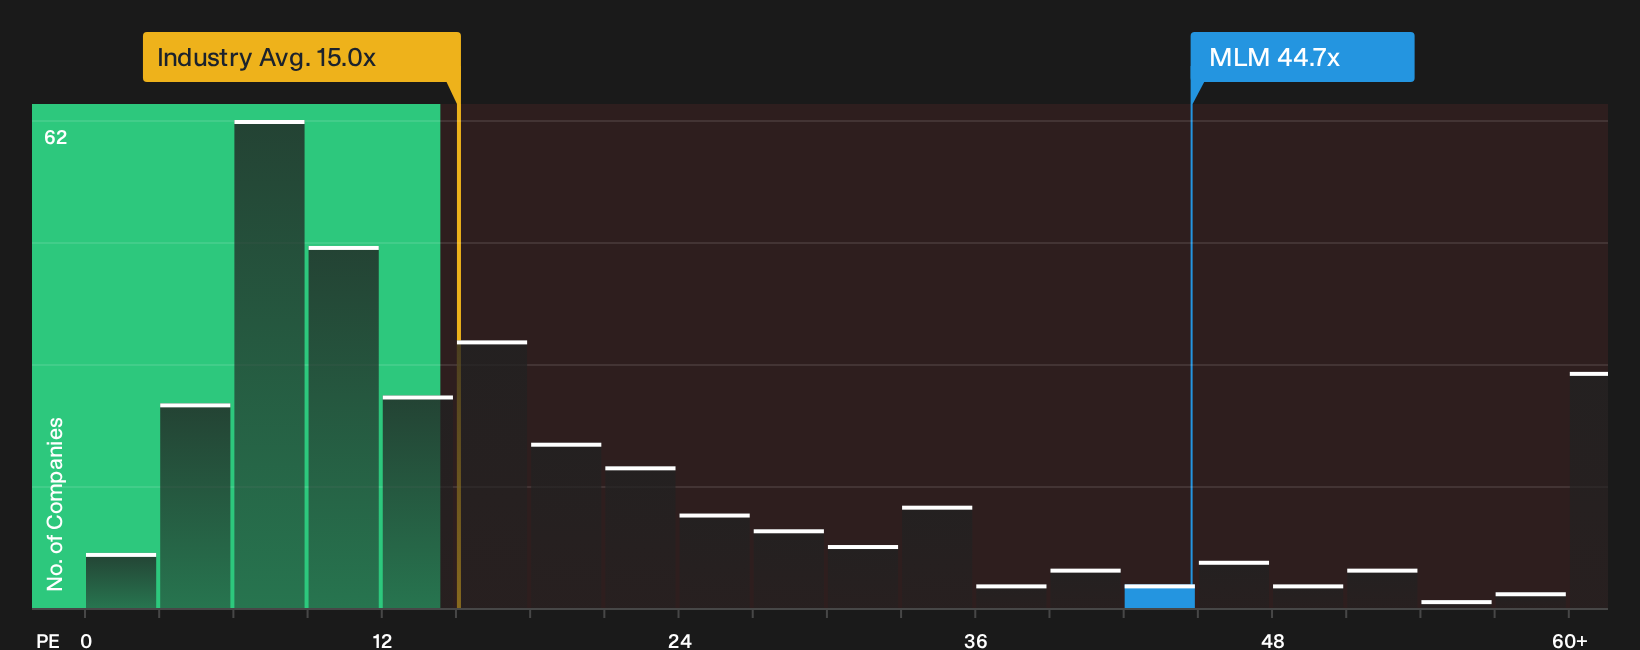
The fair value narrative points to an 18% discount, but the P/E picture pulls the other way. Martin Marietta Materials trades on a 44.7x P/E, compared with a 23.3x fair ratio, a 15x industry average and a 22.3x peer level. That is a rich premium. Is the acquisition story strong enough to justify it?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and execution risks can make Martin Marietta Materials tricky to size up, so move quickly, review the core data, and decide where you stand using 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Martin Marietta Materials?
If Martin Marietta Materials has sharpened your focus on quality and valuation, do not stop here. Use the Simply Wall Street Screener to widen your watchlist intelligently.
- Target resilient compounding potential by scanning a 39 high quality undervalued stocks that already combine quality fundamentals with pricing that screens below intrinsic value estimates.
- Build a sturdier income stream by checking a 8 dividend fortresses that pair higher yields with businesses assessed for payout strength and balance sheet support.
- Dial down portfolio risk by reviewing a 29 resilient stocks with low risk scores that score well on financial health and lower volatility characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com