


ITT (ITT) just combined a busy earnings week with a guidance bump, stronger orders and a confirmed dividend, giving investors fresh numbers to reassess how the stock’s recent gains stack up.
ITT’s latest jump, with a 1-day share price return of 4.92% and a 7-day share price return of 3.55%, comes after the raised guidance, strong Q3 order growth and the confirmed dividend. It lands on top of a 17.99% year to date share price return and a 3-year total shareholder return of 105.35%, which together suggest momentum has cooled slightly in the very short term but remains firmly positive over multi year periods.
Scan peers showing similar order strength and guidance upgrades with our hand picked 42 power grid technology and infrastructure stocks as you weigh ITT’s latest move.
Bulls see ITT’s raised outlook, free cash flow focus and SPX FLOW integration as underpriced. Bears point to the recent run and lower GAAP EPS. Which story do the current valuation markers support?
Most Popular Narrative: 20.5% Undervalued
ITT’s most followed valuation story pegs fair value at $258.46, above the recent $205.55 close. This puts the latest post earnings pop in a wider context for anyone weighing the guidance upgrade against price.
Strong, sustained order growth and backlog, supported by a company level book to bill of 1.1 in Q2 2026, nearly doubled backlog over three years, and especially high ratios at Svanehøj and SPX FLOW, points to future revenue recognition that may not be fully reflected in ITT’s valuation.
See why 5 investors see ITT as 20% undervalued.
Result: Fair Value of $258.46 (UNDERVALUED)
Still, the ITT story can fray if project heavy backlogs see timing pushouts or if integration work at SPX FLOW and Svanehøj drags on margins.
Find out about the key risks to this ITT narrative.
Another View: ITT Looks Expensive On Earnings
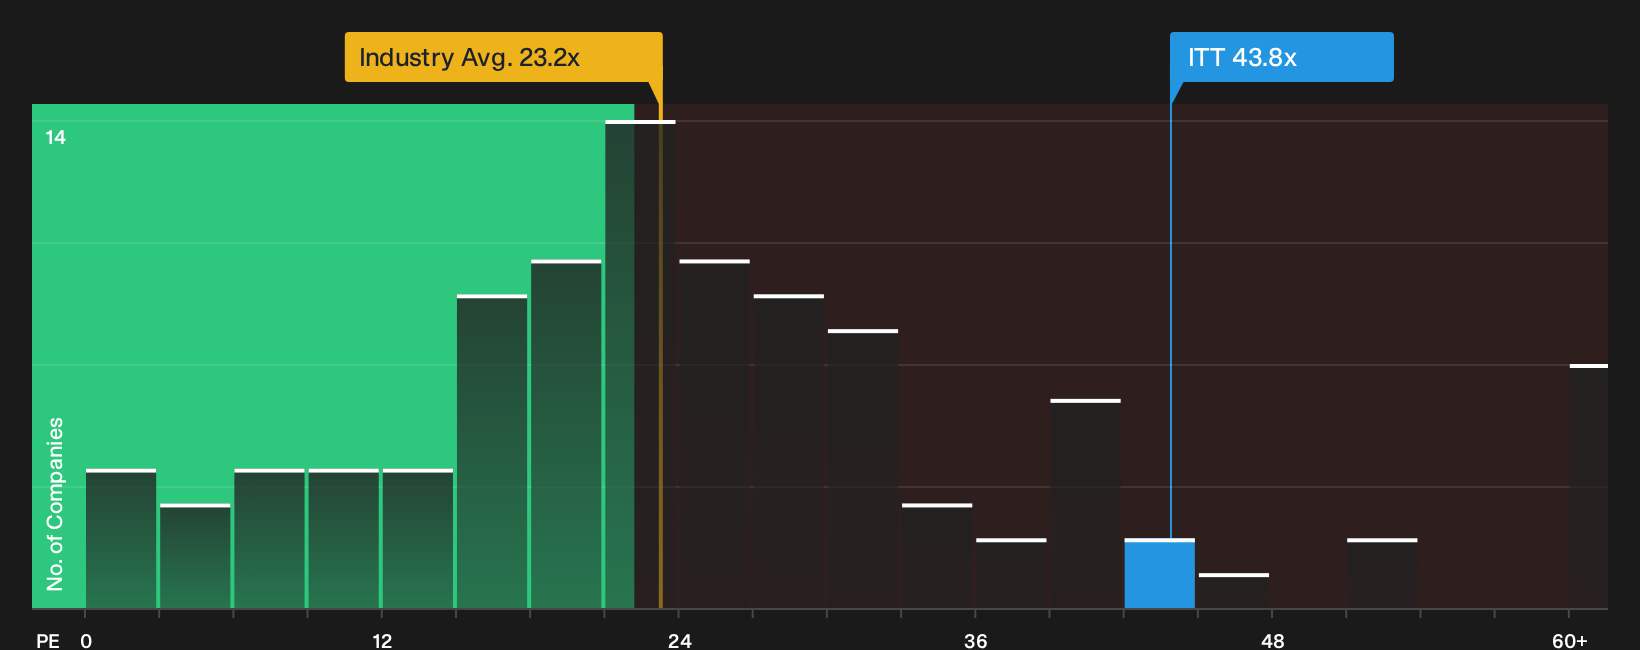
Step away from fair value models for a moment and look at what the market is already paying for ITT. The stock trades on a P/E of 43.8x, compared with 31.3x for peers and 23.1x for the wider US Machinery group. The fair ratio sits lower again at 29.6x.
That gap means a lot of future growth and execution is already embedded in today’s price. The key question for you is whether the earnings story can keep justifying this premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the ITT story so far should push you to test the numbers yourself and decide where you stand quickly. To weigh both sides of the debate in one place, spend a moment with the 3 key rewards and 2 important warning signs.
Looking for more ITT sized investment ideas?
If ITT has sharpened your focus, do not stop here. Use the screener to uncover fresh ideas that match your approach before the market gets there first.
- Target resilient performers and stress test your downside by running your criteria through the 29 resilient stocks with low risk scores.
- Highlight potential mispricings by scanning companies trading below what their quality might suggest using the 39 high quality undervalued stocks.
- Surface under followed opportunities with strong fundamentals before they hit the mainstream through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com